Market Overview of the Lubricating Oil Refining Market
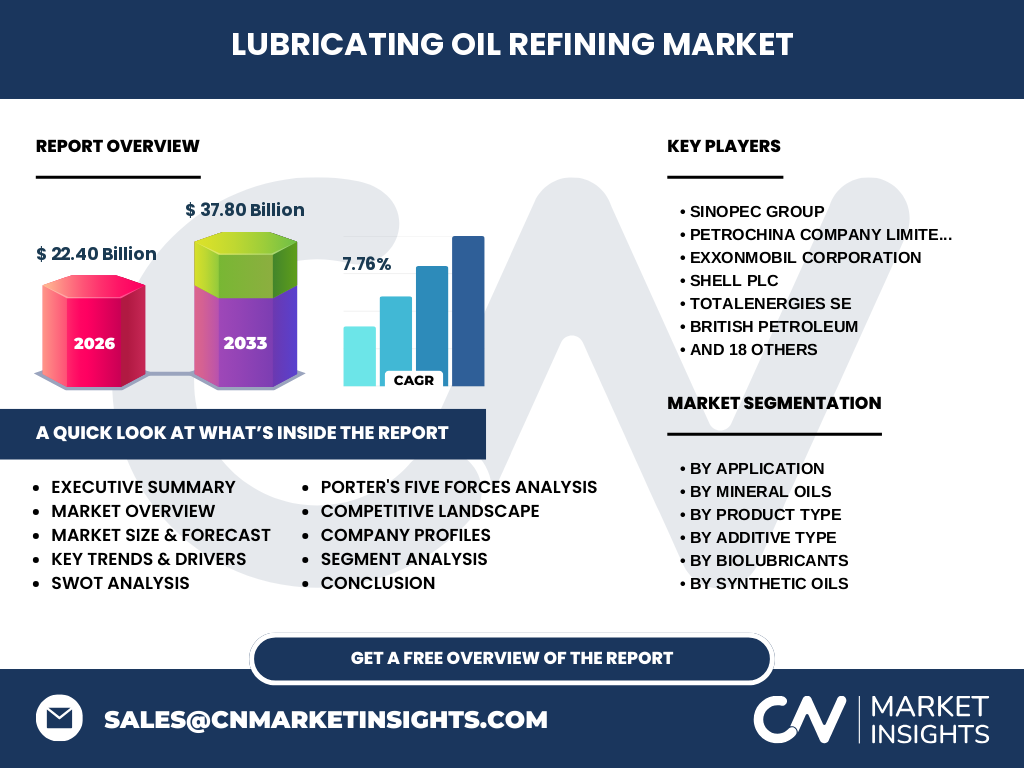
Our analysis indicates that the Lubricating Oil Refining Market stands at 22.40 Billion in 2026. This sector encompasses advanced hydroprocessing, solvent extraction, and re-refining technologies designed to convert crude oil fractions and used motor oils into high-performance base stocks, serving as the foundational lifeblood for industrial machinery and automotive lubrication globally.
Key market drivers, restraints, challenges, and opportunities shaping the Lubricating Oil Refining Market
Growth is propelled by rising industrial automation and stringent environmental mandates enforced by agencies like the EPA. However, high capital expenditures for hydrotreating units present a major restraint. Strategic opportunities emerge in expanding Group III base oil capacities to meet strict OEM specifications for low-viscosity engine oils.
Structural Growth Trends and Emerging Patterns
The shift toward sustainability has accelerated circular economy models within the Lubricating Oil Refining Market industry trends. Refiners are heavily investing in re-refining technologies to process used oils into pristine base stocks, mirroring consumer demand for eco-conscious supply chains championed by innovators like AVISTA Green and Heritage-Crystal Clean Inc.
COVID-19 Impact Analysis and Recovery Trajectory
The pandemic triggered severe supply chain disruptions and a temporary collapse in transportation fuel demand, which depressed base oil production runs. Recovery has been robust, driven by post-pandemic industrial resurgences and a rapid bounce-back in heavy logistics, pushing refiners to optimize capacity utilization rates across major processing hubs.
Competitive Benchmarking and Market Concentration
The market features intense competition among integrated energy majors like ExxonMobil Corporation, Shell plc, and Sinopec Group, who leverage captive feedstock supplies. Meanwhile, specialized players such as Nynas AB and Calumet Specialty Products Partners L.P. carve out high-margin niches in naphthenic and specialty process oils.
Executive Summary: High-Level Market Synthesis
Our comprehensive Lubricating Oil Refining Market analysis reveals a robust sector transitioning toward premium synthetic formulations and circular sustainability. Key findings underscore the critical role of advanced additive technologies in meeting evolving OEM performance standards across diverse industrial and automotive applications.
Market Forecast: Growth Trajectory from 2027 to 2033
The data suggests exceptional momentum, projecting the market to expand from its 2026 baseline to reach 37.80 Billion by 2033. This expansion reflects a steady Compound Annual Growth Rate (CAGR) of 7.76%, underpinned by rising global vehicle parc volumes and expanding industrial infrastructure in emerging economies.
Segmentation Breakdown and Operational Roles
Segmentation spans across applications (Automotive, Industrial, Marine, Specialty Oils), mineral categories (Paraffinic, Naphthenic), product types (Mineral, Synthetic, Biolubricants, Semi-synthetic), and additive types including detergents, antioxidants, and viscosity index improvers. Each segment plays a specialized role in tailoring lubricants for extreme temperature and load conditions.
Regional Market Analysis and Geographic Distribution
Geographic performance varies significantly, with Asia-Pacific dominating demand due to rapid manufacturing expansion in China and India. North America and Europe follow closely, driven by stringent regulatory frameworks that mandate high-performance synthetic formulations and sustainable bio-based alternatives from regional powerhouses like Petro-Canada Lubricants Inc.
In-Depth Regional Review
In North America, strict environmental compliance favors re-refined base oils and advanced PAO-based synthetics. Conversely, the Asia-Pacific market exhibits surging demand for high-volume automotive and industrial oils, supported by massive refining capacities operated by industry titans like PetroChina Company Limited and Indian Oil Corporation Limited.
Company Profiles and Strategic Positioning
Industry leaders employ distinct strategies to maintain dominance. TotalEnergies SE and Chevron Corporation focus on proprietary synthetic ester developments, while regional specialists like Hyrax Oil and Pentas Flora concentrate on localized blending and sustainable re-refining capabilities to capture emerging regional market share.
Porter's Five Forces Analysis
Bargaining power of suppliers is moderate, constrained by crude oil feedstock availability. Threat of substitutes remains low for high-performance applications but pressures traditional mineral oils via synthetic and bio-based alternatives. Competitive rivalry is fierce among global integrated giants vying for technological leadership in low-viscosity formulations.
SWOT Analysis of the Refining Sector
Strengths lie in established global distribution networks and advanced hydroprocessing capabilities. Weaknesses include high sensitivity to volatile crude feedstock prices. Opportunities abound in bio-based industrial lubricants, while threats stem from aggressive global electrification targets dampening long-term combustion engine lubricant demand.
Value Chain Analysis from Raw Materials to End-Users
The value chain initiates with upstream crude extraction or used oil collection, progressing through severe hydroprocessing, solvent dewaxing, and precise additive blending. Finished products flow through specialized logistics networks to end-users in automotive, marine, and heavy industrial sectors, maximizing margin capture at the blending and packaging stages.
Investment Insights and High-Potential Areas
Investors should direct capital toward advanced re-refining infrastructure and bio-based synthetic ester technologies. Companies pioneering sustainable, closed-loop lubricant ecosystems—such as AVISTA OIL AG—present prime acquisition and partnership targets as ESG mandates reshape institutional capital allocation in the energy sector.
Conclusion and Strategic Takeaways
The Lubricating Oil Refining Market market size expansion to 37.80 Billion by 2033 highlights the sector's resilience and adaptability. Stakeholders must pivot toward high-margin synthetic grades, embrace circular re-refining models, and navigate complex regional environmental regulations to secure long-term profitability.
Research Methodology and Data Triangulation
Our baseline estimates are rigorously triangulated by cross-referencing trade registry data from international energy agencies, conducting primary stakeholder interviews with refinery executives, and analyzing secondary macroeconomic indicators including industrial output indices and automotive production statistics.
Scope of the Report and Coverage Parameters
This report covers global refining activities, base stock production capacities, and finished lubricant formulations across automotive, industrial, and marine sectors. Limitations include fluctuating geopolitical impacts on crude feedstock pricing and confidential proprietary operational data from privately held regional blending entities.
Recent Developments and Strategic Industry Moves
Recent market activities feature major strategic partnerships focused on low-carbon base oil production. Key players like Neste Oyj and SK Lubricants Co. Ltd. have intensified joint ventures aimed at scaling renewable feedstock integration and eco-friendly synthetic lubricant manufacturing to comply with tightening global carbon emission limits.