What is the market overview of the Smart Office Market?
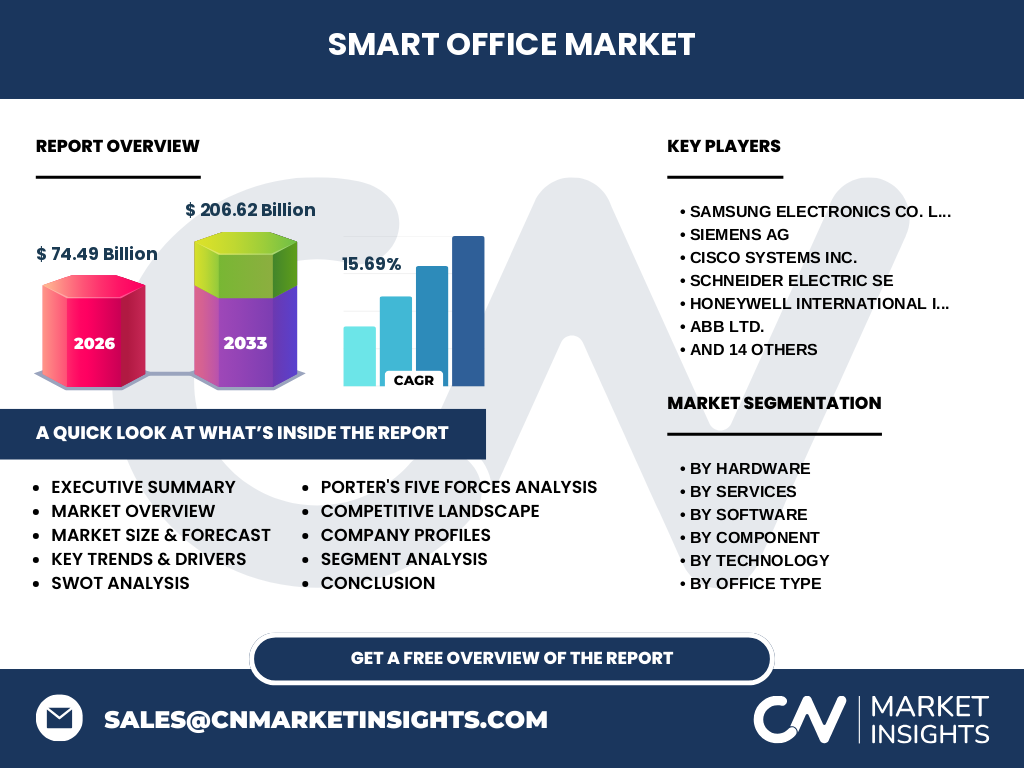
Our analysis indicates that the Smart Office Market size stands at 74.49 Billion in 2026. This sector encompasses integrated hardware, software, and services designed to optimize workplace efficiency, employee productivity, and energy consumption through advanced automation and IoT connectivity.
Structural Growth Drivers and Market Constraints
Growth is propelled by rising demand for energy-efficient building operations and hybrid work models. However, high initial capital expenditures for retrofitting legacy commercial real estate and stringent cybersecurity regulations governing data privacy remain key operational constraints.
Emerging Trends Shaping Workplace Technology
The shift toward AI-driven workspace analytics and cloud-enabled occupancy management is redefining corporate real estate. Innovators like Robin Powered Inc. and Deskbird AG are leading this transition with predictive desk-sharing algorithms.
COVID-19 Impact and Post-Pandemic Recovery
The pandemic permanently altered corporate real estate strategies, accelerating deployments of touchless access control and advanced HVAC air filtration. Recovery has transitioned into sustained expansion as enterprises reconfigure physical footprints for flexible, hybrid operational models.
Competitive Benchmarking and Market Dynamics
The landscape features intense competition among automation giants and agile software specialists. Corporations like Schneider Electric SE and Honeywell International Inc. dominate hardware deployment, while specialized players focus on granular analytics and software integration.
Executive Summary of the Smart Office Market
Our comprehensive Smart Office Market analysis projects explosive expansion, surging from 74.49 Billion in 2026 to 206.62 Billion by 2033 at a robust 15.69% CAGR. Digital transformation in corporate facilities is now a board-level priority.
Market Forecast and Trajectory Through 2033
Driven by rapid urbanization and corporate sustainability mandates, the market is poised to achieve a stellar 15.69% CAGR from 2027 to 2033. This trajectory reflects widespread adoption of IoT and AI across global enterprise footprints.
Segmentation Breakdown of Hardware, Software, and Services
The market breaks down into Hardware (Smart Lighting, Security, HVAC, Audio/Video), Software (Facility Management, Workplace Analytics, Energy Management), and Services (Managed and Consulting). Hardware currently commands the largest share due to foundational sensor deployments.
Geographic Distribution and Regional Performance
North America leads adoption due to early-stage proptech investments, closely followed by Europe driven by stringent energy efficiency directives like the EU Green Deal. Asia-Pacific represents the fastest-growing regional market fueled by smart city initiatives in commercial hubs.
In-Depth Regional Review and Localized Constraints
North American growth is anchored by corporate tech campuses, whereas European markets contend with strict compliance frameworks regarding workplace data collection. APAC expansion faces logistical hurdles in integrating smart systems into fragmented real estate markets.
Strategic Positioning of Leading Industry Participants
Market leaders utilize distinct strategic approaches; for instance, Cisco Systems Inc. leverages robust networking infrastructure for video conferencing, while Signify N.V. focuses on smart lighting IoT ecosystems to capture enterprise sustainability budgets.
Porter's Five Forces Assessment
Bargaining power of suppliers is moderate due to specialized IoT chipset manufacturing, while buyer power remains high given numerous software alternatives. Threat of new entrants is mitigated by high R&D costs and established enterprise vendor relationships.
SWOT Analysis of the Smart Office Ecosystem
Strengths include high ROI on energy savings; weaknesses involve integration friction with legacy systems. Opportunities lie in AI-driven predictive maintenance, while threats center on rising cybersecurity vulnerabilities in interconnected building automation systems.
Value Chain Analysis from Raw Materials to End-Users
The value chain originates with semiconductor and raw material suppliers, moving through hardware manufacturers and software developers like Spacewell International NV, culminating in enterprise end-users across healthcare, retail, and financial sectors.
Investment Insights and High-Potential Areas
High-potential investment opportunities concentrate in AI-powered workplace analytics and automated energy management software. Investors should prioritize firms offering interoperable SaaS platforms that seamlessly integrate with existing building automation hardware.
Conclusion and Strategic Takeaways
The Smart Office Market industry trends highlight an irreversible shift toward intelligent, automated, and sustainable workplaces. Stakeholders must embrace cloud integration and robust cybersecurity to capture value in this fast-growing sector.
Research Methodology and Data Triangulation
Our baseline estimates are rigorously triangulated by combining trade registry data, primary stakeholder interviews with C-level proptech executives, and secondary macroeconomic indicators from global commercial real estate databases.
Scope of the Report and Analytical Parameters
This report covers global revenue estimations and growth forecasts from 2027 to 2033, segmented by hardware, software, services, component, technology, office type, and end-user industry, excluding residential home automation applications.
Recent Developments and Strategic Industry Moves
Recent market activity is characterized by strategic acquisitions and IoT platform partnerships. For example, Logitech International S.A. and Crestron Electronics Inc. have launched advanced hybrid meeting room integrations to capture rising enterprise demand.