Market overview of the Machinery, Equipment, And Supplies Wholesalers Market
Our analysis indicates that the Machinery, Equipment, And Supplies Wholesalers Market represents a critical B2B nexus, facilitating global supply chains for industrial hardware, OEM components, and heavy capital goods. Serving as the primary intermediary between original manufacturers and commercial end-users, this sector underpins industrial output across automotive, aerospace, and energy verticals.
Structural Growth Drivers and Market Restraints
The market is propelled by accelerating industrial automation and supply chain digitization. However, supply chain bottlenecks and volatile raw material costs for steel and polymers act as persistent restraints. Wholesalers must navigate complex logistics and fluctuating tariffs imposed by regulatory bodies like the Department of Commerce.
The Shift Toward Autonomous Fulfillment Operations
Industry participants are aggressively investing in fully automated systems and robotics-based warehouse operations to combat labor shortages. Leaders like WW Grainger Inc and Fastenal Company leverage proprietary inventory algorithms to optimize fulfillment speed across complex B2B distribution nodes.
Pandemic Aftershocks and COVID-19 Impact Analysis
The COVID-19 pandemic exposed severe vulnerabilities in global industrial supply chains, triggering massive inventory hoarding followed by sudden corrections. Recovery trajectories now prioritize regionalized warehousing, multi-sourcing strategies, and digital procurement portals to insulate operations against future macroeconomic disruptions.
Competitive Benchmarking and Market Concentration
The competitive landscape features a mix of multinational giants and specialized regional distributors. Wesco International Inc, Ferguson plc, and Rexel SA dominate through massive scale and M&A strategies, while independent wholesalers compete via deep technical expertise and localized inventory availability.
Executive Summary: Machinery, Equipment, And Supplies Wholesalers Market Dynamics
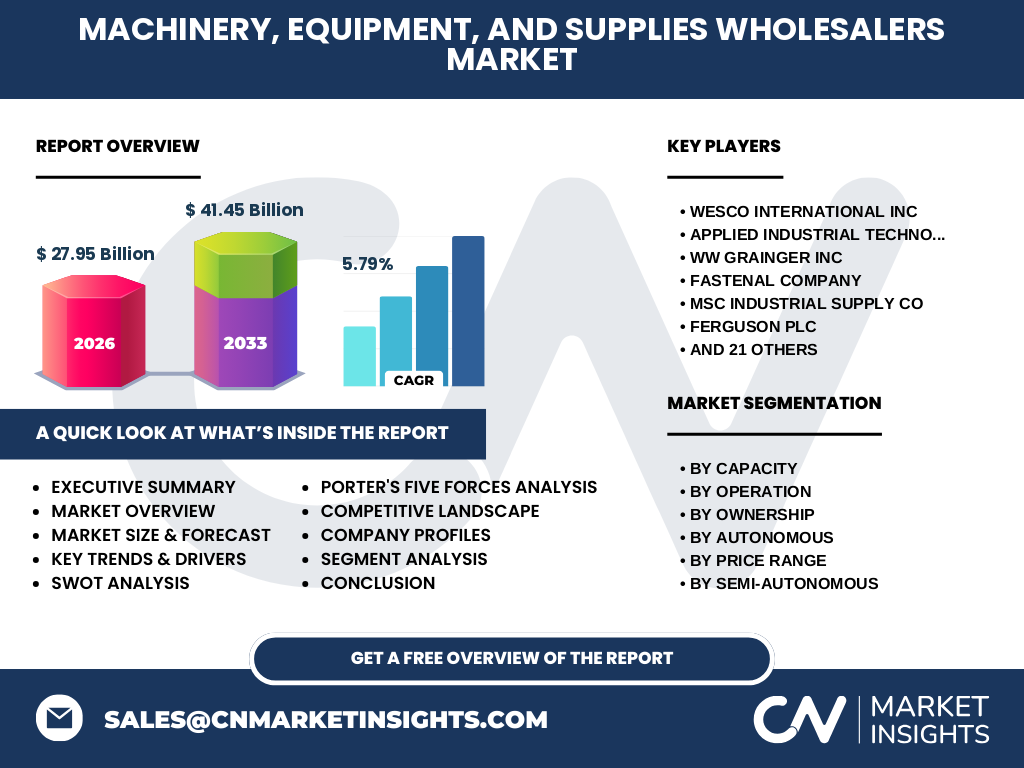
Our research establishes a market size of 27.95 Billion in 2026, expanding to 41.45 Billion by 2033 at a CAGR of 5.79%. This robust expansion reflects heightened demand for advanced capital equipment, IoT-enabled machinery, and agile B2B distribution networks across global industrial hubs.
Long-Term Market Forecast Through 2033
Driven by sustained infrastructure investments and green energy transitions, the sector is projected to surge from 27.95 Billion in 2026 to 41.45 Billion by 2033. This trajectory underscores a steady 5.79% CAGR, rewarding distributors capable of integrating predictive maintenance tools into their core offerings.
Segmentation Analysis of Wholesale Operations
The market segments by capacity (Small, Medium, Large), operation (Autonomous, Semi-Autonomous), ownership (Wholesale Chains, Independent Wholesalers), price range (Premium, Mid-Range, Economy), and industry vertical (Automotive, Aerospace, Construction, Food and Beverage, Energy, Healthcare, Packaging). Large-scale autonomous systems currently capture the highest revenue share.
Geographic Distribution and Regional Market Analysis
Regional performance varies based on local manufacturing output and government infrastructure spending. North America and Europe lead in advanced automation adoption, while Asia-Pacific exhibits the fastest Machinery, Equipment, And Supplies Wholesalers Market growth fueled by rapid industrialization in emerging manufacturing corridors.
In-Depth Regional Review of Key Industrial Corridors
North American growth is anchored by robust construction and energy sectors, with major distribution hubs centered around key logistics nodes. Meanwhile, European markets face stringent environmental regulations from the European Union, compelling wholesalers to stock energy-efficient machinery and recyclable packaging supplies.
Strategic Company Profiles and Market Positioning
Industry stalwarts like Sonepar Group, Bunzl plc, and Watsco Inc maintain dominant market positions through targeted vertical specialization. Meanwhile, tech-focused distributors such as Avnet Inc and Arrow Electronics Inc bridge the gap between heavy industrial machinery and embedded electronic components.
Porter's Five Forces Assessment
Buyer power remains moderate due to the commoditized nature of standard supplies, offset by high switching costs for specialized machinery. Supplier rivalry is intense among top-tier manufacturers like Wurth Group and MRC Global Inc, while threat of new entrants is mitigated by steep capital requirements for global logistics networks.
SWOT Analysis of the Wholesale Ecosystem
Strengths include vast distribution networks and established OEM relationships. Weaknesses involve legacy IT infrastructure. Opportunities lie in e-commerce B2B marketplaces and IoT integration. Threats stem from macroeconomic inflation, geopolitical trade tensions, and direct-to-consumer manufacturer sales models.
Value Chain Analysis from Raw Materials to End-Users
The value chain initiates with raw metal and polymer suppliers feeding OEM manufacturers, followed by wholesale intermediaries like DistributionNOW Inc and Graybar Electric Company Inc. Wholesalers add immense value through credit financing, localized warehousing, kitting, and just-in-time delivery to construction and aerospace end-users.
Strategic Investment Insights and High-Potential Areas
Investors should target distributors integrating AI-driven inventory forecasting and hybrid semi-autonomous systems. Companies capable of servicing high-margin verticals like renewable energy infrastructure and advanced healthcare manufacturing offer superior risk-adjusted return profiles over the forecast window.
Conclusion and Key Takeaways for Stakeholders
The Machinery, Equipment, And Supplies Wholesalers Market is undergoing a digital and operational metamorphosis. Reaching 41.45 Billion by 2033, the industry rewards forward-thinking players who embrace automation, optimize supply chain resilience, and cultivate deep technical partnerships across specialized industrial verticals.
Research Methodology for Baseline Estimates
Our analytical framework triangulates trade registry data, primary executive interviews with supply chain directors across firms like MSC Industrial Supply Co and Ferguson Enterprises USA, and macroeconomic indicators from agencies like the Federal Reserve to establish robust, verifiable baseline market sizing.
Scope of the Report and Coverage Parameters
This report covers global B2B distribution dynamics for industrial machinery, commercial equipment, and operational supplies from 2026 through 2033. Excluded from this scope are direct retail consumer sales, raw chemical extraction, and non-machinery commodity trading sectors not aligned with industrial wholesale definitions.
Recent Industry Developments and Strategic Moves
Recent market activity is characterized by aggressive cross-border acquisitions and digital platform launches. Firms such as Consolidated Electrical Distributors and Border States Electric have forged strategic technology partnerships to enhance real-time inventory visibility and accelerate last-mile B2B delivery schedules.