Market overview and structural scope of the Remote Weapon Systems Market
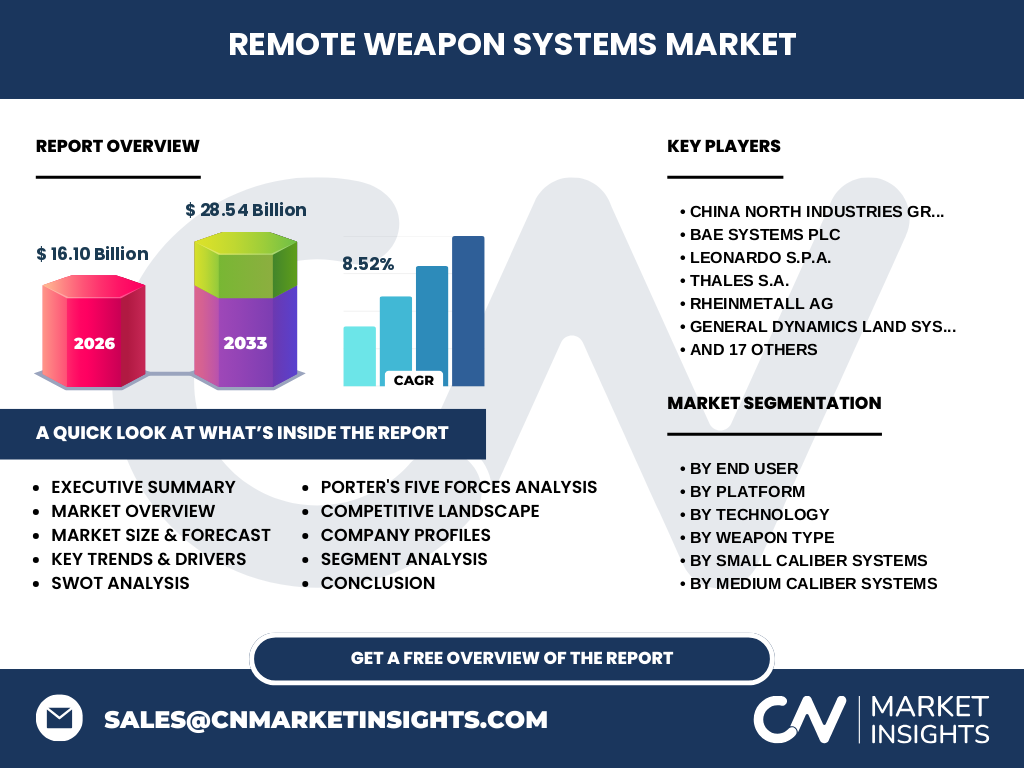
Our analysis indicates the Remote Weapon Systems Market represents a critical paradigm shift in modern military engineering, bridging the gap between crewed armaments and unmanned lethality. Valued at 16.10 Billion in 2026, the sector encompasses stabilized weapon platforms integrated with advanced optronics and ballistic fire control computers, allowing operators to engage targets remotely from protected vehicle interiors or command bunkers.
Core catalysts and friction points shaping the Remote Weapon Systems Market
The market is propelled by an urgent global demand for minimized soldier casualties and enhanced asymmetric threat neutralization. However, supply chain constraints involving rare-earth minerals and stringent ITAR export compliance regulations act as notable friction points. Industry leaders like Kongsberg Defence And Aerospace AS and Elbit Systems Ltd. navigate these hurdles through localized manufacturing and modular architectural designs.
Structural Growth Drivers in the Remote Weapon Systems Market
The transition toward network-centric warfare heavily influences industry expansion. Key growth drivers include the proliferation of urban combat scenarios, the imperative for multi-spectral targeting systems, and military modernization initiatives across Eastern Europe and the Indo-Pacific. Defense ministries increasingly mandate open-architecture digital backbones to facilitate seamless integration with tactical battle management software.
Pandemic repercussions and recovery trajectories in the Remote Weapon Systems Market
While COVID-19 disrupted global semiconductor supply chains and delayed prototype field testing, the post-pandemic recovery has been remarkably robust. Geopolitical tensions accelerated defense budgets, turning supply chain resilience into a top strategic priority. Companies adapted by dual-sourcing critical thermal imaging components and hardening digital supply networks against cyber vulnerabilities.
Competitive Benchmarking within the Remote Weapon Systems Market
The competitive landscape features a distinct tier of prime contractors, including BAE Systems plc, Rheinmetall AG, and Leonardo S.p.A., competing alongside specialized innovators like Rafael Advanced Defense Systems Ltd. and Electro Optic Systems Holdings Limited. Market concentration is moderately high, with legacy defense giants leveraging deep government relationships while agile pure-play turret manufacturers capture niches through rapid software iteration.
Executive Summary of the Remote Weapon Systems Market research overview
Our comprehensive research projects the Remote Weapon Systems Market to scale from 16.10 Billion in 2026 to 28.54 Billion by 2033, expanding at a robust 8.52% CAGR. Grounded in rigorous primary interviews and macroeconomic trade registry data, this report equips defense strategists with actionable intelligence on high-growth segments, regional hotspots, and competitive positioning.
Market forecast trajectory from 2027 to 2033
Driven by persistent geopolitical friction and accelerated defense procurement cycles, the market trajectory charts an impressive climb from 2027 to 2033, culminating in a valuation of 28.54 Billion at a steady 8.52% CAGR. This expansion is heavily underwritten by multi-year procurement contracts for armored vehicle upgrades and specialized naval force protection suites.
Segmentation analysis across end-users, platforms, technologies, and weapon types
The market demonstrates deep diversification across operational parameters:
- By End User: Military, Homeland Security, Law Enforcement, Critical Infrastructure Security Agencies, Border Patrol Agencies.
- By Platform: Land Systems, Marine Systems, Airborne Systems.
- By Technology: Remote Controlled, Autonomous, Semi Autonomous.
- By Weapon Type: Small Caliber Systems, Medium Caliber Systems, Missile Integrated Systems, Non Lethal Payload Systems.
Geographic distribution and regional performance dynamics
Regional performance mirrors active territorial disputes and defense budget expansions. North America leads in technological sophistication and research funding, while Europe exhibits rapid procurement growth driven by continental defense initiatives. The Asia-Pacific region demonstrates the fastest volume adoption, fueled by maritime border disputes and the modernization drives of nations like Singapore and South Korea.
In-depth regional review of high-growth operational theaters
Our analysis highlights how localized logistical hurdles and regulatory frameworks shape regional demand. In Europe, interoperability standards mandated by the European Defence Agency dictate strict modularity requirements. Meanwhile, Asia-Pacific markets prioritize saltwater-corrosion resistance for maritime systems and high-elevation performance for mountainous land borders, favoring localized specialists such as Singapore Technologies Engineering Ltd.
Strategic positioning of major industry participants
Leading industry players deploy distinct strategic maneuvers to capture market share. Kongsberg dominates western land platform integration, whereas ASELSAN Elektronik Sanayi ve Ticaret A.S. secures vital contracts through cost-competitive, high-durability optronic turrets. Concurrently, firms like General Dynamics Land Systems and Hanwha Aerospace Co. Ltd. embed remote systems directly into their next-generation infantry fighting vehicle platforms.
Porter's Five Forces analysis of the Remote Weapon Systems Market
Industry rivalry is intense, tempered only by high barriers to entry including strict military qualification testing and massive capital expenditures for R&D. Supplier power is moderate due to specialized electro-optical and gyroscope dependencies. Buyer power rests heavily with sovereign defense ministries, while the threat of substitution remains low given the unique tactical superiority of remote armaments.
SWOT evaluation of the global ecosystem
Strengths include high operational safety for personnel and superior target acquisition accuracy. Weaknesses involve complex maintenance pipelines and high unit acquisition costs. Opportunities lie in integrating artificial intelligence for autonomous threat prioritization. Threats are characterized by rapid adversary electronic warfare jamming capabilities and stringent international arms control treaties.
Value chain analysis from raw material procurement to end-user deployment
The value chain originates with raw material extraction—specifically titanium, carbon fiber, and rare-earth elements for laser rangefinders. Component manufacturers then supply high-precision servos, ballistic computers, and weapon mounts to tier-one integrators like Thales S.A. or Saab AB. Final integration occurs before rigorous environmental testing, culminating in deployment by military end-users.
Strategic investment insights and high-potential areas
Investors should direct capital toward artificial intelligence edge-processing units and anti-jamming guidance links, which represent the next competitive frontier. Sub-segments focusing on counter-unmanned aerial system (C-UAS) integration and loitering munition compatibility, such as advanced missile integrated systems, offer the highest risk-adjusted yield over the forecast period.
Conclusion and key strategic takeaways
The data confirms that the Remote Weapon Systems Market is transitioning from a supplementary vehicle upgrade to a core pillar of modern defense architecture. Reaching 28.54 Billion by 2033, success in this sector demands continuous software innovation, compliance with strict defense standards, and strategic partnerships with established defense primes.
Research methodology behind our triangulated baseline estimates
Our research methodology employs a rigorous data triangulation model. We cross-reference primary qualitative insights from structured interviews with senior defense procurement officers and chief technology officers with quantitative data extracted from national trade registries, defense ministry budget allocations, and secondary macroeconomic indicators to ensure absolute market sizing accuracy.
Scope of the report, coverage parameters, and operational limitations
This report covers global market dynamics for remote weapon systems from 2026 to 2033, segmenting data by end user, platform, technology, and weapon type. Limitations include restricted access to classified black-budget military programs and sudden shifts in export control legislation enforced by regulatory bodies such as the US State Department.
Recent developments, strategic partnerships, and product launches
Recent industry momentum is defined by strategic joint ventures, such as KNDS N.V. partnering with specialized turret developers, and the unveiling of AI-enabled loitering munition integration by firms like Valhalla Turrets and Pro Optica S.A. These moves underscore a collective industry push toward multi-domain lethality and automated threat engagement.