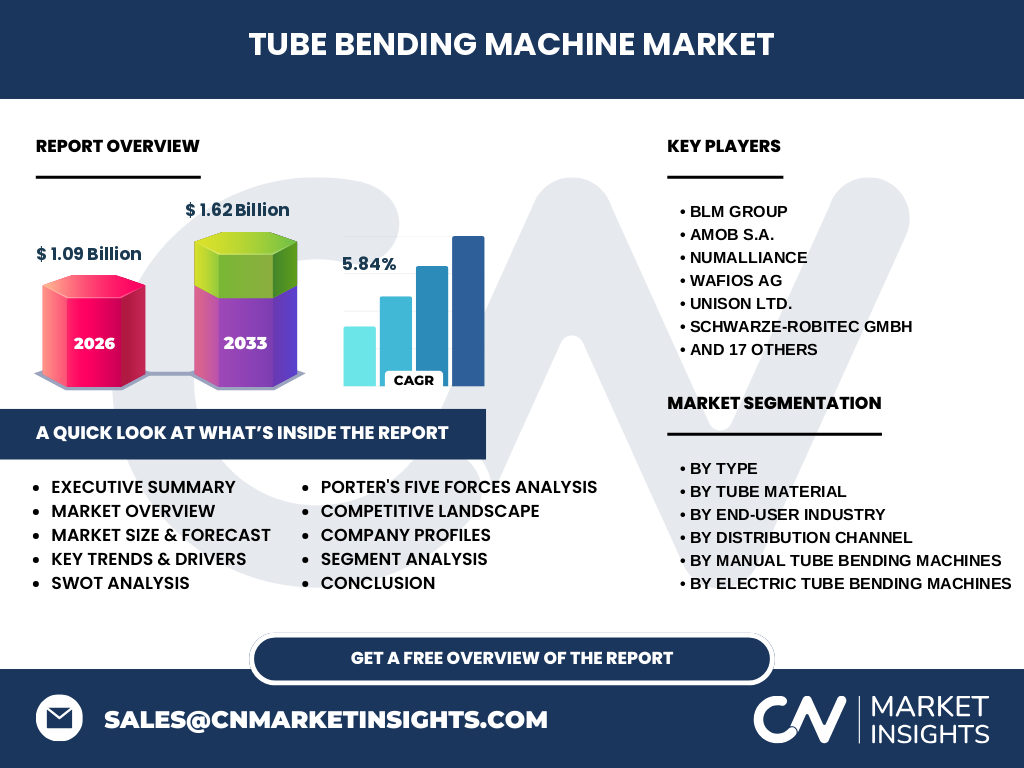
Market overview of the Tube Bending Machine Market
The Tube Bending Machine Market is valued at 1.09 Billion in 2026, serving as a critical pillar for heavy fabrication involving high-strength structural steel, titanium, and copper raw materials. Our analysis indicates that this market underpins complex manufacturing across major global ports and industrial hubs, governed by strict ISO and OSHA safety standards.
Structural Growth Drivers and Restraints in the Tube Bending Machine Market
Growth is propelled by strict lightweighting mandates in electric vehicles and aerospace frame manufacturing. However, our research highlights supply chain bottlenecks for heavy-duty servo motors and compliance hurdles with regional machinery directives like CE marking as primary operational restraints dampening rapid capacity expansion.
Emerging trends and growth patterns in Tube Bending Machine Market industry trends
The market is rapidly shifting toward fully automated, multi-axis servo configurations that integrate real-time springback compensation. Industry innovators like Unison Ltd. and BLM GROUP are pioneering these software-driven setups, allowing tier-1 suppliers to drastically reduce material waste when bending exotic alloys.
COVID-19 impact analysis and recovery trajectory
The pandemic severely disrupted global supply chains, delaying capital expenditure for heavy industrial machinery across ports in Antwerp and Shanghai. Post-pandemic recovery has been robust, driven by automated reshoring initiatives where facilities deploy all-electric servo tube bending machines to minimize reliance on manual labor.
Competitive Benchmarking: Major Players and Strategic Dynamics
The competitive landscape features specialized heavyweights such as WAFIOS AG, Numalliance, and AMOB S.A. Market concentration is moderately high in high-end multi-axis CNC systems, where proprietary kinematics and advanced bending simulation software dictate pricing power and customer retention among aerospace contractors.
Executive summary of key findings for the Tube Bending Machine Market
Our comprehensive assessment reveals a resilient market anchored by technological convergence. Strategic investments in software integration and high-speed rotary draw benders are redefining competitive moats, transforming traditional metal fabrication into smart, interconnected production environments.
Market forecast and trajectory for the Tube Bending Machine Market
Driven by robust demand across industrial machinery and infrastructure, the Tube Bending Machine Market size is projected to expand from 1.09 Billion in 2026 to 1.62 Billion by 2033, achieving a steady compound annual growth rate of 5.84% over the forecast period.
Segmentation analysis across core product and application categories
The market is segmented by type into Computer Numerical Control, hydraulic, electric, pneumatic, and manual machines. Material applications split between metal and plastic tubes, while end-users span automotive, aerospace, and construction. Each segment requires specialized tooling to handle varying wall thicknesses and centerline radii.
Regional market analysis and geographic performance distribution
Geographic performance highlights Asia-Pacific as the manufacturing epicenter, fueled by dense automotive clusters in Japan and China. Meanwhile, North America and Europe prioritize advanced multi-axis Computer Numerical Control Tube Bending Machines to service stringent aerospace and defense compliance mandates.
In-depth regional review of manufacturing hubs
European markets concentrate heavily on premium, custom-engineered solutions from Italian and German innovators like Crippa S.p.A. and Schwarze-Robitec GmbH. Conversely, the Asia-Pacific landscape favors high-throughput, standardized CNC and hydraulic units deployed near major container terminals for swift global export.
Company profiles and strategic positioning of industry leaders
Industry leaders like BLM GROUP and AMOB S.A. maintain dominant positions through end-to-end integration of laser cutting and bending cells. Meanwhile, specialists like YLM Group Co. Ltd. and SOCO Machinery Co. Ltd. capture significant market share by offering robust, cost-effective CNC and hydraulic solutions.
Porter's Five Forces analysis of competitive intensity
Bargaining power of buyers is moderate-to-high due to numerous equipment builders, while supplier power remains constrained by standardized hydraulic components and servomotors. Threat of substitution is low given the irreplaceable precision of dedicated tube benders in complex fluid-carrying assemblies.
SWOT analysis of the global sector
Strengths lie in high-precision automation and proprietary simulation software. Weaknesses involve high initial capital outlays. Opportunities emerge from EV chassis manufacturing, while threats stem from macroeconomic volatility impacting heavy industrial capital expenditure budgets worldwide.
Value chain analysis from raw materials to end-users
The value chain initiates with alloy steel and electronic component suppliers, flowing through precision machine assembly by firms like Pines Engineering and Wafios AG. It culminates with tier-1 automotive and aerospace fabricators utilizing these systems to deliver finished structural assemblies.
Investment insights and high-potential growth areas
High-potential capital allocation centers on all-electric servo tube bending machines and AI-driven offline programming software. Investors should target niche automation integrators capable of reducing setup times for high-mix, low-volume job shops.
Conclusion and strategic takeaways for industry stakeholders
The trajectory through 2033 emphasizes software-hardware convergence. Companies failing to upgrade their machinery portfolios to support intelligent, multi-axis CNC bending will lose margin share to technologically agile competitors.
Research methodology for baseline estimates and validation
Our baseline estimates are rigorously triangulated by combining customs trade registry data, primary executive interviews with chief technology officers across top manufacturers, and secondary macroeconomic indicators tracking global industrial production indices.
Scope of the report and analytical boundaries
This report covers global revenue performance and volume shipments across defined machine types and end-user verticals from 2026 to 2033. It explicitly excludes non-machined pipe joining methods like welding and standard fitting distribution.
Recent developments, partnerships, and strategic product launches
Recent market dynamism includes strategic joint ventures focused on green manufacturing and the launch of IoT-enabled bending cells by innovators like Unison Ltd. and BLM GROUP, designed to enable predictive maintenance and remote diagnostics for global clients.