What is the structural scope and industry significance of the Cranial Fixation And Stabilization Systems Market?
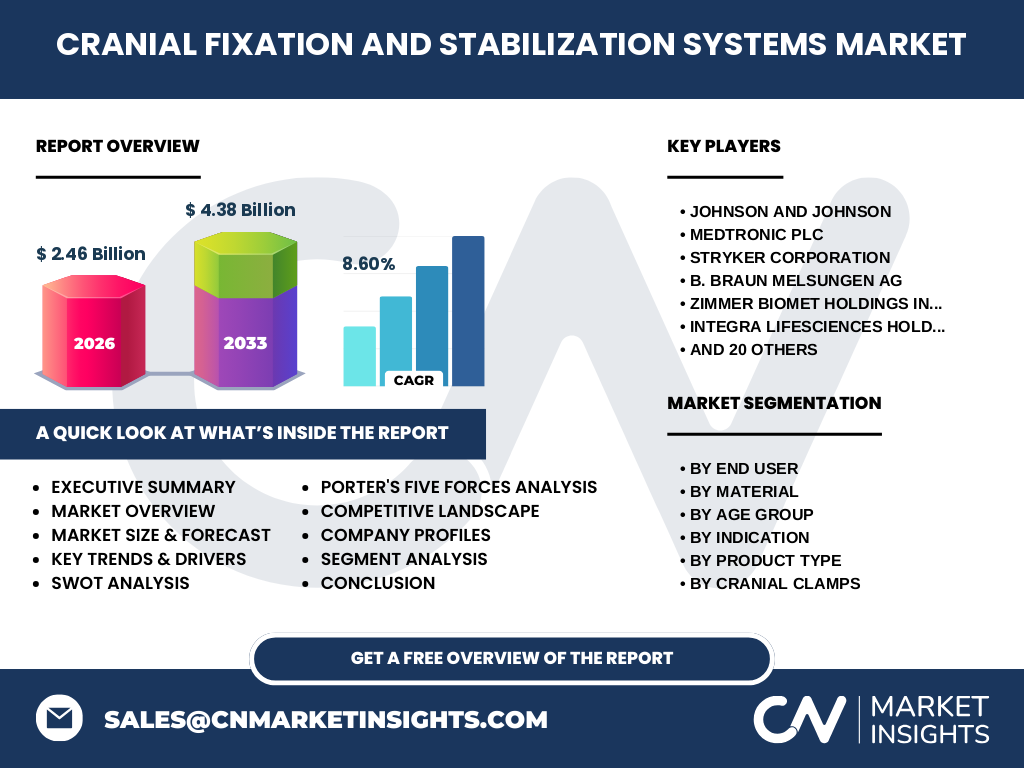
Our analysis indicates that the Cranial Fixation And Stabilization Systems Market encompasses specialized medical devices utilized in neurosurgery, valued at $2.46 Billion in 2026. This sector holds critical industry significance as hospitals and ambulatory surgical centers rely on precision titanium and resorbable implants for traumatic brain injury and tumor surgeries, governed by stringent FDA and CE mark regulatory pathways.
Structural Growth Drivers and Market Restraints
The market is propelled by a rising incidence of traumatic brain injuries and neurological disorders, driving demand for advanced cranial plates and screws. However, strict reimbursement caps and high capital expenditure for radiolucent cranial clamps act as primary restraints. Regulatory compliance hurdles imposed by bodies like the FDA significantly lengthen time-to-market for innovative patient-specific solutions.
The Shift Toward Patient-Specific Solutions
A defining industry trend is the rapid adoption of custom cranial meshes and patient-specific cranial plates designed via advanced 3D printing. This shift improves anatomical matching during complex reconstruction and deformity correction procedures. Market leaders like Renishaw plc and Stryker Corporation are capitalizing on this demand, shifting clinical preference away from conventional pre-shaped metallic implants.
COVID-19 Impact and Recovery Trajectory
The pandemic severely disrupted elective neurosurgical procedures, causing supply chain bottlenecks for medical-grade titanium and resorbable polymers. Nevertheless, the post-pandemic recovery trajectory has been robust, driven by a renewed backlog clearance in hospitals and specialized clinics, pushing the market toward a projected valuation of $4.38 Billion by 2033.
Competitive Benchmarking and Strategic Dynamics
The competitive landscape features high concentration among multinational medtech giants like Medtronic plc, Johnson And Johnson, and Zimmer Biomet Holdings Inc., who leverage extensive global distribution networks. Meanwhile, agile innovators like KLS Martin Group and Medartis AG maintain strong footholds by specializing in proprietary self-drilling cranial screws and bioresorbable fixation portfolios.
Executive Summary of Key Analytical Findings
Our comprehensive research confirms that the Cranial Fixation And Stabilization Systems Market is poised for accelerated expansion, registering a robust 8.60% CAGR from 2027 to 2033. Strategic M&A activity, technological convergence with digital planning software, and rising geriatric patient demographics remain the primary catalysts reshaping competitive positioning across global healthcare systems.
Long-Term Market Forecast from 2027 to 2033
Based on our econometric modeling, the market will scale from its baseline of $2.46 Billion in 2026 to reach $4.38 Billion by the end of 2033. This consistent expansion is underpinned by escalating healthcare expenditures in emerging economies and broader clinical adoption of magnesium alloys and advanced resorbable polymers.
Segmentation Analysis Across End Users, Materials, and Indications
The market segments by end user into hospitals, ambulatory surgical centers, and specialty clinics. Material categories span non-resorbable metals, resorbable polymers, and magnesium alloys. Indications range from traumatic brain injury and tumor surgery to vascular, hydrocephalus, and reconstruction procedures, each requiring specialized product types like three-pin clamps and locking screws.
Geographic Distribution and Regional Performance
Regional performance varies significantly, with North America leading market revenue due to advanced neurosurgical infrastructure and high reimbursement clarity. Meanwhile, Asia-Pacific represents the fastest-growing regional market, propelled by expanding hospital networks in China and India, alongside rising local manufacturing capabilities by firms like Changzhou Huida Medical Instrument Co. Ltd.
In-Depth Regional Review of Healthcare Infrastructure
Evaluating regional dynamics reveals that Europe maintains steady demand driven by stringent medical device regulations and established players like B. Braun Melsungen AG and Adeor Medical AG. Conversely, Latin America and the Middle East face localized logistical hurdles and budget constraints, though urban medical hubs increasingly adopt premium titanium cranial meshes.
Strategic Positioning of Leading Industry Players
Major enterprises such as Integra LifeSciences Holdings Corporation, MicroPort Scientific Corporation, and Orthofix Medical Inc. deploy distinct differentiation strategies. While conglomerates focus on broad product bundling across cranial clamps and plates, niche specialists like Osteopore International Pte Ltd capture market share through proprietary bioresorbable scaffolding innovations.
Porter's Five Forces Industry Competitiveness Assessment
The industry exhibits moderate-to-high supplier power due to the specialized sourcing requirements for medical-grade titanium and biocompatible polymers. Threat of substitutes remains low given the irreplaceable nature of rigid cranial fixation, whereas competitive rivalry is intense among established multinational firms vying for hospital formulary inclusion.
SWOT Analysis of the Cranial Fixation Sector
Key strengths include high biocompatibility standards and robust intellectual property portfolios held by market leaders. Weaknesses involve high device costs and complex sterilization requirements. Opportunities lie in pediatric-specific fixation systems, while threats include pricing pressures from healthcare payers and stringent international regulatory audits.
Value Chain Analysis from Raw Materials to End-Users
The value chain initiates with raw material procurement of medical-grade titanium alloys and resorbable polymers, progressing through precision CNC machining and cleanroom packaging. Finished goods transit via specialized medical freight to major distribution hubs, ultimately reaching surgical suites in hospitals and ambulatory surgical centers.
Investment Insights and High-Potential Areas
Our analysis highlights patient-specific cranial plates and radiolucent cranial clamps as high-potential investment zones. Venture capital and corporate development divisions should target medtech innovators developing advanced resorbable screws to capture high-margin segments driven by the aging adult and geriatric patient populations.
Conclusion and Strategic Key Takeaways
In summary, the Cranial Fixation And Stabilization Systems Market offers compelling growth avenues anchored by technological innovation and steady demographic tailwinds. Companies that successfully navigate regulatory frameworks while expanding their resorbable and patient-specific product portfolios will dominate the competitive landscape through 2033.
Research Methodology and Data Triangulation
Our baseline estimates are rigorously triangulated by combining primary stakeholder interviews with neurosurgeons and procurement directors, secondary trade registry data, and macroeconomic healthcare expenditure indicators. This multi-tiered verification process ensures high fidelity in market sizing and growth rate projections.
Scope of the Report and Coverage Parameters
This report covers global market dynamics for cranial fixation and stabilization systems from 2026 to 2033, analyzing product types, material compositions, age demographics, and end-user facilities. Geographic parameters encompass North America, Europe, Asia-Pacific, Latin America, and the Middle East & Africa, accounting for regulatory variances across jurisdictions.
Recent Corporate Developments and Strategic Industry Moves
Recent developments underscore a wave of strategic partnerships and product launches aimed at expanding digital neurosurgery ecosystems. Companies like Medartis AG and Jeil Medical Corporation have actively invested in regulatory clearances for novel low-profile titanium plates and advanced self-drilling cranial screws to enhance intraoperative efficiency.