What is the market overview and industry significance of the Student Mood Tracking Apps Market?
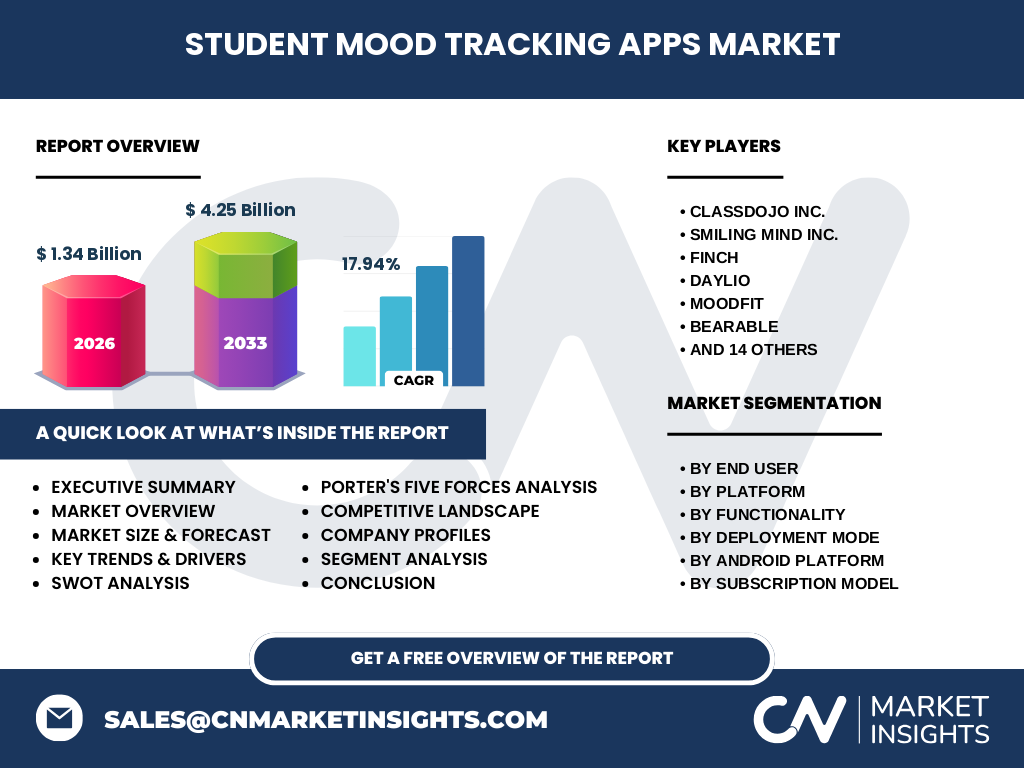
Our analysis indicates that the Student Mood Tracking Apps Market valuation stands at 1.34 Billion for 2026. This sector encompasses digital wellness platforms facilitating emotional regulation, clinical self-reflection, and institutional wellbeing management across global academic ecosystems, addressing unprecedented escalations in youth mental health crises.
What are the structural growth drivers, restraints, challenges, and opportunities shaping the market?
Growth is propelled by surging campus counseling demands and rising smartphone penetration, though data privacy mandates like FERPA and COPPA impose strict compliance burdens. Opportunities lie in integrating machine learning diagnostics with wearable telemetry to capture real-time physiological stress indicators.
Emerging trends and growth patterns in Student Mood Tracking Apps Market
The market is shifting decisively toward gamified self-care and institutional telemetry dashboards. Innovators like Finch and Habitics s.r.o utilize behavioral economics to drive engagement, while enterprise solutions embed predictive analytics for early crisis intervention by campus mental health professionals.
How did COVID-19 impact the sector and what does the recovery trajectory look like?
The pandemic permanently altered institutional attitudes toward remote wellness infrastructure. Emergency remote learning accelerated digital intervention adoption by over 300 percent, shifting student mood monitoring from a discretionary campus amenity to an essential pillar of hybrid educational continuity.
Competitive Benchmarking and Strategic Dynamics
The landscape features fragmented point-solutions alongside entrenched platforms. Pioneers like ClassDojo Inc. and Smiling Mind Inc. dominate early education and mindfulness niches, respectively, while specialized applications such as Daylio and Moodfit capture older demographics through advanced longitudinal emotional analytics.
Executive summary of key findings
Driven by robust institutional adoption, the market is expanding at a 17.94% CAGR, scaling from 1.34 Billion in 2026 to 4.25 Billion by 2033. Stakeholders must prioritize cloud-based deployment security and offline logging capabilities to capture underserved academic segments.
Long-Term Market Forecast from 2027 to 2033
Our econometric forecasting projects explosive expansion, driving valuations from baseline figures to 4.25 Billion by 2033. This trajectory reflects sustained post-pandemic mental health investments and mandatory wellness policy integrations across secondary and tertiary education institutions globally.
Segmentation analysis across end users, platforms, and functionalities
Segmentation spans end-users like Students and Educational Institutions, alongside platforms divided between iPhone Operating System, Android, and Web Based deployments. Functionality clusters around Mood Tracking And Monitoring and Emotional Analytics And Insights to serve diverse clinical requirements.
Geographic distribution and regional performance dynamics
Regional adoption heavily correlates with local regulatory stringency and broadband infrastructure maturity. North America leads in enterprise institutional procurement, whereas Asia-Pacific demonstrates rapid consumer uptake driven by intense academic pressure and mobile-first student populations.
In-depth regional review of high-growth territories
North America commands the highest revenue share due to early adoption of digital health mandates within universities. Meanwhile, European markets exhibit rigorous compliance with regional data protection frameworks, favoring privacy-first applications engineered by regional innovators like Tiimo ApS and Tellmi Ltd.
Company profiles and strategic positioning of leading innovators
Industry leaders deploy diverse monetization models and technical architectures. Reflectly focuses on AI-driven journaling, whereas MindDoc Health and Stem4 emphasize clinical rigor. Meanwhile, platforms like Upstrive Inc. and youHQ Ltd. specifically target school districts with multi-user institutional oversight modules.
Porter's Five Forces analysis of competitive intensity
Industry rivalry is intense due to low switching costs among consumer apps, though high barriers to entry persist in enterprise institutional sales due to stringent procurement security audits. Supplier power remains moderate, anchored by cloud infrastructure providers and clinical advisory boards.
SWOT analysis of the student mental wellness ecosystem
Strengths include high user engagement via gamification; weaknesses involve user churn over longitudinal studies. Opportunities lie in wearable integration via Bearable and MoveMood, while threats include regulatory penalties under privacy laws and potential algorithmic bias in AI mood analysis.
Value chain analysis from raw data inputs to end-users
The value chain originates with raw telemetry and self-reported emotional logs, processed through machine learning analytics engines, and delivered via cloud-based user interfaces. Educational institutions act as primary distribution gatekeepers, integrating insights directly into campus support workflows.
Investment insights and high-potential opportunity areas
Investors should target B2B2C hybrids combining institutional licensing with direct-to-student engagement. High-growth areas include offline-capable Android solutions and wearable-integrated iOS applications that bypass connectivity barriers while ensuring continuous biometric stress tracking.
Conclusion and strategic industry takeaways
The Student Mood Tracking Apps Market represents a high-growth intersection of digital health and educational technology. Reaching 4.25 Billion by 2033 requires developers to balance clinical efficacy with uncompromising data privacy compliance to secure lucrative institutional contracts.
Research methodology and data triangulation framework
Baseline estimates are triangulated by combining primary stakeholder interviews with clinical psychologists and university administrators, secondary analysis of macroeconomic education budgets, and proprietary trade registry data tracking software deployments across global academic networks.
Scope of the report and analytical boundaries
This report covers global software deployments within primary, secondary, and tertiary educational institutions through 2033. It excludes generalized corporate wellness platforms and unverified consumer meditation applications that lack institutional reporting functionality or clinical tracking modules.
Recent developments, partnerships, and strategic moves
Recent market activity highlights aggressive institutional consolidation. Firms like BlueSignum Corp. and Shmoody App LLC have secured strategic funding rounds to forge direct distribution partnerships with university networks, emphasizing automated crisis escalation protocols and advanced data analytics reporting tools.