What is the market overview and industry significance of Picture Labels For Toy Bins Market?
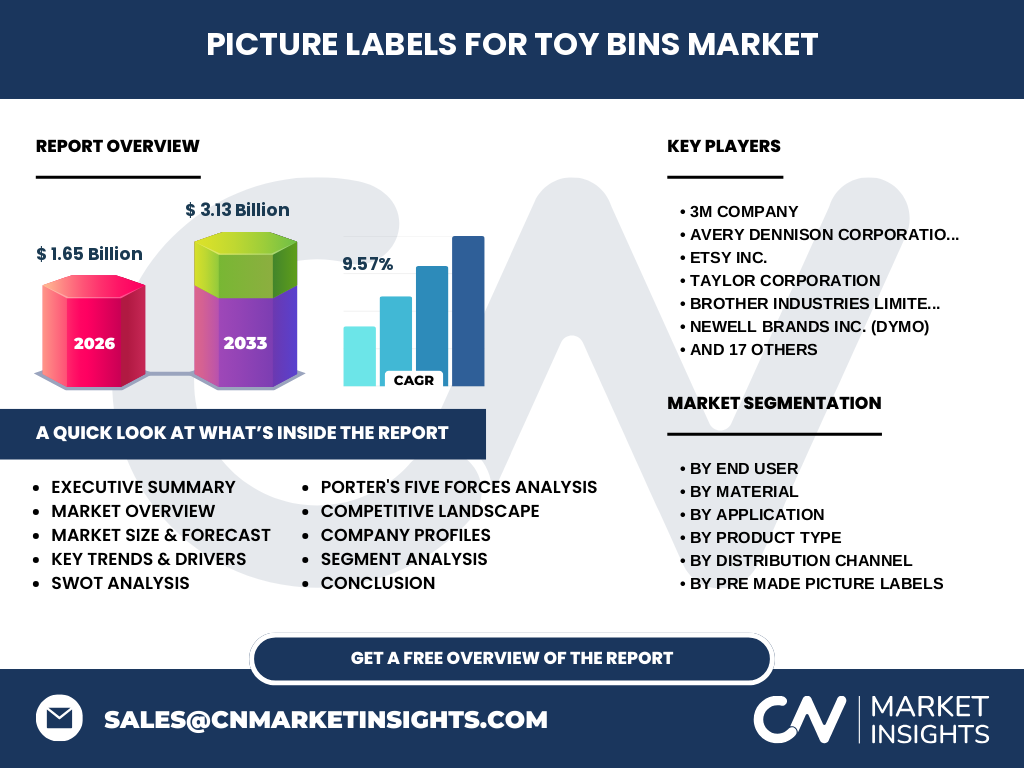
The Picture Labels For Toy Bins Market represents a niche yet rapidly expanding sector valued at 1.65 Billion in 2026. Our analysis indicates that rising consumer emphasis on structured home environments and early childhood cognitive development drives the demand for specialized identification markers, bridging material science with interior organization.
Structural Growth Drivers and Restraints Shaping Industry Dynamics
Growth is accelerated by parental investments in Montessori-aligned home organization and expanding preschool infrastructures. However, raw material price volatility in paper and synthetic polymers alongside stringent toy-safety regulations imposed by bodies like the CPSC act as notable restraints on profit margins for manufacturers.
Emerging Trends and Growth Patterns in Picture Labels For Toy Bins Market
A dominant trend is the shift toward interactive and eco-conscious labeling solutions. Parents and educators increasingly demand reusable vinyl labels and customized photo formats that foster cognitive growth, pushing brands like Cricut Inc. and StickerYou Inc. to innovate in printable craft formats.
How did the COVID-19 pandemic impact the market and shape the recovery trajectory?
The pandemic triggered an unprecedented surge in home nesting and remote learning, catapulting demand for home organization tools. Supply chain bottlenecks at major ports initially disrupted raw material flows, but post-COVID recovery has stabilized procurement, aligning with a robust market CAGR of 9.57%.
Competitive Benchmarking and Strategic Dynamics
The market features a fragmented yet highly competitive landscape. Industry giants like 3M Company and Avery Dennison Corporation leverage vast distribution networks, while direct-to-consumer innovators like Etsy Inc. and Mabel’s Labels Inc. (CCL Industries) capture share through hyper-personalized e-commerce offerings.
Executive Summary of Key Findings
Our comprehensive report reveals a projected market expansion reaching 3.13 Billion by 2033 from 1.65 Billion in 2026. This dynamic growth is underpinned by rising educational institution spending and digital commerce penetration, necessitating agile manufacturing and localized distribution strategies.
Market Forecast and Valuation Projections from 2027 to 2033
Driven by sustained consumer spending and institutional adoption, the market is projected to surge from 2027 through 2033 at a steady 9.57% CAGR. This trajectory will push total sector valuation to 3.13 Billion, rewarding players who optimize direct-to-consumer digital channels.
Segmentation Analysis of Material, Application, and Product Types
The market segments by End User (Residential, Commercial, Educational), Material (Paper, Plastic, Vinyl, Magnetic), and Product Type (Pre-Made, Customizable, DIY). Vinyl and magnetic variants lead durability segments, whereas pre-made illustrated labels dominate residential nurseries.
Geographic Distribution and Regional Performance Overview
Regional performance mirrors disposable income levels and early childhood education spending. North America leads consumption due to advanced retail distribution, while Asia-Pacific emerges as the fastest-growing region, propelled by expanding urban middle classes and proliferating preschool and daycare facilities.
In-Depth Regional Review of North America and International Markets
North America commands the largest market share, anchored by robust online retail ecosystems and high consumer expenditure on home aesthetics. Concurrently, European markets emphasize stringent eco-friendly standards, favoring biodegradable paper and non-toxic laminated adhesive solutions.
Strategic Positioning of Leading Companies
Market leaders deploy distinct strategies: Newell Brands Inc. (DYMO) and Brother Industries Limited dominate hardware-enabled labeling ecosystems, whereas specialized firms like Name Bubbles LLC and Stuck on You Pty Ltd capture loyal consumer segments via allergy-aware and durable school-grade identification products.
Porter's Five Forces Analysis of Competitive Intensity
Bargaining power of suppliers remains moderate due to diverse polymer sources, while the threat of substitutes is low given the unique utility of pictorial sorting tools. Competitive rivalry is fierce, driven by low switching costs in online retail marketplaces.
SWOT Analysis Highlighting Strategic Vulnerabilities and Wins
Key strengths lie in brand loyalty and extensive personalization capabilities. Weaknesses include vulnerability to synthetic raw material cost spikes. Opportunities abound in emerging educational deployments, while counterfeit products and digital-only organizational apps present lingering market threats.
Value Chain Analysis from Raw Material Sourcing to End-Users
The value chain initiates with chemical and paper pulp producers, passing through converting facilities where cutting-edge die-cutters and laminators operate. Finished goods flow through supermarkets, hypermarkets, and specialty online stores before reaching residential and educational end-users.
Investment Insights and High-Potential Growth Pockets
Investors should target direct-to-consumer platforms offering editable photo labels and magnetic custom solutions. High-margin opportunities reside in B2B contracts with daycare franchises seeking standardized, color-coded classroom storage labeling systems.
Conclusion and Strategic Takeaways for Industry Stakeholders
Capturing future upside in this 3.13 Billion market requires balancing automated e-commerce fulfillment with premium product customization. Companies prioritizing sustainable materials and seamless design software will outperform legacy commodity manufacturers.
Research Methodology and Baseline Estimation Triangulation
Our baseline estimates are rigorously triangulated by cross-referencing trade registry data from customs databases, primary stakeholder interviews with executives at Tinyme Pty Ltd and StickerYou Inc., and secondary macroeconomic indicators concerning global retail household expenditures.
Scope of the Report, Coverage Parameters, and Analytical Limitations
This report covers global revenue streams from 2026 to 2033 across residential, commercial, and educational end-users. Limitations include potential fluctuations in regional tariff policies and localized consumer spending shifts driven by macroeconomic inflationary pressures.
Recent Developments, Strategic Partnerships, and Product Innovations
Recent industry moves highlight aggressive digital expansion. Firms like Cricut Inc. and Silhouette America Inc. have rolled out advanced design software updates enabling instant home-print capabilities, while Mabel’s Labels Inc. expanded its institutional partnerships for school-supply sanitation compliance.