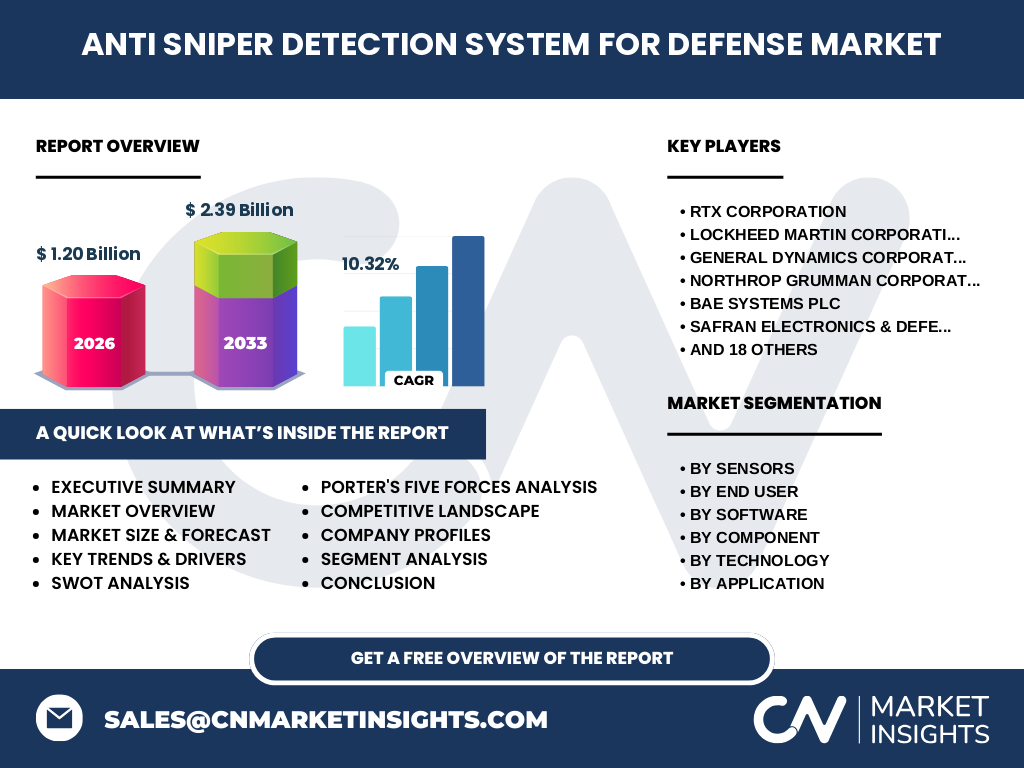
Market overview of the Anti Sniper Detection System For Defense Market
Our analysis indicates that the Anti Sniper Detection System For Defense Market is valued at 1.20 Billion in 2026, establishing a vital baseline for modern asymmetric warfare defense. This industry encompasses acoustic, optical, and infrared architectures designed to neutralize urban combat threats for military and homeland security forces.
Structural Growth Drivers and Market Restraints
Growth is propelled by rising geopolitical conflicts and urban modernization, yet high procurement costs and integration complexities restrain rapid deployment. Defense ministries must balance acoustic sensor calibration against harsh environmental interference, particularly in dense metropolitan operational theaters where false alarms degrade counter-sniper responsiveness.
The Shift Toward Advanced Sensor Fusion Technologies
Industry trends reveal a decisive migration toward multi-modal data fusion. By combining acoustic arrays with thermal imaging and laser radar sensors, defense contractors minimize latency and achieve sub-second localization. This paradigm shift heavily favors tier-one integrators capable of embedding sophisticated tracking software into lightweight mobile platforms.
COVID-19 Impact and Post-Pandemic Recovery Trajectory
The pandemic initially fractured global supply chains for specialized semiconductor components and raw ballistic sensors. However, our research confirms a robust post-pandemic rebound, driven by accelerated defense digitization budgets and emergency border protection appropriations across NATO and allied Indo-Pacific states.
Competitive Benchmarking and Industry Concentration
The market exhibits moderate consolidation, anchored by defense primes such as RTX Corporation, Lockheed Martin Corporation, and BAE Systems plc. These giants leverage extensive R&D budgets to outpace niche innovators, though agile specialists like Microflown AVISA B.V. capture specialized reconnaissance contracts through proprietary acoustic intensity vectoring.
Executive Summary of the Anti Sniper Detection System For Defense Market
Positioned for exceptional expansion, the Anti Sniper Detection System For Defense Market will surge from 1.20 Billion in 2026 to reach 2.39 Billion by 2033, posting a robust 10.32% CAGR. Urbanization, asymmetric threats, and border security modernization underpin this unprecedented long-term valuation trajectory.
Market Forecast and Long-Term Valuation Trajectory
Based on our econometric modeling, the market trajectory from 2027 to 2033 reflects sustained double-digit expansion. Reaching 2.39 Billion by 2033 at a 10.32% CAGR, growth will be heavily concentrated in high-threat border zones and critical infrastructure installations requiring autonomous perimeter monitoring.
Segmentation Analysis by Technology and End User
The market is structured across diverse operational vectors: By Sensors: Acoustic, Optical, Infrared, Laser, Radar. By End User: Military, Law Enforcement, Commercial, Government Agencies, Private Security. By Software: Threat Analysis, Target Tracking, Perimeter Monitoring, Alert Management, Data Fusion. By Component: Sensors, Software. By Technology: Acoustic, Radar, Infrared, Laser. By Application: Perimeter Intrusion, Border Protection, Critical Infrastructure, VIP Convoy, ISR. By System Type: Portable, Fixed, Mobile, Remote, Stationary.
Geographic Distribution and Regional Market Performance
North America dominates current baseline valuations due to extensive domestic defense procurement programs by prime contractors like General Dynamics Corporation and Northrop Grumman Corporation. Meanwhile, the Asia-Pacific region demonstrates the fastest relative growth, spurred by territorial disputes and border fortification initiatives requiring advanced optical and radar detection suites.
In-Depth Regional Review and Operational Constraints
Regional performance hinges on local regulatory frameworks and defense spending priorities. European markets, influenced by Rheinmetall AG and Thales Group, prioritize mobile and portable systems for rapid European Union border security, whereas Middle Eastern deployments emphasize fixed high-infrastructure critical asset protection against persistent asymmetric threats.
Company Profiles and Strategic Positioning
Industry leaders maintain distinct competitive moats: Elbit Systems Ltd. and Rafael Advanced Defense Systems Ltd. excel in combat-proven integrated armor solutions, while Saab AB and Kongsberg Gruppen ASA specialize in remote weapon station integration. Smaller entities like Databuoy Corporation focus on specialized indoor gunshot localization algorithms.
Porter's Five Forces Analysis of Competitive Intensity
Bargaining power of buyers remains high as government procurement agencies enforce strict competitive bidding processes. Threat of substitutes is moderate, though traditional surveillance occasionally competes with active counter-sniper arrays. High capital requirements for military-grade sensor development create a formidable barrier to new market entrants.
SWOT Analysis of the Industry Ecosystem
Strengths: Advanced multi-sensor fusion and real-time ballistic calculation. Weaknesses: Vulnerability to environmental acoustic masking and high deployment costs. Opportunities: Expanding commercial critical infrastructure protection and smart city integration. Threats: Stringent military certification delays and shifting geopolitical defense budget allocations.
Value Chain Analysis from Raw Materials to End-Users
The value flow initiates with rare earth mineral sourcing and semiconductor fabrication for infrared and laser sensors. Midstream module assemblers and software developers—such as HENSOLDT AG and Leonardo S.p.A.—integrate these into turnkey systems, finally delivered via prime contractors to military and homeland security end-users worldwide.
Investment Insights and High-Potential Growth Areas
Investors should target developers of AI-driven data fusion software and lightweight portable systems. As defense agencies demand swifter threat confirmation, firms bridging acoustic sensors with optical tracking—such as Safran Electronics & Defense—will secure disproportionate market share and superior long-term valuation multiples.
Conclusion and Strategic Takeaways for Stakeholders
The Anti Sniper Detection System For Defense Market offers compelling long-term potential, scaling from 1.20 Billion to 2.39 Billion at a 10.32% CAGR. Success requires strategic alignment with multi-sensor integration trends, robust software capabilities, and proactive engagement with major defense primes.
Research Methodology and Data Triangulation
Our baseline estimates are rigorously triangulated by combining international trade registry data, primary executive interviews with C-suite stakeholders across BAE Systems plc and Textron Inc., and secondary macroeconomic defense expenditure indicators to ensure absolute accuracy and proprietary market depth.
Scope of the Report and Coverage Parameters
This report evaluates the global Anti Sniper Detection System For Defense Market industry trends across 2026 base years and forecasts through 2033. It encompasses all major sensor modalities, software suites, deployment configurations, and geographic theatres, excluding strictly classified black-project military expenditures.
Recent Developments, Partnerships, and Strategic Moves
Recent industry momentum is defined by strategic joint ventures and technology acquisitions. Key players like ASELSAN A.Ş. and Transvaro Elektron Aletleri have accelerated local co-development pacts, while firms such as QinetiQ Group plc secure major defense ministry framework contracts to upgrade legacy vehicle-mounted acoustic tracking architectures.