Market overview of the Vegan Wines Market
Our analysis indicates that the Vegan Wines Market encompasses vinicultural production eliminating animal-derived fining agents like gelatin, casein, and Isinglass. Valued at 2.79 Billion in 2026, this sector carries immense significance as regulatory bodies such as the EU and TTB enforce stringent transparency, compelling wineries to adopt bentonite clay and pea protein alternatives.
Structural Growth Drivers and Market Restraints
The Vegan Wines Market industry trends highlight plant-based lifestyle adoption as a primary catalyst. Growth is propelled by eco-conscious consumers demanding certified organic raw materials. However, supply chain constraints involving specialized bottling lines and strict cross-contamination protocols in multi-label facilities act as notable operational restraints.
Emerging Trends in the Vegan Wines Market
A major shift toward sustainable packaging is reshaping the landscape, with producers favoring lightweight bottles and aluminum cans. Innovations in non-alcoholic and orange wine variants by pioneers like Sula Vineyards Limited and Gemtree Wines capture health-focused demographics seeking alternative sensory profiles.
COVID-19 Impact Analysis and Recovery Trajectory
The pandemic severely disrupted the HoReCa distribution network, forcing agile pivots toward online retail and direct-to-consumer models. Producers like Naked Wines plc capitalized on this shift, accelerating digital adoption and establishing resilient recovery trajectories that continue to drive off-premise sales post-pandemic.
Competitive Benchmarking and Market Concentration
The Vegan Wines Market analysis reveals a moderately fragmented yet consolidating landscape. Industry giants like E. & J. Gallo Winery, Constellation Brands Inc., and Pernod Ricard leverage vast distribution networks to acquire or scale dedicated organic portfolios, competing directly with agile boutique producers.
Executive Summary of Vegan Wines Market Dynamics
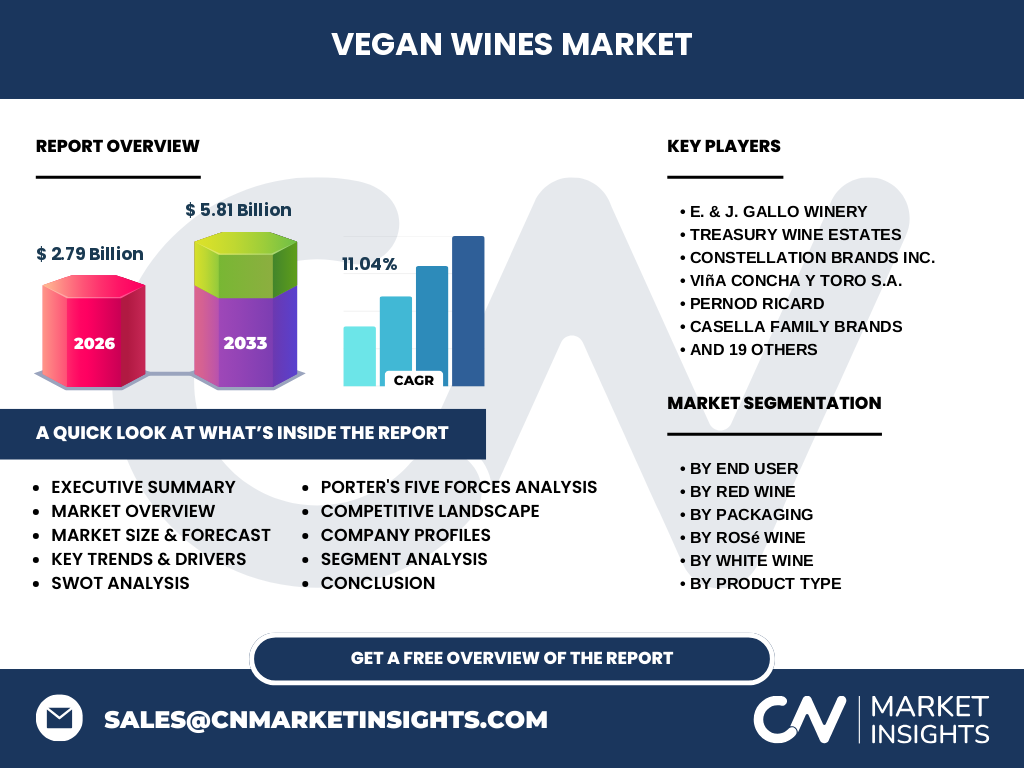
Synthesizing core findings, the Vegan Wines Market size is poised for explosive expansion, scaling from 2.79 Billion in 2026 to 5.81 Billion by 2033 at a robust 11.04% CAGR. Strategic investments in certified organic viticulture and e-commerce infrastructure represent the definitive pathway to capturing high-margin segments.
Long-Term Market Forecast from 2027 to 2033
Our proprietary models project consistent upward momentum, driving the Vegan Wines Market market size from 2.79 Billion in 2026 to reach 5.81 Billion by 2033. This trajectory represents a steady 11.04% CAGR, fueled by expanding retail shelf space and surging global demand for sustainably crafted varietals.
Segmentation Analysis across Key Product and End-User Categories
The Vegan Wines Market industry trends are heavily influenced by granular segmentation: - End User: Households, Hotel Restaurant And Catering, Other End Users - Red Wine: Still, Dry, Semi Sweet, Sweet, Fortified, Organic - Packaging: Bottles, Cans, Boxes, Other - Rosé & White Wine: Diverse dry, sweet, sparkling, and aromatic variants - Product Type: Red, White, Rosé, Sparkling, and Other (Fruit, Dessert, Fortified, Low/Non-Alcoholic, Orange) - Distribution: Online, Supermarkets, Specialty Stores
Regional Market Analysis and Geographic Performance
Geographic performance varies significantly, with Western Europe leading due to stringent labeling laws and deep-rooted organic viticulture traditions. Meanwhile, North America demonstrates the fastest adoption rates, driven by urban demographic shifts toward plant-based diets and premiumization in major metropolitan centers.
In-Depth Regional Review and Logistical Realities
Logistical efficiency dictates regional success; European producers utilize proximity to major maritime ports like Rotterdam, while Australian innovators like Yellow Tail (Casella Family Brands) leverage Pacific trade routes. Regional constraints involve adhering to unique organic certifications demanded by local import authorities.
Company Profiles and Strategic Positioning
Industry leaders maintain distinct competitive moats. Viña Concha y Toro S.A. and Familia Torres champion large-scale sustainability, while dedicated specialists like Frey Vineyards and Bonterra Vineyards capture loyalty through uncompromising no-sulfite-added, biodynamic, and vegan-certified production standards.
Porter's Five Forces Analysis of the Sector
Competitive rivalry is intense as legacy winemakers convert traditional lines to vegan standards. Supplier power remains moderate, governed by organic yeast and nutrient availability, while buyer power is high due to proliferating private-label supermarket offerings and transparent digital review platforms.
SWOT Analysis of the Vegan Wines Industry
Strengths lie in booming health-conscious consumer alignment; weaknesses involve higher certification and auditing costs. Opportunities abound in emerging Asian-Pacific markets, while threats stem from potential greenwashing regulatory crackdowns and climate change impacts on traditional grape-growing regions.
Value Chain Analysis from Raw Materials to End-Users
The value flow begins with sustainably farmed grapes and plant-based fining agents. It moves through temperature-controlled vinification at facilities managed by firms like AdVini S.A. or Italian Wine Brands S.p.A., passing through specialized logistics before reaching consumers via supermarkets and e-commerce.
Investment Insights and High-Potential Areas
High-potential capital allocation targets non-alcoholic and organic sparkling segments, which exhibit exceptional growth velocity. Investors should prioritize wineries partnering with digital-first distributors like Naked Wines plc to maximize customer acquisition efficiency in unpenetrated suburban demographics.
Conclusion and Strategic Key Takeaways
The Vegan Wines Market offers compelling growth, backed by a projected 11.04% CAGR pushing valuations to 5.81 Billion by 2033. Wineries that seamlessly integrate absolute supply chain transparency with innovative packaging will dominate the next era of global wine consumption.
Research Methodology and Data Triangulation
Our baseline estimates are rigorously triangulated by synthesizing global trade registry data, primary qualitative interviews with master winemakers from entities like Weingut Gunderloch and Thumbprint Cellars, and secondary macroeconomic indicators regarding agricultural yields and consumer beverage expenditure.
Scope of the Report and Coverage Parameters
This report evaluates the global Vegan Wines Market across all specified product categories, distribution channels, and regional blocks from 2026 through 2033. Limitations include localized excise tax volatility and unrecorded direct-to-consumer farmgate sales within fragmented developing agricultural zones.
Recent Developments and Corporate Strategic Moves
Recent market dynamism is marked by targeted M&A activity and portfolio expansions. Key players such as Treasury Wine Estates and The Wine Group LLC have recently introduced carbon-neutral, vegan-certified tiers to meet tightening corporate ESG mandates and capture conscious millennial buyers.