Market overview of the Wide-Field Optical Coherence Tomography (OCT) Imaging Market
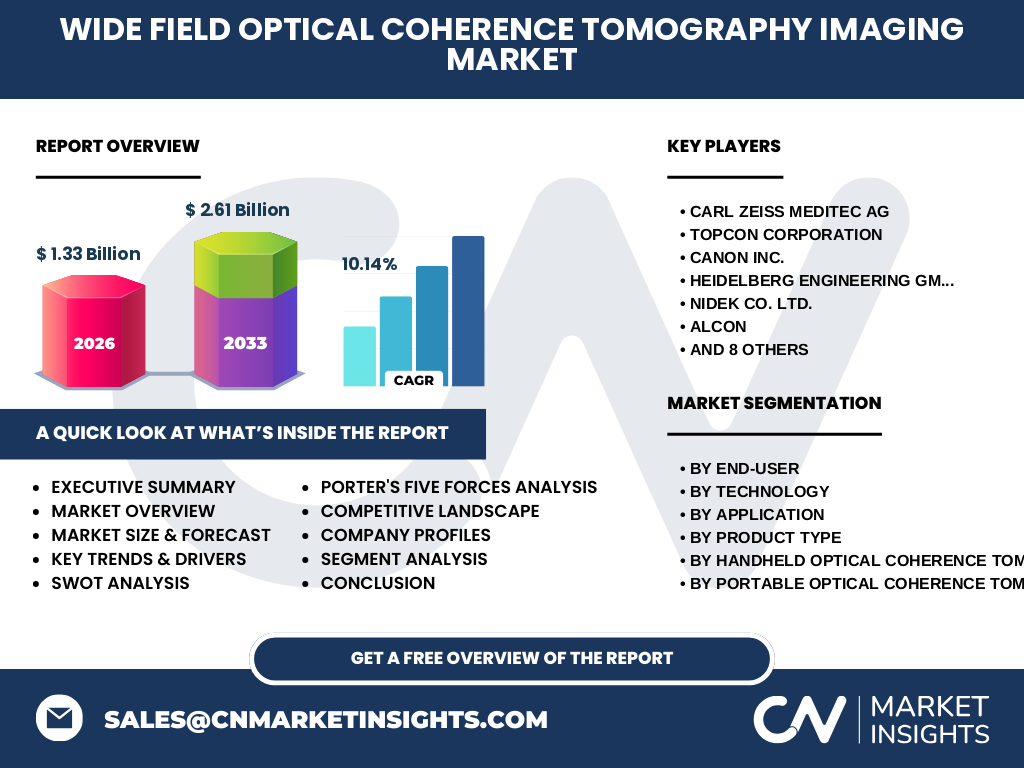
Our analysis indicates that the Wide-Field Optical Coherence Tomography (OCT) Imaging Market represents a transformative frontier in diagnostic medicine, providing unprecedented peripheral retinal visualization. Valued at 1.33 Billion in 2026, this sector is critical for early detection of pathologies like diabetic retinopathy and glaucoma, bridging vital gaps in modern clinical workflows.
Structural Growth Drivers and Market Restraints
The Wide-Field Optical Coherence Tomography (OCT) Imaging Market industry trends reveal robust momentum fueled by rising diabetic populations and technological shifts toward non-invasive diagnostics. However, stringent FDA and CE-MDR regulatory hurdles and prohibitive capital expenditure requirements for high-resolution units continue to restrain rapid adoption in smaller community healthcare facilities.
Emerging trends and growth patterns in the sector
A defining shift in the Wide-Field Optical Coherence Tomography (OCT) Imaging Market analysis is the integration of proprietary artificial intelligence algorithms, spearheaded by innovators like Altris AI. These advancements automate pathological screening, radically shortening scan review times and empowering clinicians in high-volume specialty clinics.
COVID-19 impact analysis and pandemic recovery
The COVID-19 pandemic severely disrupted supply chains for critical optical components and delayed elective ophthalmic screenings globally. Nevertheless, our research shows a vigorous post-pandemic rebound, as telehealth mandates and stringent infection control protocols accelerated investments in portable and point-of-care diagnostic devices.
Competitive Benchmarking and Market Concentration
Industry leadership within the Wide-Field Optical Coherence Tomography (OCT) Imaging Market is consolidated among established med-tech titans such as Carl Zeiss Meditec AG, Topcon Corporation, and Heidelberg Engineering GmbH. These enterprises leverage expansive global distribution networks and aggressive R&D spending to maintain dominant market share against agile challengers.
Executive summary of key findings
Our comprehensive executive synthesis highlights a projected market expansion reaching 2.61 Billion by 2033, growing at a robust 10.14% CAGR starting in 2027. This acceleration underscores an escalating clinical demand for wider scanning angles, multi-modal integration, and AI-driven diagnostic precision across global healthcare systems.
Market forecast from 2027 to 2033
Driven by compounding technological adoption and aging demographics, the Wide-Field Optical Coherence Tomography (OCT) Imaging Market size will scale from 1.33 Billion in 2026 to 2.61 Billion by 2033. This expansion is sustained by continuous replacement cycles in tier-one hospital networks and surging adoption in emerging economies.
Segmentation analysis by technology, application, and end-user
The market architecture divides across core vectors: By End-User (Hospitals, Specialty Clinics, Ambulatory Surgical Centers, Research Institutes); By Technology (Spectral Domain, Swept Source, Time Domain OCT); By Application (Ophthalmology, Cardiology, Oncology, Dermatology); and By Product Type, encompassing advanced tabletop, handheld, and portable configurations.
Geographic distribution and regional market performance
Geographic performance in the Wide-Field Optical Coherence Tomography (OCT) Imaging Market reflects disparities in healthcare reimbursement models. North America maintains revenue dominance due to high diagnostic reimbursement rates, while Asia-Pacific represents the fastest-growing frontier, propelled by expanding healthcare infrastructure in China and Japan.
In-depth regional review of high-growth territories
North America and Western Europe remain primary revenue engines due to early clinical adoption of swept-source modalities and dense concentrations of specialized eye care facilities. Concurrently, APAC economies show accelerated uptake, driven by local manufacturing initiatives from firms like Weiren Medical Technology and MOPTIM Imaging Technique Co. Ltd.
Company profiles and strategic positioning of leading innovators
Market participants deploy distinct competitive plays: Canon Inc. and NIDEK CO. LTD. focus on ergonomic tabletop multi-modal devices, whereas Thorlabs Inc. supplies advanced optical components to research institutes. Meanwhile, specialized players like Notal Vision target remote patient monitoring, reshaping post-operative care paradigms.
Porter's Five Forces analysis
The Porter's Five Forces assessment reveals moderate-to-high competitive rivalry among established giants, coupled with substantial barriers to entry stemming from intricate patent landscapes in laser optics. Supplier power remains moderate regarding specialized silicon sensors, whereas buyer bargaining power is mitigated by the clinical necessity for gold-standard diagnostic precision.
SWOT analysis of the industry ecosystem
Key strengths include high diagnostic accuracy and expanding AI software integrations. Weaknesses center on high device acquisition costs. Opportunities abound in rural telehealth deployment via portable units, while threats involve rigorous regulatory compliance delays enforced by bodies like the FDA and EMA.
Value chain analysis from raw materials to end-users
The value chain originates with precision optical glass, semiconductor laser diodes, and advanced sensors. Tier-1 manufacturers assemble these components into diagnostic units, shipping via specialized logistics hubs to end-users like hospitals, ambulatory surgical centers, and research institutes, ensuring strict quality control.
Investment insights and high-potential areas
Strategic capital deployment should prioritize battery-operated and wireless-enabled handheld OCT devices. These segments address underserved decentralized care settings and remote screening initiatives, offering high-margin growth opportunities for venture capital and strategic acquirers in the med-tech space.
Conclusion and strategic takeaways
The Wide-Field Optical Coherence Tomography (OCT) Imaging Market presents compelling long-term prospects. Reaching 2.61 Billion by 2033, success in this landscape requires sustained R&D investment in swept-source technology, strategic AI partnerships, and navigation of localized regulatory frameworks to capture emerging regional demand.
Research methodology and data triangulation
Baseline estimates are triangulated using a rigorous mix of secondary macroeconomic indicators, trade registry data from major ports of entry, and primary stakeholder interviews with key opinion leaders, chief medical officers, and procurement heads across global hospital networks.
Scope of the report and coverage parameters
This report encompasses a comprehensive evaluation of the Wide-Field Optical Coherence Tomography (OCT) Imaging Market industry trends, covering global revenue streams from 2026 through 2033. It excludes low-resolution standard OCT systems, focusing exclusively on wide-field innovations across all specified technology and end-user verticals.
Recent developments, partnerships, and product launches
Recent industry momentum highlights aggressive product diversification. Collaborations between hardware leaders like Heidelberg Engineering GmbH and software developers such as Altris AI underscore a broader industry race toward integrated, automated diagnostic suites that streamline clinical workflows and improve patient outcomes.