What is the market overview and definition of the Counter-Drone And Anti-Unmanned Aerial System (UAS) Technology Market?
The Counter-Drone And Anti-Unmanned Aerial System (UAS) Technology Market encompasses specialized hardware, software, and services engineered to detect, track, identify, and mitigate unauthorized drones. Our analysis indicates that as low-altitude airspace congestion accelerates, securing critical infrastructure from asymmetric airborne threats has become a paramount defense priority.
Structural Growth Drivers and Restraints
Key market drivers include the rapid proliferation of commercial drones and geopolitical conflicts highlighting asymmetric aerial threats, pushing the Counter-Drone And Anti-Unmanned Aerial System (UAS) Technology Market industry trends toward advanced detection. Conversely, strict regulatory frameworks governing radio frequency spectrum allocation and kinetic interference in civilian airspace act as notable market restraints.
Emerging trends and growth patterns in the Counter-Drone And Anti-Unmanned Aerial System (UAS) Technology Market
The shift toward artificial intelligence-driven threat assessment and directed energy weapons is reshaping the landscape. Based on our research, defense primes are heavily integrating edge computing into Command And Control Software to process multi-sensor inputs from radar and electro-optical cameras in real time, drastically reducing human response latency.
How did COVID-19 impact the Counter-Drone And Anti-Unmanned Aerial System (UAS) Technology Market?
The pandemic temporarily disrupted global supply chains for specialized semiconductor components and raw materials like gallium nitride. However, our evaluation shows that accelerated remote border monitoring needs during lockdowns actually catalyzed long-term funding, positioning the Counter-Drone And Anti-Unmanned Aerial System (UAS) Technology Market for robust post-pandemic recovery.
Competitive Benchmarking and Strategic Dynamics
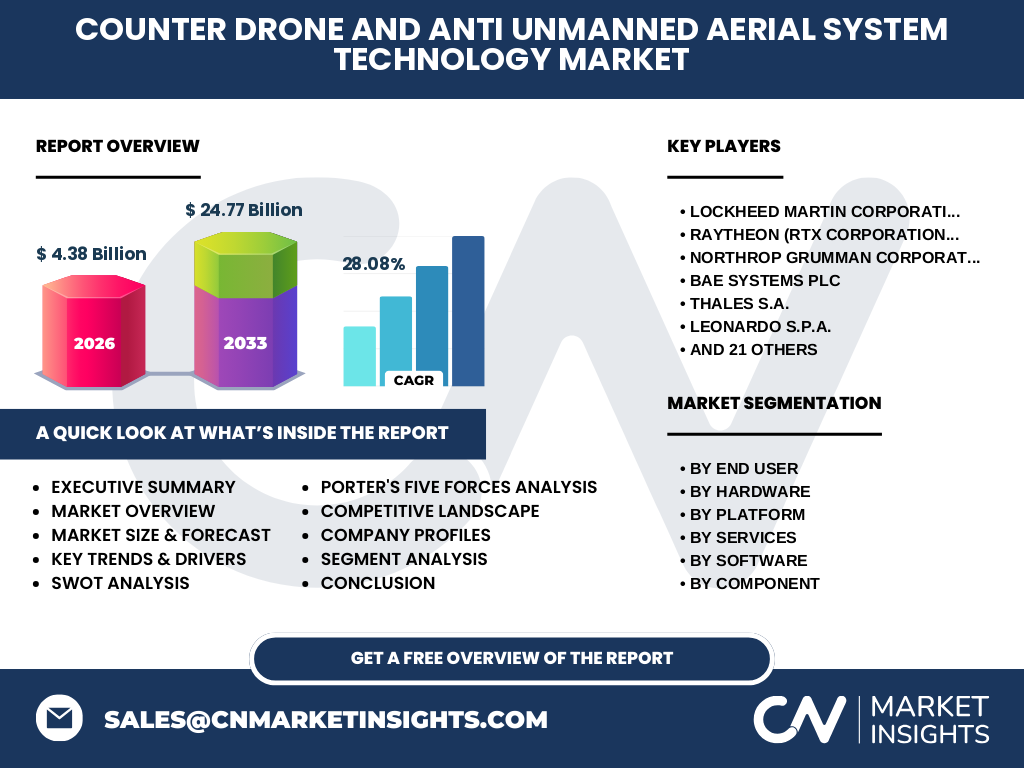
The competitive landscape features a blend of prime defense contractors and agile technology innovators. Enterprises like Lockheed Martin Corporation and Raytheon compete alongside specialized firms such as DroneShield Ltd. and D-Fend Solutions Ltd., driving fierce M&A activity to capture comprehensive end-to-end capabilities across hardware, software, and maintenance services.
Executive Summary of the Counter-Drone And Anti-Unmanned Aerial System (UAS) Technology Market
Our comprehensive findings project the Counter-Drone And Anti-Unmanned Aerial System (UAS) Technology Market market size to surge from 4.38 Billion in 2026 to 24.77 Billion by 2033. This remarkable expansion represents a compound annual growth rate (CAGR) of 28.08%, driven by escalating security requirements across military and commercial sectors.
Market forecast from 2027 to 2033
The data suggests exponential growth trajectory, vaulting from the 2026 baseline of 4.38 Billion to reach 24.77 Billion by 2033 at a 28.08% CAGR. This upward curve reflects surging procurement budgets by homeland security agencies and critical infrastructure operators seeking multi-layered protection against sophisticated swarm attacks.
Segmentation analysis across hardware, software, services, and platforms
The market is categorized into hardware (Radar Systems, RF Detection, Electro Optical And Infrared Cameras, Acoustic Sensors, Jamming Devices), software (Command And Control, AI Detection), services, platforms (Ground-Based, Airborne, Vehicle-Mounted, Handheld), and operating ranges. Each segment plays a vital role in delivering layered defense-in-depth solutions tailored for specific operational environments.
Geographic distribution and regional market analysis
Regional performance varies significantly based on defense spending allocations and regulatory openness to counter-UAS deployment. North America leads the adoption curve due to stringent homeland security mandates, while Europe demonstrates rapid procurement growth driven by localized geopolitical tensions and critical infrastructure vulnerability assessments.
In-depth regional review of key markets
Our analysis reveals that the Asia-Pacific region is experiencing the fastest growth in the Counter-Drone And Anti-Unmanned Aerial System (UAS) Technology Market analysis, fueled by escalating defense budgets in nations like India and regional maritime disputes. Meanwhile, the Middle East remains a primary early adopter of combat-proven kinetic and directed energy systems.
Company Profiles and Strategic Positioning
Industry leaders occupy distinct niches: RTX Corporation and Northrop Grumman focus on large-scale integrated air defense architectures, while innovators like Anduril Industries Inc. and Epirus Inc. specialize in software-defined autonomy and high-power microwave effectors. This dichotomy forces traditional primes to acquire agile startups to maintain technological parity.
Porter's Five Forces Analysis
Supplier power remains moderate due to specialized semiconductor dependencies, whereas buyer power is high among sovereign defense agencies demanding bespoke customization. The threat of substitution is low given the unique physical nature of aerial threats, but competitive rivalry is intense as firms race to commercialize artificial intelligence detection software.
SWOT Analysis of the Industry
Strengths include highly sophisticated multi-sensor fusion capabilities, while weaknesses involve high procurement costs and complex regulatory approval hurdles. Opportunities abound in commercial venue protection and airport airspace security, balanced against threats from rapidly evolving open-source drone evasion techniques.
Value Chain Analysis from Raw Materials to End-Users
The value chain originates with rare earth minerals and semiconductor fabricators supplying specialized radar components. These feed into hardware manufacturers and software developers who collaborate with system integrators before final deployment by end-users across military defense, critical infrastructure, and commercial events.
Investment Insights and High-Potential Areas
Investors should target early-stage developers specializing in artificial intelligence-based detection software and directed energy systems. These sub-segments offer superior margin potential and are positioned to capture outsized market share as defense procurement shifts toward cost-effective, non-kinetic mitigation technologies.
Conclusion and Key Takeaways
The data underscores a transforming security paradigm where traditional defense frameworks prove inadequate against low-altitude drone threats. With a projected 28.08% CAGR reaching 24.77 Billion by 2033, stakeholders must prioritize software adaptability and multi-sensor integration to secure long-term competitive advantage.
Research methodology for baseline estimates
Our baseline estimates are rigorously triangulated by combining trade registry data, primary stakeholder interviews with chief technology officers, and secondary macroeconomic indicators. This multi-tiered approach ensures high fidelity in market sizing and eliminates anomalies inherent in single-source forecasting models.
Scope of the report and coverage parameters
This report evaluates the global Counter-Drone And Anti-Unmanned Aerial System (UAS) Technology Market across specified hardware, software, service, platform, and end-user verticals from 2026 through 2033. Limitations include restricted access to classified military black-budget allocations in select sovereign states.
Recent developments, partnerships, and strategic moves
Recent market activities feature extensive cross-border partnerships between defense primes and pure-play anti-drone specialists. Companies are aggressively launching software upgrades focused on drone swarm defeat mechanisms and securing multi-million dollar contracts with international civil aviation authorities and border patrol agencies.