What is the scope and industry significance of the Diamond Honing Stone Market?
Our analysis indicates that the Diamond Honing Stone Market encompasses specialized superabrasive tooling engineered for ultra-precise bore finishing and tight tolerance machining. Valued at $0.50 billion in 2026, this sector is indispensable for high-integrity manufacturing, relying on synthetic and natural diamond matrices to achieve nanometer-scale surface roughness across critical industrial components.
What are the primary market drivers, restraints, challenges, and opportunities shaping the Diamond Honing Stone Market?
Growth is propelled by rigorous tighter automotive emission standards and aerospace lightweighting demands requiring superior cylinder bore geometries. However, high raw material costs for synthetic diamond grit and complex supply chain bottlenecks for metal bonds restrain rapid margin expansion. Significant opportunities lie in developing eco-friendly hybrid bonding agents to reduce thermal degradation during aggressive stock removal.
The Shift Toward Advanced Precision Superabrasives
Industrial end-users are rapidly migrating away from conventional aluminum oxide stones toward engineered diamond solutions to handle advanced alloys like Inconel and titanium. This trend favors innovators such as Sunnen Products and Gehring Technologies GmbH And Co. KG, whose technologically advanced honing heads demand ultra-consistent electroplated and resin bond stones to prevent thermal distortion.
How did COVID-19 impact the Diamond Honing Stone Market and shape its subsequent recovery trajectory?
The pandemic caused severe supply disruptions in raw diamond procurement and forced temporary shutdowns across major automotive and machinery manufacturing plants globally. Post-pandemic recovery has been robust, driven by automated factory re-tooling and pent-up demand for high-precision dimensional correction tools from industrial hubs in East Asia and Western Europe.
Competitive Benchmarking and Market Concentration in Superabrasives
The market features a consolidated core of global powerhouses balanced by agile regional specialists. Industry leaders like Saint-Gobain and Asahi Diamond Industrial Co Ltd. leverage massive R&D budgets for proprietary bond matrices, while regional competitors such as Henan Huanghe Whirlwind Co Ltd. compete effectively on large-scale synthetic diamond grit production and cost efficiencies.
Executive Summary of the Diamond Honing Stone Market Industry Trends
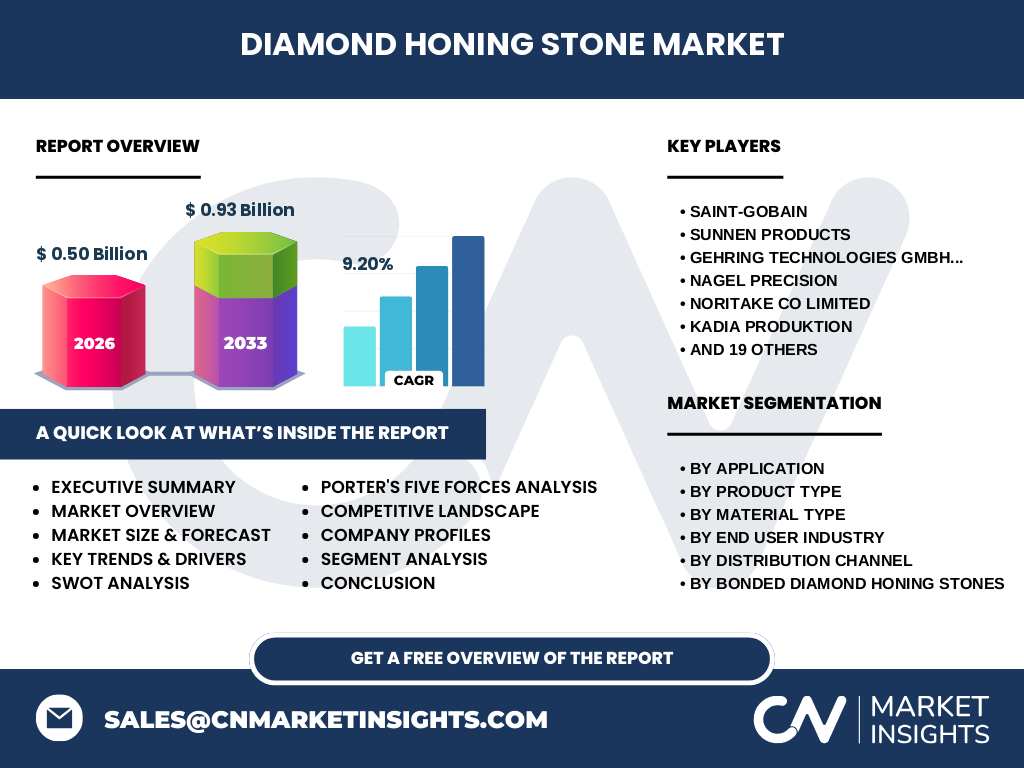
Our comprehensive assessment highlights that the Diamond Honing Stone Market will expand from $0.50 billion in 2026 to $0.93 billion by 2033, driven by a robust 9.20% CAGR. Strategic M&A activity and proprietary bond developments—such as vitrified and polyimide resin formulations—remain vital for capturing high-margin aerospace and automotive contracts.
Projected Market Trajectory and Growth Forecast from 2027 to 2033
Based on our econometric modeling, the market is poised for accelerated expansion, scaling from its 2026 baseline to reach $0.93 billion by 2033 at a steady 9.20% CAGR. This growth is underpinned by escalating requirements for surface finishing and deburring operations within electrified powertrain manufacturing and hydraulic systems.
Segmentation Analysis of Product Types, Materials, and Applications
The market segments by product into bonded, resin bond, metal bond, and electroplated diamond honing stones. Material types span synthetic and natural diamond bases, while applications range from surface finishing and precision honing to deburring operations and dimensional correction. End-users include automotive, aerospace, machinery manufacturing, tooling, and metalworking industries utilizing direct sales, industrial distributors, and online platforms.
Geographic Distribution and Regional Performance Dynamics
Regional performance varies significantly, with the Asia-Pacific region leading consumption due to massive automotive manufacturing output in China, Japan, and India. North America and Europe follow closely, driven by stringent aerospace standards and advanced machining facilities requiring specialized nickel and bronze bond stones supplied by regional leaders like Engis Corporation.
In-Depth Regional Review of Manufacturing Hubs and Demand Centers
In North America, demand is heavily tied to aerospace overhaul facilities and defense contractors requiring exact dimensional tolerances. Meanwhile, the European market focuses on high-end automotive tier-1 suppliers in Germany and Italy, where companies like KADIA Produktion and Nagel Precision integrate specialized honing stones into automated CNC production cells.
Strategic Positioning of Leading Companies in the Global Landscape
Market participants deploy distinct competitive strategies; for instance, Noritake Co Limited and Kinik Company Limited focus on advanced vitrified and ceramic bond technologies. Concurrently, specialized players like Abrasive Technology Inc. and DK Holdings Limited emphasize custom single-layer and multi-layer electroplated stones tailored for niche medical device and micro-machining applications.
Porter's Five Forces Analysis of Competitive Pressures
Bargaining power of suppliers is moderately high due to the specialized nature of high-grade synthetic diamond grit. Threat of substitutes remains low because conventional abrasives fail to meet the extreme wear resistance required in modern precision honing, though competitive rivalry is intense among established global superabrasive manufacturers.
SWOT Analysis Highlighting Strategic Strengths and Market Threats
Key strengths include exceptional hardness and long operational lifespans of diamond matrices. Weaknesses involve high initial capital expenditures for specialized tooling. Opportunities emerge from EV transmission gear finishing, while threats include macroeconomic volatility impacting heavy industrial machinery demand and fluctuating raw material tariffs.
Value Chain Analysis from Raw Material Sourcing to End-User Application
The value chain originates with chemical vapor deposition (CVD) and high-pressure high-temperature (HPHT) synthetic diamond synthesis. Mid-stream processes involve precision bonding, sintering, and electroplating by firms such as ILJIN Diamond Co Ltd. and More Super Hard Products Co Ltd., culminating in distribution to tier-1 automotive and aerospace machining floors.
Strategic Investment Insights and High-Potential Growth Areas
Investors should target manufacturers specializing in hybrid and polyimide resin bond diamond stones, as these materials reduce thermal stress during high-speed machining. Partnerships with regional machining innovators in emerging economies offer significant upside for capturing market share in precision tooling and deburring operations.
Conclusion and Strategic Takeaways for Industry Stakeholders
The Diamond Honing Stone Market represents a highly lucrative, technology-driven niche scaling toward $0.93 billion by 2033. Success requires continuous R&D investment in proprietary bond matrices and close alignment with automotive and aerospace manufacturers transitioning to next-generation precision components.
Research Methodology for Baseline Estimation and Market Triangulation
Our research methodology combines rigorous bottom-up capacity assessments with top-down macroeconomic modeling. Baseline estimates for the $0.50 billion 2026 market size were triangulated through extensive primary stakeholder interviews with chief engineers at companies like Wendt India/GmbH and Zhengzhou Boson Abrasives Co Ltd., cross-referenced against global trade registries and industrial manufacturing indices.
Scope of the Report and Analytical Parameters
This report covers global revenue estimations and volumetric consumption trends for the Diamond Honing Stone Market from 2027 through 2033. Limitations include restricted primary data transparency in certain localized markets, which were mitigated through econometric proxy indicators and expert panel consensus.
Recent Developments, Strategic Partnerships, and Product Launches
Recent industry momentum features key players expanding production capacities for eco-friendly ceramic bond stones. Notable strategic moves include collaborative R&D agreements between tooling specialists and universities to optimize diamond grit retention, alongside localized facility expansions by firms like Solar Diamond Tools India Private Limited and Varun Udyog Tools And Dies Private Limited to serve rising regional demand.