What is the scope and industry significance of the Companion Diagnostics For Targeted Therapies Market?
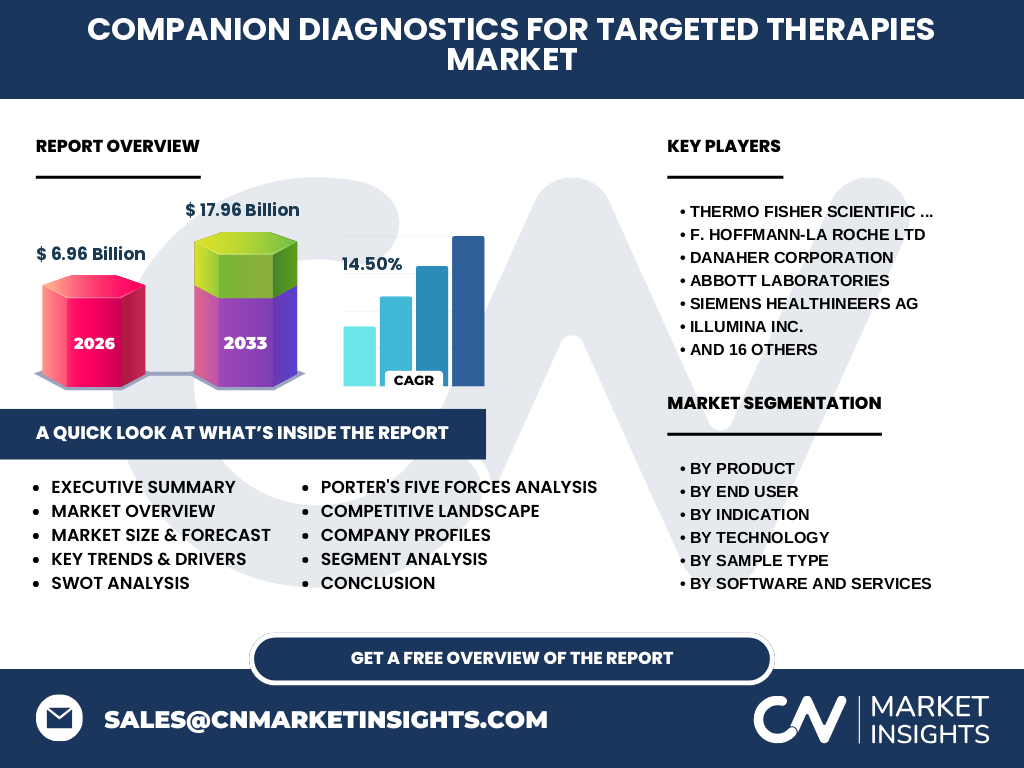
The Companion Diagnostics For Targeted Therapies Market reaches a valuation of 6.96 Billion in 2026, establishing itself as a cornerstone of precision oncology and customized medicine. Our analysis indicates that these in vitro diagnostic tests are critical for identifying patient subpopulations most likely to benefit from specific targeted drugs, thereby minimizing adverse pharmacological reactions and optimizing healthcare expenditure across global clinical networks.
Key market drivers, restraints, challenges, and opportunities shaping Companion Diagnostics For Targeted Therapies Market
Growth is propelled by an expanding oncology drug pipeline and rising demand for personalized healthcare solutions. However, stringent regulatory hurdles imposed by agencies like the FDA and EMA create substantial time-to-market delays. Reimbursement complexities remain a primary restraint, though lucrative opportunities emerge within liquid biopsy applications and decentralized testing models utilized by reference laboratories.
Emerging trends and growth patterns in Companion Diagnostics For Targeted Therapies Market
The shift toward Next Generation Sequencing and multi-biomarker detection is redefining clinical paradigms. Decentralized genomic profiling is gaining traction as hospitals and physician laboratories seek rapid turnaround times. This evolution favors agile diagnostic innovators capable of integrating advanced bioinformatics services with high-throughput diagnostic analyzers to handle complex molecular datasets efficiently.
How did the COVID-19 pandemic impact the Companion Diagnostics For Targeted Therapies Market and its recovery trajectory?
The pandemic caused severe disruptions in routine oncology screenings and clinical trial recruitment. Despite initial contractions, molecular diagnostic capabilities experienced accelerated funding and infrastructure expansion. Our research reveals that post-pandemic recovery is robust, driven by surging clinical reliance on automated laboratory instruments and digital pathology systems to maintain workflow continuity during operational backlogs.
Competitive Benchmarking and Market Concentration
The landscape features intense competition among industry heavyweights like F. Hoffmann-La Roche Ltd, Thermo Fisher Scientific Inc., and Qiagen N.V., who leverage extensive assay portfolios and strategic pharma partnerships. Market concentration remains moderately high, with specialized players such as Guardant Health Inc. and Foundation Medicine Inc. carving out dominant niches in circulating tumor DNA testing.
Executive summary of key findings about Companion Diagnostics For Targeted Therapies Market
Our comprehensive evaluation projects the Companion Diagnostics For Targeted Therapies Market to expand from 6.96 Billion in 2026 to 17.96 Billion by 2033, registering a robust 14.50% CAGR. Precision oncology, technological convergence with artificial intelligence, and expanding reimbursement frameworks represent the primary pillars sustaining this remarkable trajectory.
Long-Term Market Forecast from 2027 to 2033
Driven by the commercialization of novel biologic therapies, the market is set for exponential acceleration, scaling to 17.96 Billion by 2033 at a 14.50% CAGR. Sequential revenue expansion will be heavily anchored by increased adoption of companion assays within emerging economies and expanding clinical indications outside oncology, particularly in cardiovascular and neurological diseases.
Structural Segmentation Analysis of the Industry
The market divides into distinct operational categories. By product, it encompasses Assays, Kits, And Reagents, Instruments And Systems, and Software And Services. End users range from Hospitals And Physician Laboratories to Pharmaceutical And Biotechnology Companies. Indications span Oncology, Cardiovascular, and Neurological Diseases, utilizing technologies such as Polymerase Chain Reaction, Next Generation Sequencing, and Immunohistochemistry across tissue and blood samples.
Geographic Distribution and Regional Performance Trends
Geographic performance is led by North America, supported by robust reimbursement frameworks and early adoption of advanced genomic testing. Europe follows closely, governed by stringent European Medicines Agency regulations. Meanwhile, the Asia-Pacific region demonstrates the fastest growth velocity, propelled by expanding healthcare infrastructure in China and Japan alongside rising clinical trial investments.
In-Depth Regional Review and Localized Market Constraints
North America retains market dominance due to high concentration of biotechnology innovators and favorable FDA policies accelerating breakthrough devices. Conversely, market penetration in Latin America and MEA faces structural hurdles, including limited healthcare expenditure and variable reimbursement policies for high-cost molecular assays, restricting adoption primarily to elite metropolitan reference centers.
Strategic Positioning of Leading Companies
Industry leaders deploy distinct commercial strategies to secure market share. Illumina Inc. and Agilent Technologies Inc. focus on proprietary sequencing platforms and hardware dominance. Meanwhile, Exact Sciences Corporation and Natera Inc. concentrate on non-invasive screening assays, while Tempus AI Inc. integrates clinical data platforms to bridge diagnostics with advanced bioinformatics and patient management.
Porter's Five Forces Analysis of the Competitive Environment
The threat of new entrants is moderate due to steep regulatory barriers and high capital requirements for proprietary instrument validation. Bargaining power of buyers is substantial among large hospital networks, whereas supplier power remains low given the commoditization of raw biochemical reagents. Competitive rivalry is fierce among established diagnostics giants vying for exclusive pharma co-development deals.
SWOT Analysis of the Global Industry Landscape
Strengths include high clinical efficacy of targeted drugs and strong IP portfolios held by market leaders. Weaknesses involve complex regulatory approval timelines and high test costs. Opportunities lie in emerging liquid biopsy applications and AI-driven data interpretation services. Threats stem from potential reimbursement cuts and stringent cross-border data privacy regulations affecting bioinformatics platforms.
Value Chain Analysis from Raw Materials to End-Users
The value chain initiates with specialty chemical suppliers providing raw enzymes and oligonucleotides for molecular diagnostic kits. Mid-stream activities involve assay development, clinical validation, and manufacturing by diagnostic corporations. Downstream distribution flows through reference laboratories and hospital networks, ultimately delivering actionable biomarker reports to prescribing oncologists and clinicians.
Investment Insights and High-Potential Growth Areas
Investors should direct capital toward next-generation sequencing platforms, decentralized digital pathology systems, and advanced bioinformatics services. Companies specializing in minimal residual disease detection and blood-based sample preparation reagents offer exceptional ROI potential as clinical demand shifts decisively toward non-invasive, real-time monitoring of therapeutic responses.
Conclusion and Key Takeaways for Industry Stakeholders
The Companion Diagnostics For Targeted Therapies Market represents a high-growth, innovation-driven sector poised to achieve 17.96 Billion by 2033. Success requires strategic alignment with decentralized testing trends, robust regulatory navigation, and proactive partnerships with pharmaceutical developers to co-create synchronized diagnostic and therapeutic assets.
Research Methodology and Data Triangulation Protocols
Our baseline estimates are derived through rigorous data triangulation, combining trade registry data, primary stakeholder interviews with key opinion leaders, and secondary macroeconomic indicators. We cross-reference corporate filings from firms like Danaher Corporation and bioMérieux S.A. with national health statistics to ensure maximum accuracy in our market sizing models.
Scope of the Report and Analytical Limitations
This report covers global market dynamics for companion diagnostics from 2026 through 2033, analyzing segments across products, technologies, sample types, and end users. Analytical limitations include potential variances in regional healthcare policy shifts, unpredictable macro-inflationary pressures, and the inherent volatility of fast-moving biotechnology regulatory approvals across international jurisdictions.
Recent Developments, Product Launches, and Strategic Partnerships
Recent market activity highlights intense collaborative efforts, exemplified by co-development agreements between pharma giants and diagnostic innovators like Caris Life Sciences Inc. and Myriad Genetics Inc. Recent product launches emphasize automated, high-throughput Next Generation Sequencing assays designed to reduce operational friction in clinical laboratories and expand actionable biomarker panels globally.