Market overview of the Weapon System Air Defense Systems Market
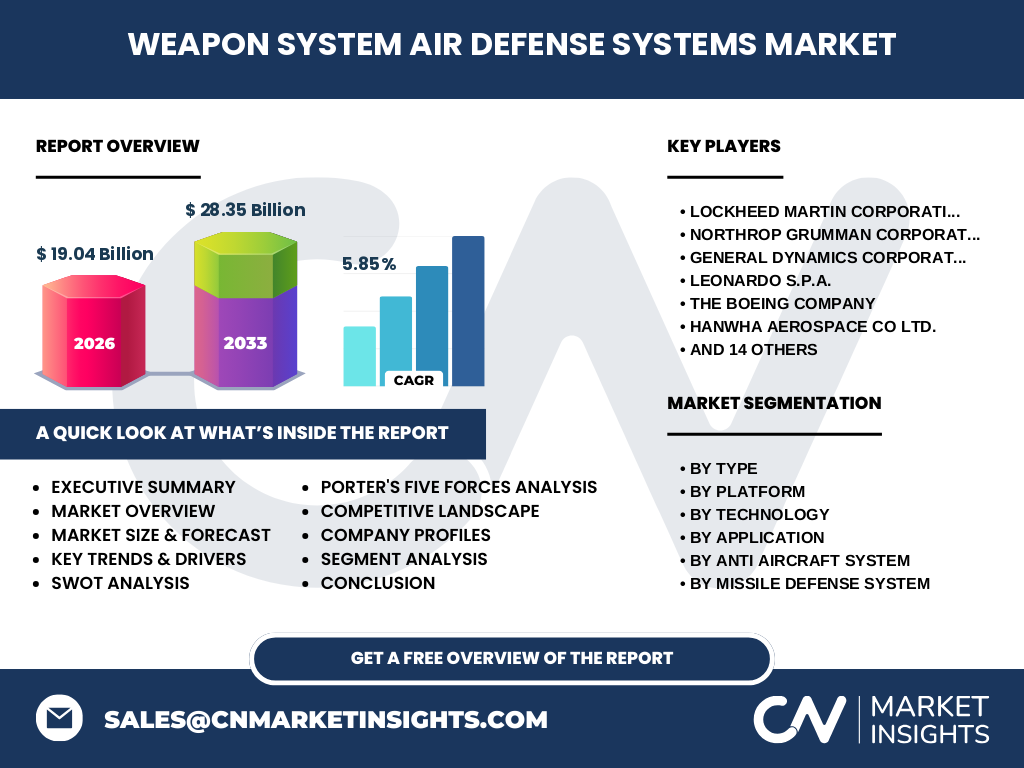
Our analysis indicates that the Weapon System Air Defense Systems Market is valued at $19.04 billion in 2026. This sector encompasses critical defensive architecture ranging from Missile Defense Systems to Counter Unmanned Aerial Systems. Industry significance is underscored by escalating geopolitical volatility, requiring advanced land, naval, and airborne interception capabilities to protect sovereign airspace against modern asymmetric threats.
Structural Growth Drivers and Market Constraints
The market is propelled by a CAGR of 5.85% driven by surging defense budgets and the proliferation of low-cost drones. Conversely, primary market restraints involve stringent export controls governed by ITAR and multilateral Wassenaar Arrangement frameworks. Supply chain bottlenecks concerning specialized rare-earth raw materials like neodymium for radar actuators continue to challenge component lead times for prime contractors.
Emerging Technological Evolution and Growth Patterns
The industry is experiencing a decisive shift toward Directed Energy Counter Drone Systems and Hypersonic Missile Defense Systems. Integration of AI-driven Command And Control Systems is reshaping tactical decision-making. Technology innovators are prioritizing multi-domain interoperability, allowing legacy radar assets to seamlessly cue modern missile interceptors during high-tempo engagement scenarios.
COVID-19 Impact Analysis and Post-Pandemic Recovery
The pandemic severely disrupted Tier-2 and Tier-3 sub-component suppliers, creating acute logistical hurdles in microchip procurement and specialized metallurgy. Recovery trajectories accelerated rapidly post-2022 as national governments categorized defense manufacturing as an essential critical infrastructure sector, catalyzing multi-year procurement backlogs for major primes.
Competitive Benchmarking and Strategic Dynamics
Market concentration is high, featuring defense conglomerates like Lockheed Martin Corporation, Raytheon equivalents, and Northrop Grumman Corporation leading major prime contracts. Strategic dynamics are defined by aggressive cross-border joint ventures, such as MBDA S.A.S initiatives, and targeted acquisitions of niche anti-drone software startups to capture expanding homeland security budgets.
Executive Summary of the Weapon System Air Defense Systems Market
Our comprehensive report reveals a robust valuation trajectory, expanding from $19.04 billion in 2026 to reach $28.35 billion by 2033. Driven by persistent regional conflicts and modernization mandates, the market offers exceptional growth across Counter Rocket Artillery And Mortar Systems and advanced radar technologies. Defense procurement executives must prioritize software-defined architectures to maintain competitive advantages.
Long-Term Market Forecast from 2027 to 2033
Based on our econometric modeling, the market will surge from 2027 through 2033 to achieve a total valuation of $28.35 billion, expanding at a steady 5.85% CAGR. Accelerated procurement cycles in Eastern Europe and the Indo-Pacific will fuel sustained demand for mobile counter-battery and terminal phase interception systems over the forecast period.
Segmentation Analysis by Platform, Type, and Technology
The market segments by Type include Missile Defense System, Anti Aircraft System, Counter Rocket Artillery And Mortar Systems, and Counter Unmanned Aerial Systems. Platforms span Land, Naval, and Airborne architectures. Technologically, Radar Systems, Missile Interceptors, and Electronic Warfare Systems form the operational backbone, addressing Homeland Security, Military And Defense, and Critical Infrastructure Protection applications.
Geographic Distribution and Regional Performance
Regional performance is spearheaded by North America and the Asia-Pacific, fueled by rising defense expenditures in the US, Taiwan, and Japan. European markets show unprecedented growth owing to continental joint procurement initiatives. Localized market constraints in the Middle East focus heavily on rapid-deployment counter-drone solutions to safeguard energy infrastructure.
In-Depth Regional Review of Key Defense Hubs
North America retains the largest revenue share, supported by robust Department of Defense outlays for homeland defense. Meanwhile, the Asia-Pacific exhibits the fastest regional growth rate, driven by maritime territorial disputes and extensive acquisitions involving domestic firms like Bharat Electronics Limited and Mitsubishi Electric Corporation.
Strategic Positioning of Leading Industry Players
Key industry participants such as Israel Aerospace Industries Ltd., Rafael Advanced Defense Systems Ltd., and Kongsberg Gruppen ASA leverage proven combat-tested architectures like the Iron Dome and NASAMS. European stalwarts including Diehl Defence GmbH And Co. KG and Saab AB focus on modular, networked air defense solutions tailored for NATO interoperability.
Porter's Five Forces Analysis of the Defense Sector
Supplier power is moderately high due to specialized aerospace-grade composites and semiconductor dependencies. Buyer power remains constrained to sovereign ministries of defense. The threat of new entrants is remarkably low, restricted by massive capital expenditure requirements, complex regulatory certifications, and entrenched intellectual property portfolios of established primes like The Boeing Company and Airbus.
SWOT Analysis of the Weapon System Air Defense Systems Market
Strengths include highly sophisticated interception capabilities and strong government backing. Weaknesses involve prolonged product development cycles. Opportunities center on unserved emerging economies upgrading obsolete Soviet-era assets. Threats include severe supply chain disruptions and geopolitical export restrictions impacting revenue realization for players like ASELSAN A.Ş and Roketsan.
Value Chain Analysis from Raw Materials to End-Users
The value chain originates with raw material providers supplying titanium alloys, carbon fibers, and gallium arsenide semiconductors. Mid-stream Tier-1 contractors—including Leonardo S.p.A., Safran, and Bharat Dynamics Limited—integrate sub-assemblies into complete radar and missile systems, ultimately delivering finished assets to sovereign military end-users.
Investment Insights and High-Potential Growth Areas
Strategic investment should target directed-energy counter-drone start-ups and scalable software algorithms for automated threat classification. Venture capital and private equity targeting the defense sector will find high-margin opportunities in commercial-off-the-shelf (COTS) integration for rapid deployment capabilities, bypassing traditional multi-year procurement delays.
Conclusion and Strategic Takeaways
The Weapon System Air Defense Systems Market represents a highly lucrative arena driven by unavoidable modernization imperatives. With market size reaching $19.04 billion in 2026 and scaling to $28.35 billion by 2033, stakeholders must invest in agile, multi-domain architectures to capture expanding defense outlays worldwide.
Research Methodology and Baseline Triangulation
Our baseline estimates are rigorously triangulated by cross-referencing national defense budget allocations, trade registry data from the Stockholm International Peace Research Institute (SIPRI), and primary interviews with C-suite executives across major primes like Hanwha Aerospace Co Ltd. and General Dynamics Corporation, validated against macroeconomic indicators.
Scope and Limitations of the Research Report
This report covers global market dynamics for weapon system air defense systems from 2026 to 2033, analyzing segmentation across types, platforms, technologies, and applications. Limitations include the exclusion of classified black-budget military programs and unverified bilateral defense transfers between non-transparent state actors.
Recent Developments, Partnerships, and Product Launches
Recent industry developments highlight accelerated co-development agreements between transatlantic defense firms. Prominent strategic moves include joint radar-upgrade contracts awarded to Elbit Systems Ltd. and accelerated European procurement initiatives designed to counter sophisticated cruise missile threats in contested regional environments.