What is the scope and industry significance of the Military Aircraft Modernization Retrofit Market?
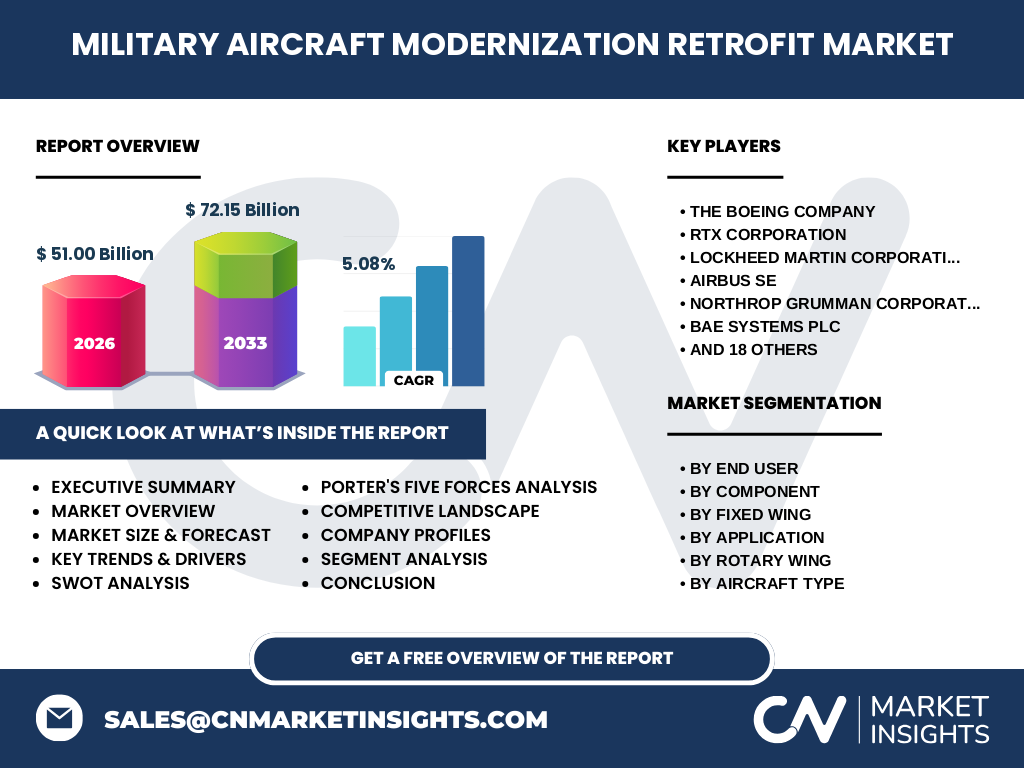
The Military Aircraft Modernization Retrofit Market represents a vital sector valued at $51.00 Billion in 2026. This market encompasses life-extension programs, avionics upgrades, and propulsion overhauls for aging defense fleets, enabling air forces globally to bypass the prohibitive costs of acquiring entirely new airframes while maintaining strategic deterrence capabilities.
Structural Growth Drivers and Market Restraints
Our analysis indicates that escalating defense budgets and the imperative need to upgrade legacy platforms drive robust demand. Conversely, stringent military airworthiness certifications and complex supply chain bottlenecks for raw materials like titanium and carbon composites serve as prominent restraints, challenging major defense primes to optimize their maintenance schedules.
Emerging Trends in the Retrofit Sector
The shift toward digital cockpits, open-architecture avionics, and optionally manned systems is transforming the sector. Industry leaders like RTX Corporation and Lockheed Martin Corporation are capitalizing on these trends by integrating advanced electronic warfare suites into legacy platforms to counter modern anti-access/area-denial threats.
COVID-19 Impact Analysis and Recovery Trajectory
The pandemic severely disrupted global aerospace supply chains, delaying scheduled depot-level maintenance and retrofits. However, our research shows a vigorous post-pandemic recovery trajectory, propelled by government-backed stimulus packages aimed at sustaining national defense industrial bases and accelerating digital transformation initiatives.
Competitive Benchmarking and Strategic Dynamics
Market concentration remains high, dominated by tier-one primes such as The Boeing Company, Northrop Grumman Corporation, and BAE Systems plc. These industry giants leverage aggressive mergers, acquisitions, and strategic teaming agreements to secure lucrative government depot contracts and secure their market positions.
Executive Summary: High-Level Synthesis
The data suggests that the Military Aircraft Modernization Retrofit Market is poised for accelerated expansion, moving from $51.00 Billion in 2026 to $72.15 Billion by 2033 at a CAGR of 5.08%. Fleet aging and geopolitical tensions dictate that upgrading existing assets is a fiscal and operational necessity.
Market Forecast from 2027 to 2033
Projections establish that the market will expand steadily at a compound annual growth rate of 5.08%, culminating in a total valuation of $72.15 Billion by 2033. This consistent trajectory reflects sustained multi-year defense spending commitments across North America, Europe, and the Asia-Pacific region.
Segmentation Analysis of Airframes and Systems
The market breaks down across several categories. By end user: Air Force, Navy, Army, Coast Guard, and Special Forces. By component: Avionics, Weapon System, Propulsion, and Other Components. By fixed wing: Fighter, Transport, Bomber, Surveillance, Trainer, Maritime Patrol, Tanker, and Special Mission Aircraft. By application: Combat, Multi Role, Surveillance, Search And Rescue, Transport, and Other Applications. By rotary wing: Attack, Transport, Utility, Reconnaissance, Naval, and Training Helicopters. By aircraft type: Fixed Wing, Rotary Wing, and Unmanned Aerial Vehicles (UAV). By UAV: High Altitude Long Endurance, Medium Altitude Long Endurance, Tactical, Combat, Mini, and Micro UAVs.
Geographic Distribution and Performance
Geographic performance varies significantly, with North America retaining the largest revenue share due to extensive fleet upgrade programs managed by dominant primes like L3Harris Technologies Inc. and Sierra Nevada Corporation. Meanwhile, the Asia-Pacific region demonstrates the fastest growth rate driven by regional security dynamics and fleet modernization mandates.
In-Depth Regional Review
European markets focus heavily on interoperability with NATO standards, benefiting regional players like Airbus SE, Thales S.A., Leonardo S.p.A., and Dassault Aviation S.A. In contrast, the Middle East and Asia-Pacific prioritize indigenous retrofit capabilities, creating lucrative partnership opportunities for international defense contractors.
Company Profiles and Competitive Positioning
Leading companies utilize distinct strategic positioning to capture market share. Entities like Elbit Systems Ltd., Israel Aerospace Industries Ltd., and Saab AB specialize in modular avionics and electronic warfare retrofits, offering cost-effective upgrades that appeal to budget-constrained international defense ministries.
Porter's Five Forces Analysis
The threat of new entrants is remarkably low due to stringent military certification hurdles, high capital requirements, and strict intellectual property protections held by incumbent OEMs. Buyer power remains moderate, as defense agencies hold significant leverage while depending on specialized technical expertise from primes like Safran S.A. and Curtiss-Wright Corporation.
SWOT Analysis of the Modernization Landscape
Strengths include deeply established customer relationships and proprietary technical knowledge. Weaknesses involve vulnerability to defense budget shifts. Opportunities lie in UAV integration, while threats stem from complex geopolitical trade restrictions and rising cybersecurity vulnerabilities in upgraded digital systems.
Value Chain Analysis from Raw Materials to End-Users
The value chain initiates with raw material suppliers providing aerospace-grade alloys and specialized electronics. It progresses through component manufacturers like Hensoldt AG and Samtel Avionics Limited, system integration by prime contractors, and concludes with military end-users executing depot-level maintenance and fleet operations.
Investment Insights and High-Potential Areas
Strategic recommendations emphasize investment in predictive maintenance software, cyber-hardened avionics, and modular propulsion systems. Companies such as Korea Aerospace Industries Ltd., Turkish Aerospace Industries Inc., and Astronautics Corporation of America present high-potential targets for stakeholders seeking exposure to niche retrofit technologies.
Conclusion and Key Takeaways
The Military Aircraft Modernization Retrofit Market offers robust opportunities as global defense budgets shift toward maximizing the utility of existing airframes. Reaching $72.15 Billion by 2033, success in this market belongs to agile innovators who can integrate next-generation technologies into legacy platforms efficiently.
Research Methodology and Data Triangulation
Our baseline estimates are rigorously triangulated by combining official defense department budget allocations, trade registry data, and primary stakeholder interviews with aerospace engineering executives. Secondary macroeconomic indicators and historical fleet deployment metrics are cross-referenced to ensure forecast accuracy.
Scope of the Report and Analytical Limitations
This report covers global retrofit and modernization activities across fixed-wing, rotary-wing, and unmanned platforms through 2033. Limitations include potential fluctuations in classified military spending budgets and unforeseen geopolitical events that may alter national defense priorities and procurement schedules.
Recent Industry Developments and Strategic Moves
Recent developments feature strategic partnerships and product launches aimed at upgrading tactical fleets. Companies like Aero Vodochody AEROSPACE a.s. have announced joint ventures to modernize trainer aircraft avionics, reflecting an industry-wide push to embed advanced combat simulation tools into legacy flight decks.