What is the Market overview of the Smart Radiation-Free Bone Density Ultrasound Devices Market?
The Smart Radiation-Free Bone Density Ultrasound Devices Market is valued at 0.57 Billion in 2026. Our analysis indicates that this sector encompasses non-ionizing diagnostic technologies utilizing quantitative ultrasound (QUS) and cloud connectivity to evaluate skeletal status, bypassing traditional ionizing radiation constraints associated with dual-energy X-ray absorptiometry.
What are the Structural Growth Drivers and Restraints?
Market expansion is heavily propelled by rising geriatric demographics demanding non-invasive diagnostics. However, reimbursement complexities across localized healthcare jurisdictions act as primary restraints. Regulatory hurdles from bodies like the FDA and EMA impose strict validation timelines on artificial intelligence-enabled algorithms.
Emerging trends and growth patterns
The shift toward decentralized screening is transforming clinical pathways. Our research highlights that Cloud Connected Ultrasound Systems and portable form factors are driving high-volume deployments in retail clinics and non-traditional wellness centers, accelerating recurring SaaS revenue models for manufacturers.
How did the COVID-19 pandemic impact this market?
The pandemic severely disrupted elective orthopedic screenings in 2020 and 2021, temporarily depressing adoption metrics. Nevertheless, the post-pandemic recovery trajectory shows a pronounced bounce-back, driven by an acute clinical preference for point-of-care, easily sanitizable handheld units that minimize patient transit within hospital settings.
Competitive Benchmarking and Industry Concentration
The competitive landscape features a mix of specialized innovators and established medtech corporations. Pioneers like Echolight S.p.A. and BeamMed Ltd. lead technological differentiation via proprietary echogenic spectrum analysis, while regional manufacturers such as Pinyuan Medical optimize supply chain economics for emerging markets.
Executive Summary of the Smart Radiation-Free Bone Density Ultrasound Devices Market
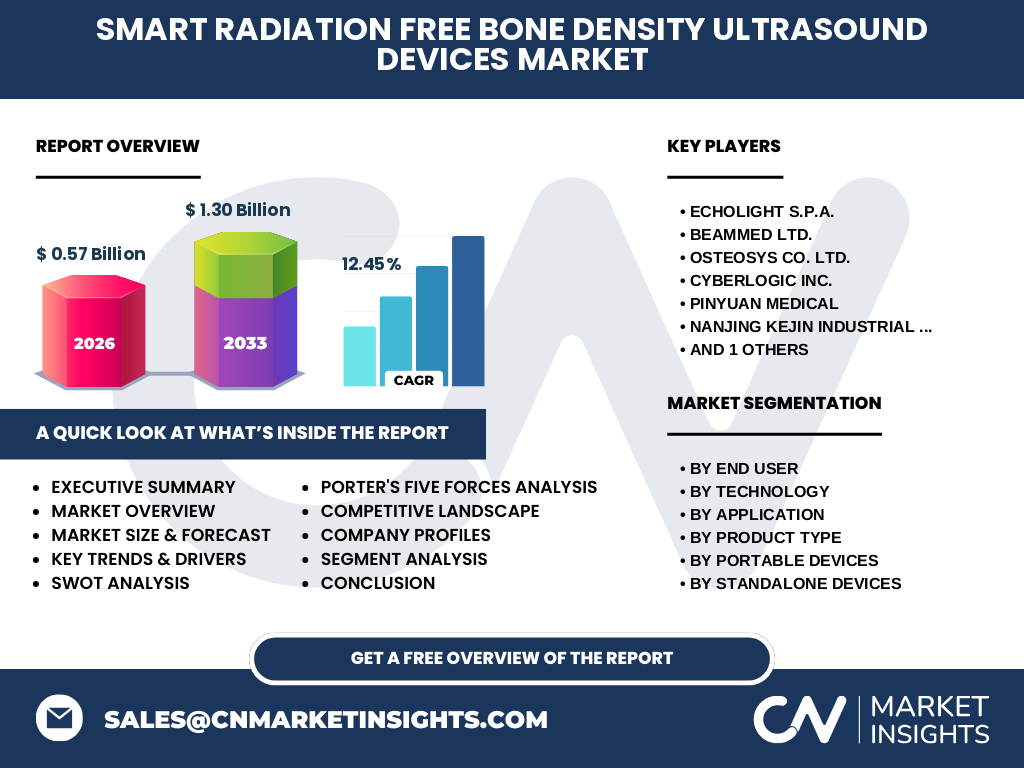
Our comprehensive audit reveals a dynamic, high-growth sector set to expand from 0.57 Billion in 2026 to 1.30 Billion by 2033. Strategic consolidation, aggressive R&D in AI diagnostics, and a 12.45% CAGR underline exceptional commercial viability for early-stage investors and medical device conglomerates alike.
Long-Term Market Forecast from 2027 to 2033
Projected growth indicates the market will surge at a robust 12.45% CAGR, scaling total industry valuation from 0.57 Billion in 2026 to reach 1.30 Billion by 2033. This trajectory reflects widespread clinical integration across primary care settings globally.
Segmentation Analysis Across End Users and Technologies
By End User, the market segments into Hospitals, Diagnostic Centers, Specialty Clinics, and Home Care Settings. Technology segments encompass Quantitative Ultrasound, Artificial Intelligence Enabled, and Cloud Connected systems, each addressing distinct clinical workflows ranging from osteoporosis diagnosis to fracture risk assessment.
Regional Market Analysis and Geographic Performance
Geographic performance demonstrates stark disparities driven by reimbursement frameworks. North America maintains revenue dominance due to rapid technological adoption, whereas Asia-Pacific emerges as the fastest-expanding theater, propelled by aggressive healthcare infrastructure investments by domestic firms like Jiangsu Yikang Electronic Technology.
In-Depth Regional Review
European markets prioritize regulatory compliance under the European Medical Device Regulation (MDR), favoring established regional players like OsteoSys Co. Ltd. and Echolight. Conversely, North American adoption focuses heavily on Point Of Care Bone Density Devices that seamlessly integrate into existing electronic health record ecosystems.
Strategic Company Profiles
Market leaders deploy distinct competitive strategies to capture share. CyberLogic Inc. and Nanjing Kejin Industrial Co. Ltd. focus on algorithmic precision and cost-effective hardware manufacturing, respectively. Meanwhile, BeamMed prioritizes lightweight wireless form factors tailored for ambulatory and geriatric home care delivery models.
Porter's Five Forces Analysis
Industry rivalry remains intense among established ultrasound innovators, while the threat of substitution from traditional dual-energy X-ray systems is steadily declining due to radiation safety concerns. Supplier power is moderate, balanced by specialized piezoelectric transducer manufacturers and software algorithm developers.
SWOT Analysis of the Industry
Key strengths lie in radiation safety and portability, contrasting with weaknesses such as clinician skepticism regarding ultrasound accuracy versus legacy modalities. Opportunities abound in preventative wellness home care, while threats stem from stringent international regulatory clearance processes and reimbursement erosion.
Value Chain Analysis from Raw Materials to End-Users
The value chain originates with advanced piezoelectric ceramic sourcing, silicon wafer fabrication for microprocessors, and proprietary software engineering. Finished devices flow through specialized distributors and direct sales channels to end-users spanning multi-specialty hospitals and mobile diagnostic screening units.
Investment Insights and High-Potential Areas
High-potential capital allocation centers on software-as-a-medical-device (SaMD) integration and AI-driven bone microarchitecture analytics. Investors should target nimble manufacturers offering Wireless Bone Density Ultrasound Devices positioned to capture explosive demand in decentralized outpatient clinics and preventative wellness programs.
Conclusion and Key Takeaways
The smart radiation-free bone density ultrasound devices market represents a transformative intersection of preventive medicine and digital health. With clear momentum pushing valuations to 1.30 Billion by 2033, stakeholders must prioritize regulatory agility, cloud ecosystem integration, and targeted clinician education initiatives.
Robust Research Methodology
Baseline estimates are meticulously triangulated by synthesizing proprietary trade registry data, primary qualitative interviews with key opinion leaders, and secondary macroeconomic indicators. Our quantitative models apply rigorous regression analysis to validate shipment volumes, average selling prices, and regional reimbursement trends.
Scope of the Report
This report evaluates the global market across defined parameters, including product types like portable versus standalone units, distribution channels, and application modalities. Geographic scope spans North America, Europe, Asia-Pacific, Latin America, and the Middle East and Africa, excluding bespoke custom-built research prototypes.
Recent Industry Developments
Recent strategic moves emphasize cloud integration and clinical validation partnerships. Key market participants have aggressively launched next-generation handheld diagnostics featuring enhanced AI diagnostic assistance, alongside strategic distribution agreements aimed at expanding market penetration across emerging healthcare networks in Southeast Asia.