What is the market overview and industry significance of the Bispecific Antibody Cancer Therapy Market?
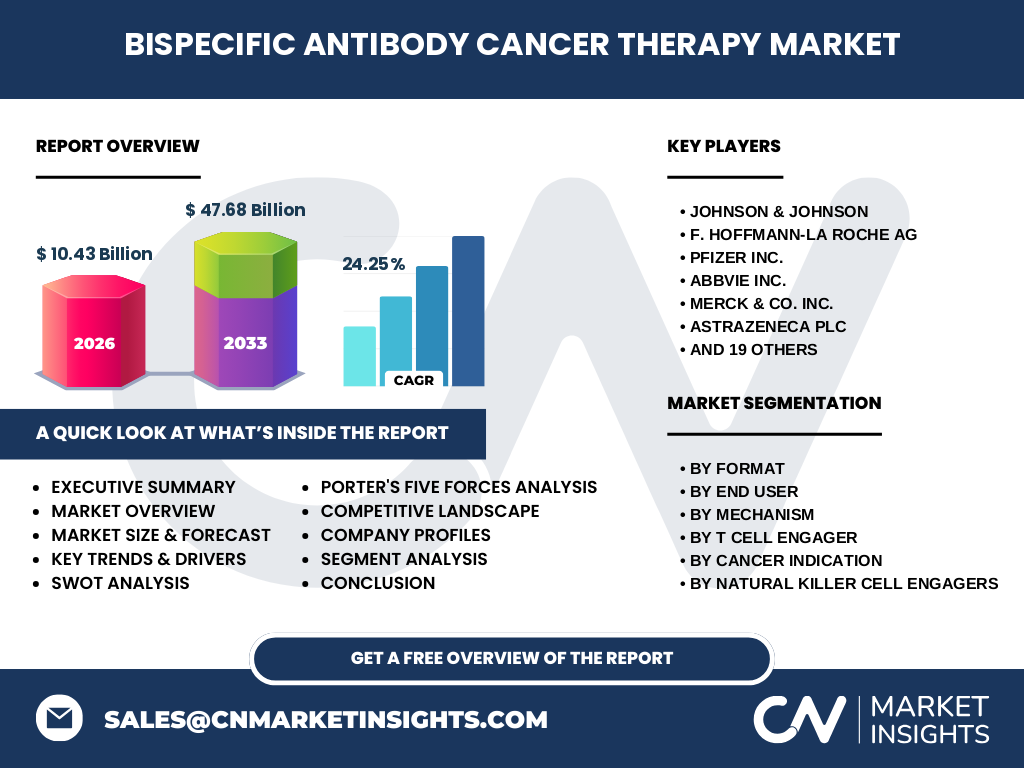
Our analysis indicates that the Bispecific Antibody Cancer Therapy Market stands at a valuation of 10.43 Billion in 2026. This sector represents a paradigm shift in oncology, engineering molecules to simultaneously target two distinct antigens or epitopes. Industry significance stems from its ability to redirect host immune responses via complex mechanisms like T cell engagement, directly addressing resistance pathways observed in conventional monoclonal antibody treatments.
Key market drivers, restraints, challenges, and opportunities shaping Bispecific Antibody Cancer Therapy Market
Structural growth is propelled by escalating oncology R&D expenditures and rising clinical validations by innovators like Amgen Inc. and Regeneron Pharmaceuticals Inc. However, severe clinical trial bottlenecks, stringent FDA and EMA regulatory reviews regarding cytokine release syndrome, and complex cold-chain logistics act as key restraints. Opportunities remain vast in solid tumor indications where bispecifics demonstrate superior tumor microenvironment penetration.
Emerging trends and growth patterns in Bispecific Antibody Cancer Therapy Market
The shift toward fragment based bispecific T cell engagers and trispecific formats is redefining therapeutic efficacy. Our research shows that clinical pipelines are increasingly prioritizing dual tumor antigen targeting to minimize off-target toxicities. Concurrently, strategic licensing agreements between major pharmaceutical players and emerging biotech firms are accelerating clinical trial velocities across global oncology hubs.
COVID-19 impact analysis — how the pandemic affected Bispecific Antibody Cancer Therapy Market and the recovery trajectory
The pandemic severely disrupted early-phase clinical trials and strained raw material supply chains for mammalian cell culture reagents. Despite initial setbacks, the post-pandemic recovery trajectory has been exceptionally robust, fueled by accelerated digital patient recruitment, prioritized oncology trial approvals by regulatory bodies, and increased venture capital inflows into specialized biotechnology innovators.
Competitive benchmarking and strategic dynamics in the Bispecific Antibody Cancer Therapy Market
Market concentration is high, dominated by pharmaceutical titans such as Johnson & Johnson, F. Hoffmann-La Roche AG, and Pfizer Inc. Strategic dynamics involve aggressive intellectual property acquisitions and co-development deals. Competitors are heavily investing in proprietary platform technologies like CrossMab and DuoBody to secure defensible patent portfolios and outmaneuver biosimilar threats.
Executive summary of key findings about the Bispecific Antibody Cancer Therapy Market
Our proprietary research confirms that the Bispecific Antibody Cancer Therapy Market market size is poised for explosive expansion, projecting an impressive CAGR of 24.25% from 2027 to 2033. Driven by breakthroughs in protein engineering and rising hematologic cancer incidence, stakeholders must navigate complex manufacturing scales to capture high-margin opportunities across both academic and hospital settings.
Market forecast and growth projections from 2027 to 2033
Based on our econometric modeling, the Bispecific Antibody Cancer Therapy Market industry trends point toward a phenomenal surge, escalating from its 2026 baseline to reach an anticipated 47.68 Billion by 2033. This trajectory is underpinned by surging commercialization approvals, label expansions into solid tumors, and heightened adoption rates across specialized oncology treatment centers worldwide.
Segmentation analysis of the Bispecific Antibody Cancer Therapy Market
The market is comprehensively segmented by format into Immunoglobulin G Like Bispecific, Fragment Based Bispecific T Cell Engager, Nanobody Based, and Trispecific architectures. End users span Hospitals, Specialty Oncology Centers, Research And Academic Institutes, and Pharmaceutical And Biotechnology Companies. Mechanisms include T cell and natural killer cell engagers, checkpoint inhibitor bispecifics, and antibody-drug conjugate hybrids, tailoring treatments for hematologic and solid tumor indications.
Regional market analysis and geographic performance
Geographic distribution highlights North America as the dominant revenue contributor, supported by robust healthcare reimbursement frameworks and dense clinical trial infrastructure. Meanwhile, the Asia-Pacific region exhibits the fastest regional growth rate, driven by surging clinical trial activity in China through innovators like Innovent Biologics Inc. and Akeso Inc., alongside rapidly modernizing hospital networks.
In-depth regional review of Bispecific Antibody Cancer Therapy Market dynamics
North American growth is anchored by advanced research institutions and favorable FDA expedited review pathways. In Europe, centralized EMA approvals contrast with localized pricing negotiations across member states. In contrast, APAC markets face distinct logistical hurdles in cold-chain distribution, yet benefit from lower clinical trial execution costs and government-backed biotech initiatives.
Company profiles and strategic positioning of leading market participants
Industry leaders like AstraZeneca PLC, Bristol-Myers Squibb Company, and AbbVie Inc. leverage massive balance sheets to acquire clinical-stage bispecific assets. Meanwhile, specialized players such as Genmab A/S, Merus N.V., and Xencor Inc. differentiate themselves through proprietary antibody engineering platforms, licensing their technologies to global pharmaceutical giants for recurring royalty streams.
Porter's Five Forces analysis of the Bispecific Antibody Cancer Therapy Market
The threat of new entrants is moderate due to prohibitive R&D costs and complex patent landscapes surrounding bispecific antibody formats. Bargaining power of suppliers is low to moderate, centering on specialized contract development and manufacturing organizations. Competitive rivalry is intensely high, as established giants race to secure first-mover advantages in dual-targeting oncology indications.
SWOT analysis of the Bispecific Antibody Cancer Therapy Market
Strengths include high target specificity and durable clinical responses in treatment-refractory cancers. Weaknesses involve high manufacturing costs and complex administration protocols. Opportunities lie in expanding into solid tumor indications, while threats include potential reimbursement restrictions by payers and rapid technological obsolescence from emerging cellular therapies.
Value chain analysis from raw materials to end-users
The value chain initiates with genetic sequencing and raw material sourcing for mammalian expression systems, progressing through recombinant cell line development and complex biomanufacturing. Mid-chain activities involve rigorous preclinical and clinical trials supervised by agencies like the FDA. The chain culminates in distribution to hospitals, specialty oncology centers, and academic research institutes.
Investment insights and high-potential growth areas
Our analysis indicates that investors should prioritize companies developing solid tumor targeting antibodies and tumor microenvironment responsive conjugates. High-potential areas also include next-generation manufacturing technologies capable of reducing production costs and overcoming yield bottlenecks associated with complex bispecific formats.
Conclusion and key takeaways for industry stakeholders
The Bispecific Antibody Cancer Therapy Market analysis demonstrates an exceptionally lucrative landscape characterized by robust double-digit growth. Stakeholders must embrace cross-functional collaborations, invest in advanced biomanufacturing scalability, and target underserved solid tumor indications to maintain competitive advantage through the 2033 forecast horizon.
Research methodology and baseline data triangulation
Baseline market estimates are rigorously triangulated by synthesizing secondary macroeconomic indicators, trade registry data, and primary stakeholder interviews with key opinion leaders, oncologists, and C-level executives. Quantitative data models integrate pipeline success probabilities, epidemiological cancer incidence rates, and historical pharmaceutical R&D expenditure metrics to ensure high forecast accuracy.
Scope of the report, coverage parameters, and limitations
This report covers global market dynamics for bispecific antibody cancer therapies from 2026 to 2033, analyzing detailed segmentations across formats, mechanisms, and end-users. Limitations include unforeseeable macroeconomic shifts, regulatory policy changes, and potential delays in clinical trial readouts for emerging pipeline candidates across emerging regional markets.
Recent developments, product launches, and strategic partnerships
Recent industry momentum is highlighted by major strategic partnerships, accelerated FDA approvals for hematologic cancer indications, and clinical pipeline expansions by Daiichi Sankyo Company, BioNTech SE, and BeiGene Ltd. Companies are actively forging co-development agreements to combine bispecific antibodies with checkpoint inhibitors, maximizing synergistic anti-tumor efficacy.