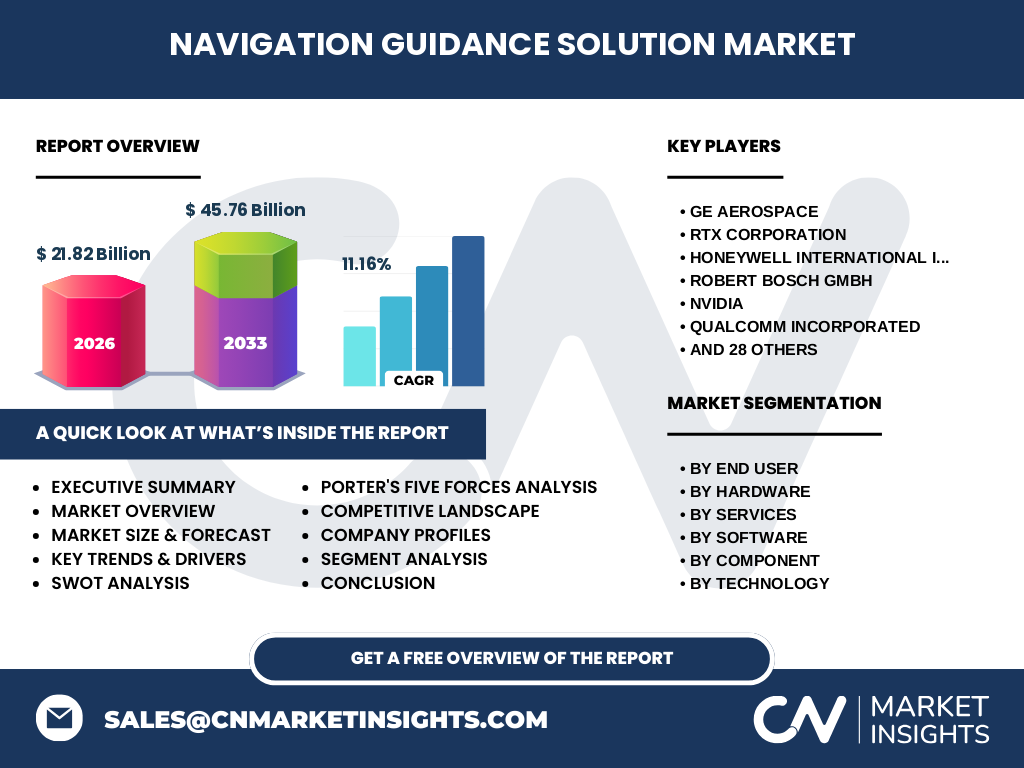
What is the market overview of the Navigation Guidance Solution Market?
Our analysis indicates that the Navigation Guidance Solution Market is valued at $21.82 Billion in 2026, driven by critical requirements for high-precision positioning across aerospace, defense, and autonomous transport systems. Key players like Honeywell International Inc., RTX Corporation, and Northrop Grumman Corporation anchor an industry utilizing specialized silicon wafers, rare-earth magnets, and atomic clocks to build resilient Inertial Navigation Systems (INS) and Global Positioning System (GPS) receivers that withstand severe electromagnetic interference and environmental stress.
Structural Growth Drivers and Market Restraints
Growth in the Navigation Guidance Solution Market is heavily propelled by the proliferation of autonomous vehicles, unmanned aerial systems, and strict international maritime safety mandates imposed by the International Maritime Organization (IMO). However, our research highlights significant restraints, including susceptibility to GNSS signal jamming and spoofing, alongside prohibitive manufacturing costs for high-grade ring laser gyroscopes. This creates a challenging operational landscape for firms like Safran S.A. and Thales S.A.
Emerging Trends in Navigation Guidance Solution Industry Trends
The shift toward sensor fusion and non-GPS dependent navigation dominates current Navigation Guidance Solution industry trends. Defense contractors and commercial fleet managers increasingly demand quantum sensors and Light Detection And Ranging (LiDAR) integration to ensure uninterrupted positioning where satellite signals fail. Advanced Navigation Pty Ltd and VectorNav Technologies LLC lead this technological curve, developing compact attitude and heading reference systems that merge inertial data with computer vision algorithms.
How did COVID-19 impact the Navigation Guidance Solution Market?
The COVID-19 pandemic caused severe supply chain disruptions across semiconductor foundries and specialized component manufacturing facilities, temporarily stalling production lines for GNSS receivers and display units. Nevertheless, the post-pandemic recovery trajectory has been exceptionally robust, fueled by accelerated digital transformation in logistics and increased defense modernization budgets. Enterprises quickly rebounded by prioritizing automated supply chain routing and remote maintenance services.
Competitive Benchmarking and Strategic Dynamics
Competitive intensity in the Navigation Guidance Solution Market remains high, characterized by continuous R&D investments and strategic cross-sector acquisitions. Industry titans such as GE Aerospace, Garmin Ltd., and Trimble Inc. compete fiercely through proprietary mapping software and high-accuracy GNSS hardware. Meanwhile, nimble innovators like Swift Navigation Inc. and NovAtel challenge incumbents by offering scalable, software-defined correction services that lower barriers to entry for commercial drone operators.
Executive Summary of the Navigation Guidance Solution Market Analysis
Our comprehensive Navigation Guidance Solution Market analysis reveals a high-growth sector projected to expand from $21.82 Billion in 2026 to $45.76 Billion by 2033, achieving a stellar 11.16% CAGR. This dynamic expansion is underpinned by pervasive automation demands in land, airborne, and marine navigation platforms. Stakeholders must focus on multi-sensor redundancy and software-hardware integration to capture emerging high-margin opportunities.
Navigation Guidance Solution Market Forecast from 2027 to 2033
Based on our econometric modeling, the Navigation Guidance Solution Market will surge from $21.82 Billion in 2026 to reach $45.76 Billion by the end of 2033, maintaining a compound annual growth rate of 11.16%. This upward trajectory is heavily supported by escalating investments in autonomous commercial shipping, precision agriculture, and smart city infrastructure requiring sub-meter positioning accuracy across urban canyons and remote industrial sites.
Segmentation Breakdown of Navigation Guidance Solution Market
The Navigation Guidance Solution Market is segmented comprehensively across multiple dimensions to address specific operational needs. By component, the market spans Hardware (sensors, receivers, antennas, control units, display units), Software (navigation, mapping, routing, data processing, simulation), and Services (installation, integration, maintenance, consulting, support). Technology divisions include Global Positioning System, Inertial Navigation System, Radio Detection And Ranging, and Light Detection And Ranging, deployed across aerospace, automotive, marine, and defense end users.
Geographic Distribution and Regional Market Analysis
Regional performance in the Navigation Guidance Solution Market varies significantly based on local defense expenditure, regulatory mandates, and automotive manufacturing density. North America maintains a dominant revenue share due to extensive aerospace and defense programs managed by RTX Corporation and Lockheed Martin. Meanwhile, the Asia-Pacific region exhibits the fastest growth rate, driven by rapid urbanization, massive smart port developments in Singapore and Shanghai, and burgeoning automotive sectors in Japan and South Korea.
In-Depth Regional Review of Navigation Guidance Solution Deployment
Our regional deep-dive shows that North America benefits from rigorous Federal Aviation Administration (FAA) NextGen air traffic modernization initiatives, boosting demand for advanced airborne navigation solutions. In Europe, strict European Union Aviation Safety Agency (EASA) compliance and European Maritime Safety Agency directives compel commercial vessels and aircraft to adopt highly robust radio detection and radar systems, directly benefiting regional players like TomTom N.V., HERE Technologies, and Robert Bosch GmbH.
Strategic Positioning of Leading Companies
Market leaders employ distinct strategic positioning to capture specialized verticals within the Navigation Guidance Solution Market. Qualcomm Incorporated and NVIDIA focus on high-performance semiconductor chipsets for automotive autonomous driving, while Trimble Inc. and Topcon Corporation dominate precision agriculture and construction surveying. Defense-oriented giants like Elbit Systems Ltd. and Israel Aerospace Industries prioritize jam-resistant military navigation systems integrated tightly with tactical data links.
Porter's Five Forces Analysis of the Industry
Porter's Five Forces assessment indicates moderate-to-high competitive rivalry driven by rapid technological obsolescence and aggressive pricing from emerging software providers. Threat of new entrants remains low due to extreme R&D capital requirements for inertial sensors and rigorous aerospace certification hurdles. Bargaining power of suppliers is moderate, as specialized silicon foundries and atomic clock manufacturers hold significant leverage over raw material pricing and component availability.
SWOT Analysis of the Navigation Guidance Solution Sector
The Navigation Guidance Solution Market features robust strengths in high-accuracy positioning and multi-sensor redundancy, balanced against weaknesses like vulnerability to cyber-attacks and signal jamming. Prime opportunities lie in autonomous robot taxis and drone delivery corridors, while major threats include escalating geopolitical tensions disrupting rare-earth supply chains and strict spectrum allocation regulations imposed by bodies like the Federal Communications Commission.
Value Chain Analysis from Raw Materials to End-Users
The industry value chain begins upstream with raw material providers supplying silicon, quartz, and specialized alloys for inertial sensors. Midstream participants—including Honeywell International Inc., Safran S.A., and Garmin Ltd.—fabricate hardware components, write complex navigation software, and assemble control units. Downstream, systems integrators deploy these solutions into commercial aircraft, military vehicles, and marine vessels managed by logistics operators and defense ministries worldwide.
Investment Insights and High-Potential Areas
Strategic investment should target firms developing resilient, non-GNSS navigation technologies such as quantum inertial measurement units and celestial navigation software. Venture capital and private equity firms will find high-potential returns in software-defined radio navigation startups and autonomous fleet management platforms. Companies capable of securing military-grade certifications while scaling cost-effective commercial solutions represent prime acquisition targets in this $45.76 Billion market.
Conclusion and Key Industry Takeaways
The Navigation Guidance Solution Market represents a vital technological frontier, expanding rapidly from $21.82 Billion in 2026 to $45.76 Billion by 2033 at an 11.16% CAGR. Success in this ecosystem hinges on robust sensor fusion, cyber-resilient architectures, and multi-platform adaptability across aerospace, defense, and automotive verticals. Industry participants must proactively adapt to tightening regulatory standards and shifting geopolitical supply chain dynamics.
Research Methodology for Baseline Estimates
Our baseline estimates and market forecasts for the Navigation Guidance Solution Market are meticulously triangulated using a blend of primary stakeholder interviews with C-level executives, exhaustive analysis of trade registry data from customs authorities, and secondary macroeconomic indicators published by organizations like the International Civil Aviation Organization. This rigorous multi-tiered approach ensures high fidelity in sizing segments across hardware, software, and services.
Scope of the Report and Coverage Parameters
This research report encompasses global deployment trends within the Navigation Guidance Solution Market, covering land-based, airborne, marine, and space-based navigation platforms. While offering granular breakdowns by component, technology, end user, and application, the analysis deliberately excludes legacy consumer-grade mapping apps not meeting enterprise precision thresholds. Regional evaluations span North America, Europe, Asia-Pacific, Latin America, and the Middle East and Africa.
Recent Developments in the Navigation Guidance Solution Landscape
Recent strategic moves in the Navigation Guidance Solution Market highlight heavy corporate emphasis on strategic partnerships and product innovation. Major collaborations between automotive tier-1 suppliers like DENSO Corporation and tech giants such as Google focus on high-definition mapping integration for autonomous driving. Concurrently, firms like NextNav Inc. and Swift Navigation Inc. have launched advanced terrestrial positioning networks to augment GPS resilience against urban interference.