What is the market overview and industry significance of the Military Autonomous Robot Market?
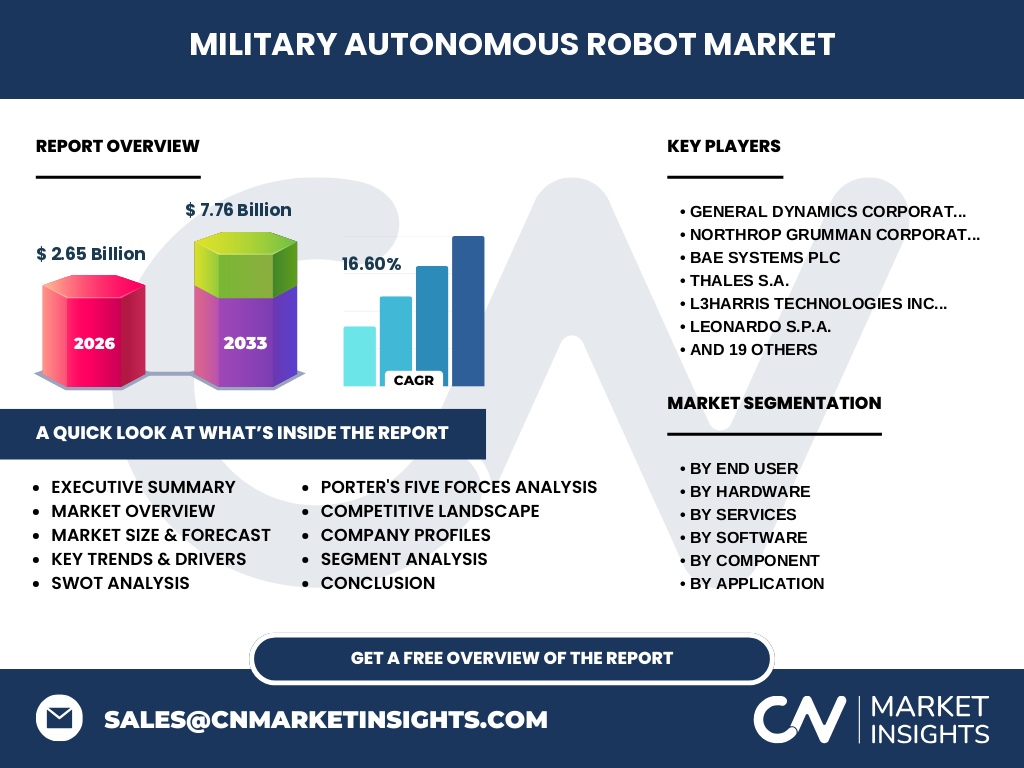
Our analysis indicates that the Military Autonomous Robot Market is valued at $2.65 Billion in 2026. This sector encompasses unmanned ground, aerial, and maritime platforms governed by advanced algorithms, critical for modern defense forces and homeland security agencies operating in contested electromagnetic spectrum environments.
Structural Growth Drivers and Market Restraints
Growth is propelled by rising geopolitical friction and the imperative to reduce combat casualties, pushing demand across Defense Forces. Conversely, the market faces stringent regulatory constraints under ITAR and export controls, alongside technical hurdles in secure, jamming-resistant wireless communications systems.
Emerging Trends and Growth Patterns in the Military Autonomous Robot Market
The shift toward edge computing and resilient swarming architectures is redefining tactical doctrines. Artificial Intelligence and Machine Learning Algorithms are seeing accelerated adoption, enabling real-time target recognition without relying on continuous satellite navigation links.
How did the COVID-19 pandemic impact the Military Autonomous Robot Market recovery trajectory?
Pandemic-induced supply chain bottlenecks for critical semiconductor components temporarily delayed hardware deliveries, yet accelerated long-term automation investments. Defense ministries prioritized contactless logistics and remote surveillance, anchoring a robust recovery trajectory for the broader Component ecosystem.
Competitive Benchmarking and Strategic Dynamics
The competitive landscape features a dual-track dynamic where prime defense contractors like General Dynamics Corporation and Northrop Grumman Corporation compete alongside agile tech innovators such as Anduril Industries and Shield AI, driving rapid integration of proprietary software.
Executive Summary of the Military Autonomous Robot Market Research
Our comprehensive research projects the Military Autonomous Robot Market to surge from $2.65 Billion in 2026 to $7.76 Billion by 2033 at a CAGR of 16.60%. This expansion highlights a structural pivot toward unmanned combat support and intelligence, surveillance, and reconnaissance (ISR) applications.
What is the projected market forecast for the Military Autonomous Robot Market from 2027 to 2033?
Based on our econometric modeling, the market will expand rapidly from 2027 to 2033, culminating at $7.76 Billion. This trajectory reflects sustained budget allocations by major defense agencies toward automated tactical systems and software modernization.
Segmentation Analysis of Hardware, Software, and Services
The market segments by hardware, software, and services, encompassing critical assets like Sensors, Autonomous Navigation Software, and System Integration Services. End users span Defense Forces and Homeland Security Agencies utilizing modes ranging from fully autonomous to remote-controlled.
Geographic Distribution and Regional Market Performance
Geographic performance is heavily concentrated in North America and the Asia-Pacific region, driven by escalating defense modernization budgets and localized border security challenges. European markets are concurrently expanding due to increased regional threat perceptions and joint capability development programs.
In-Depth Regional Review and Operational Constraints
North America maintains the largest revenue share, underpinned by robust domestic defense procurement and elite technology innovators. Meanwhile, the Asia-Pacific region exhibits the fastest deployment pace, constrained primarily by localized logistical hurdles and stringent military certification protocols.
Company Profiles and Strategic Positioning
Industry leaders leverage distinct strategic advantages; for instance, AeroVironment Inc. and Teledyne FLIR LLC dominate tactical aerial ISR, while Milrem Robotics OÜ and Ghost Robotics spearhead ground-based mobility platforms for complex terrain navigation.
Porter's Five Forces Analysis of Competitive Pressures
The threat of new entrants is moderate due to high capital requirements and strict defense accreditation standards. However, bargaining power of buyers is high as consolidated defense ministries dictate stringent performance metrics, custom payloads, and proprietary data rights.
SWOT Analysis of the Military Autonomous Robot Industry
Strengths include advanced sensor fusion and robust artificial intelligence capabilities. Weaknesses involve vulnerability to electronic warfare jamming. Opportunities lie in expanding border patrol contracts, while threats stem from adversarial deployment of counter-drone and cyber-attack vectors.
Value Chain Analysis from Raw Materials to End-Users
The value chain flows from rare earth raw materials and semiconductor foundries to subsystem manufacturers producing actuators and processing units, culminating in prime integrators delivering finished robotic platforms to end-users like Homeland Security Agencies.
Investment Insights and High-Potential Areas
High-potential investment areas concentrate on cybersecurity and encryption software, edge processing units, and modular maintenance repair and overhaul services. Investors should prioritize firms demonstrating interoperability with legacy military command and control architectures.
Conclusion and Strategic Takeaways for Stakeholders
The Military Autonomous Robot Market represents a generational shift in military capabilities, offering a compelling 16.60% CAGR through 2033. Stakeholders must prioritize software adaptability and secure supply chains to capture market share.
Research Methodology for Baseline Estimates
Our baseline estimates are rigorously triangulated by combining defense trade registry data, primary stakeholder interviews with defense procurement officers, and secondary macroeconomic indicators regarding global military expenditure trends.
Scope of the Report and Coverage Parameters
This report covers global deployment dynamics, hardware, software, and service segments through 2033. Limitations include restricted access to classified black-budget military projects and highly confidential bilateral defense acquisition contracts.
Recent Developments, Partnerships, and Strategic Moves
Recent industry dynamics feature aggressive joint ventures between traditional primes like Rheinmetall AG and software specialists like Skydio Inc., focusing on resilient mesh-networking and autonomous reconnaissance capabilities for frontline infantry units.