Market overview and structural significance of the Veterinary Hospital Market
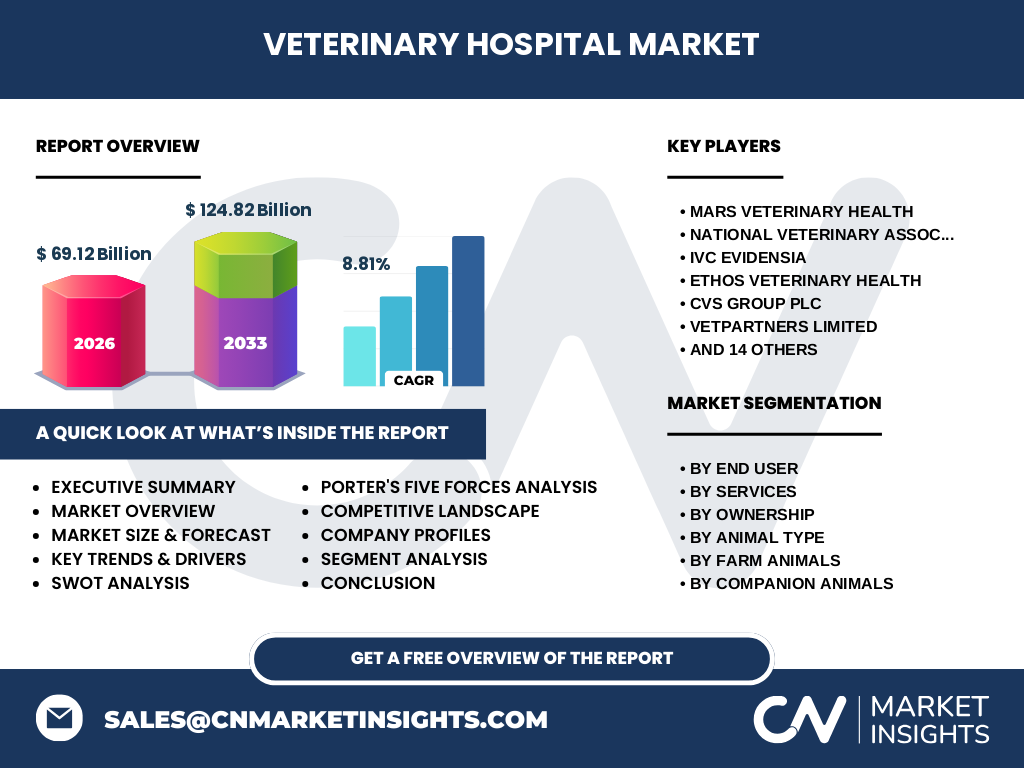
Our analysis indicates the Veterinary Hospital Market is valued at 69.12 Billion in 2026, serving as the cornerstone of animal healthcare infrastructure. This sector encompasses advanced clinical facilities, surgical centers, and diagnostic laboratories regulated by bodies such as the FDA and USDA, ensuring rigorous compliance across biological therapeutics, pharmaceutical raw materials, and specialized medical devices.
Structural Growth Drivers and Market Restraints
Based on our research, the Veterinary Hospital Market industry trends are propelled by surging pet humanization and advanced diagnostics adoption. However, structural restraints include severe labor shortages of licensed veterinary technicians and strict compliance hurdles enforced by the Drug Enforcement Administration regarding controlled veterinary analgesics and anesthetics.
The Shift Toward Advanced Digital Diagnostics and Specialized Care
The data suggests a profound industry shift toward specialized oncology, neurology, and telemedicine integrations within modern veterinary clinics. Major innovators like Mars Veterinary Health and Ethos Veterinary Health are pioneering this transition, deploying cloud-based PACS imaging and AI-driven diagnostic software to improve clinical outcomes across companion animal practices.
Pandemic Aftermath: COVID-19 Impact Analysis and Recovery Trajectory
The pandemic dramatically accelerated adoption within the Veterinary Hospital Market due to unprecedented pet adoption surges. While supply chain bottlenecks for surgical instruments and personal protective equipment initially constrained operations, clinics rebounded through contactless curbside care models and accelerated investments in digital client communication platforms.
Competitive Benchmarking and Consolidation Dynamics
Consolidation defines the competitive landscape, with private equity-backed consolidators acquiring independent practices aggressively. Enterprises like National Veterinary Associates, IVC Evidensia, and CVS Group plc leverage centralized procurement and standardized clinical protocols to optimize operational efficiencies and achieve robust economies of scale.
Executive Summary: Core Findings of the Veterinary Hospital Market Analysis
Our comprehensive Veterinary Hospital Market analysis projects rapid expansion from 69.12 Billion in 2026 to 124.82 Billion by 2033, achieving a stellar 8.81% CAGR. Strategic opportunities heavily favor corporate veterinary groups investing in specialized diagnostic infrastructure and preventative wellness programs.
Long-Term Market Forecast Through 2033
The market trajectory points toward explosive valuation gains, moving from 69.12 Billion in 2026 to reach 124.82 Billion by 2033 at an 8.81% CAGR. This robust momentum is underwritten by expanding disposable incomes and rising insurance penetration among pet owners globally.
Segmentation Analysis Across End Users, Services, and Ownership Models
Segmentation spans multiple critical vectors: By End User (Pet Owners, Livestock Owners, Animal Shelters), By Services (General Veterinary Services, Diagnostic Services, Surgical Services, Other Services), By Ownership (Private, Public), and By Animal Type (Companion Animals including dogs, cats, birds, rabbits, small mammals, exotic pets; and Farm Animals including cattle, poultry, swine, sheep, goats, equine animals).
Geographic Distribution and Regional Market Performance
Regional performance varies significantly, with North America leading in advanced surgical adoption, followed by Europe's stringent animal welfare mandates. Meanwhile, Asia-Pacific represents the fastest-growing frontier, driven by rising middle-class disposable incomes and expanding livestock operations in countries like China and India.
In-Depth Regional Review of Veterinary Healthcare Infrastructure
North America dominates the Veterinary Hospital Market size due to high veterinary expenditure per household and dense corporate consolidation networks. Europe follows closely, heavily influenced by European Medicines Agency regulations governing veterinary pharmaceuticals, while emerging Asia-Pacific markets focus heavily on livestock health and poultry biosecurity.
Strategic Positioning of Leading Companies in the Veterinary Hospital Market
Industry leaders maintain distinct strategic positioning. Mars Veterinary Health dominates through massive corporate scale, Ethos Veterinary Health leads in high-acuity specialty referral care, and agile innovators like Petfolk Inc. are redefining primary care delivery through tech-enabled, frictionless clinic models and transparent pricing.
Porter's Five Forces Analysis of Competitive Pressures
Bargaining power of suppliers remains moderate, constrained by specialized pharmaceutical manufacturers, while buyer power is fragmented among individual pet owners. However, threat of new entrants is dampened by high capital expenditure requirements for advanced imaging equipment like MRI and CT scanners within veterinary hospitals.
SWOT Analysis of the Veterinary Hospital Market
Key strengths include resilient recession-proof demand and rising animal health budgets. Weaknesses involve high staff burnout rates and veterinary debt burdens. Opportunities lie in artificial intelligence diagnostics and preventative pet care subscriptions, while threats include regulatory crackdowns on corporate consolidation and rising biomedical waste disposal costs.
Value Chain Analysis from Raw Materials to End-Users
The value chain originates with chemical and biological raw material suppliers providing active pharmaceutical ingredients, flowing through medical device manufacturers and pharmaceutical distributors. These inputs culminate in veterinary hospital networks, where practitioners deliver specialized therapeutics directly to companion animal owners and livestock operators.
Investment Insights and High-Potential Growth Areas
High-potential investment targets include veterinary teleradiology startups, specialized oncology centers, and cloud-based practice management software providers. Investors are prioritizing scalable clinic models with proven recruitment pipelines capable of mitigating industry-wide veterinary talent shortages.
Conclusion and Strategic Takeaways for Industry Stakeholders
The Veterinary Hospital Market presents compelling growth dynamics, underpinned by an 8.81% CAGR leading to 124.82 Billion by 2033. Stakeholders must embrace technological modernization, operational consolidation, and specialized care pathways to capture outsized market share.
Research Methodology and Baseline Triangulation
Baseline market estimates are rigorously triangulated by combining veterinary board registry data, primary executive interviews with hospital medical directors, and macroeconomic indicators from agencies like the World Organisation for Animal Health. Cross-validation ensures high-fidelity market sizing across all segments and geographic regions.
Scope of the Report and Coverage Parameters
This report evaluates the global Veterinary Hospital Market across specified animal types, ownership structures, and service classifications from 2026 through 2033. Limitations exclude unregulated over-the-counter animal supplements and non-hospitalized ambulatory farm visits outside established clinical billing codes.
Recent Developments: Corporate Partnerships and Strategic Moves
Recent industry developments feature aggressive M&A activity by private-equity-backed groups like National Veterinary Associates and IVC Evidensia acquiring regional multi-site practices. Concurrently, innovators such as Apiam Animal Health Limited are expanding digital telehealth integrations and investing in automated diagnostic lab equipment to streamline workflows.