What is the market overview of the Flavored Milk Powder Drinks Market?
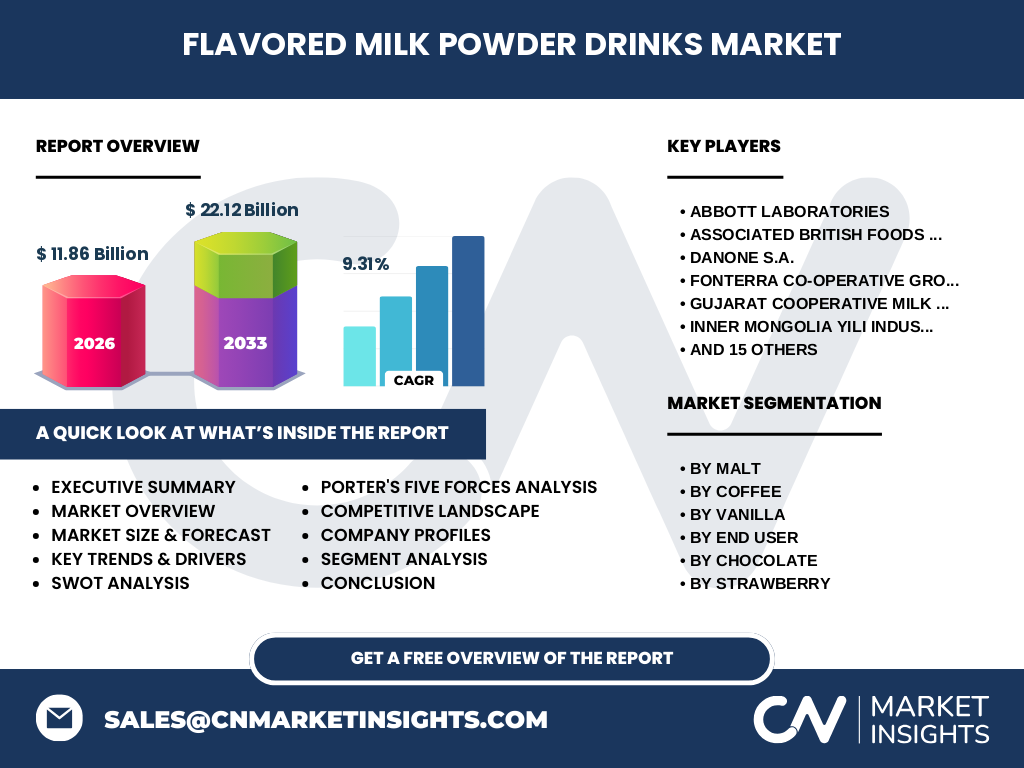
Our research indicates the Flavored Milk Powder Drinks Market encompasses globally traded shelf-stable dairy and plant-based beverage bases regulated by bodies like the FDA and EFSA. Valued at $11.86 Billion in 2026, the industry converts spray-dried milk solids combined with cocoa, malt extracts, and coffee into high-demand retail powders handled via major logistics hubs.
Key market drivers, restraints, challenges, and opportunities shaping Flavored Milk Powder Drinks Market
Structural growth relies on extended product shelf-life demanded by supply chains across developing economies. However, volatile skimmed milk powder (SMP) commodity pricing acts as a persistent restraint. Opportunities flourish in functional fortifications, while major challenges involve strict sugar-reduction mandates enforced by regional health ministries.
Emerging trends and growth patterns in Flavored Milk Powder Drinks Market
The shift toward clean-label formulations and organic ingredients dominates recent industry trends. Consumers increasingly demand Plant-Based and Mixed Dairy Plant Blends over traditional dairy. Our analysis shows double-digit uptake in functional variants containing added vitamins, probiotics, and adaptogens across urban retail corridors.
COVID-19 impact analysis — how the pandemic affected Flavored Milk Powder Drinks Market and the recovery trajectory
The pandemic dramatically accelerated at-home consumption, causing supply chain bottlenecks for essential packaging materials like Cans and Pouches. Post-pandemic recovery reflects a robust upward trajectory, driven by consumer stockpiling behavior and heightened awareness of nutritional immunity through fortified beverages.
Competitive landscape — major players, market concentration, and strategic dynamics
Market concentration is moderately high, led by multinational conglomerates such as Nestlé S.A., Abbott Laboratories, and Danone S.A. These dominant players leverage vast distribution networks in Supermarkets Or Hypermarkets. Smaller regional brands compete via niche offerings like Organic Or Natural Vanilla and regional flavor profiles.
Executive summary — high-level synthesis of key findings about Flavored Milk Powder Drinks Market
Driven by rising disposable incomes, the Flavored Milk Powder Drinks Market size is set for explosive expansion. Industry revenues will surge from $11.86 Billion in 2026 to $22.12 Billion by 2033 at a remarkable CAGR of 9.31%, fueled by continuous product innovation across diverse packaging formats.
Market forecast — projected growth from 2027 to 2033
Our proprietary financial models project steady acceleration, taking the sector from the 2026 baseline of $11.86 Billion toward the $22.12 Billion valuation by 2033. This 9.31% CAGR is propelled by aggressive emerging market penetration and premiumization strategies deployed by category leaders.
Segmentation analysis — break down each segment category, explain what it covers and its market role
Segmentation spans Flavor Types (Chocolate, Strawberry, Vanilla, Malt, Coffee), Ingredient Types (Dairy Based, Plant-Based, Mixed Dairy Plant Blends), and Packaging Types (Sachets, Jars, Cans, Pouches). Dairy Based chocolate and malt variants maintain historical volume dominance, while plant-based and single-serve sachet formats capture rapid incremental growth.
Regional market analysis — geographic distribution and performance across regions
Geographic performance reveals strong concentration in Asia-Pacific, supported by robust domestic dairy production by giants like Inner Mongolia Yili Industrial Group and Vinamilk. Western markets exhibit steady demand for functional and low-sugar alternatives distributed heavily through Online Retail channels.
In-depth regional review — detailed examination of key regional markets
Asia-Pacific leads consumption volume, heavily influenced by localized dietary habits favoring nutrient-fortified malt and chocolate beverages for children. Meanwhile, North America and Europe prioritize convenience and clean-label credentials, driving rapid adoption of portion-controlled sachets and plant-based formulations.
Company profiles — strategic positioning of leading companies in Flavored Milk Powder Drinks Market
Industry leaders maintain distinct competitive moats. Nestlé S.A. and Mondelēz International leverage massive brand equity in chocolate and malted beverages, whereas Fonterra Co-operative Group and Gujarat Cooperative Milk Marketing Federation (Amul) utilize integrated dairy supply chains to optimize cost structures and global export capabilities.
Porter's Five Forces analysis — competitive forces assessment
Supplier power remains moderate due to the commoditized nature of raw milk solids, offset by strong agricultural cooperatives. Threat of new entrants is low given high capital expenditure required for spray-drying infrastructure, while buyer power is elevated by intense retail brand switching.
SWOT analysis — strengths, weaknesses, opportunities, and threats
Strengths include exceptional shelf-life and broad demographic appeal. Weaknesses involve high sensitivity to raw dairy commodity price fluctuations. Opportunities lie in functional health integration, while major threats include tightening government regulations targeting added sugars in children's beverages.
Value chain analysis — industry structure and value flow from raw materials to end-users
The value chain originates with dairy farmers and agricultural commodity suppliers, feeding into large-scale industrial spray-drying and blending facilities operated by firms like Arla Foods and Lactalis Group. Finished goods flow through complex logistics networks to reach Supermarkets Or Hypermarkets and Online Retail.
Investment insights — strategic recommendations and high-potential areas
Investors should target emerging producers specializing in Plant-Based and High Protein Or Fortified sub-segments. Capital allocation toward sustainable packaging solutions, such as recyclable pouches and eco-friendly jars, will capture premium margins amidst tightening environmental regulations.
Conclusion and key takeaways
The Flavored Milk Powder Drinks Market industry trends highlight a sector transitioning from traditional dairy treats to functional nutritional solutions. Achieving a projected $22.12 Billion by 2033, winning operators will successfully balance indulgence with clean-label health benefits.
Research methodology — detail how baseline estimates are triangulated
Our baseline $11.86 Billion valuation for 2026 is triangulated using bottom-up manufacturing output data, cross-referenced with import-export customs registries from major maritime ports, and validated through primary executive interviews with supply chain directors across key multinational dairy enterprises.
Scope of the report — coverage parameters and limitations
This report evaluates global market dynamics for flavored milk powder preparations across 2026 to 2033. Limitations exclude ready-to-drink liquid milk beverages, focusing strictly on dry powder formulations distributed via retail and institutional channels worldwide.
Recent developments — company announcements, product launches, partnerships, and strategic moves
Recent strategic moves feature major investments in sustainable sourcing and functional product launches. For instance, The Hershey Company and Abbott Laboratories have expanded portfolio offerings to include specialized high-protein and organic variants, responding directly to evolving post-pandemic wellness demands.