Market overview and structural significance of the Specimen Transport Solutions Market
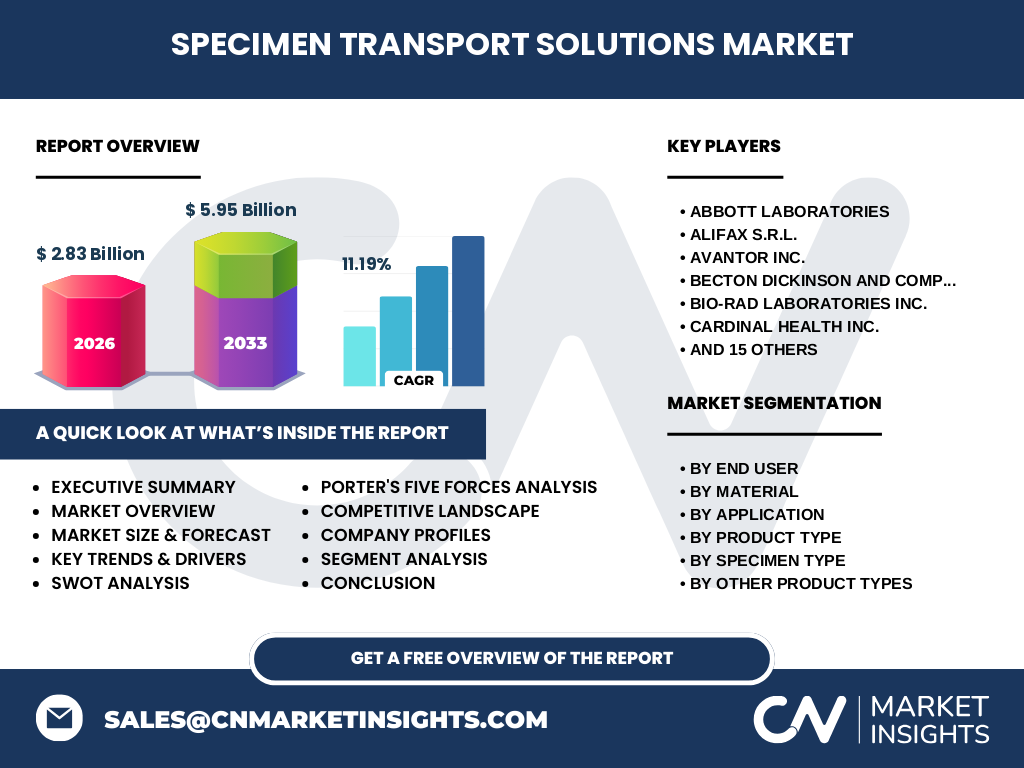
Our analysis indicates that the Specimen Transport Solutions Market represents a critical infrastructure backbone for global healthcare, valued at $2.83 billion in 2026. This sector encompasses specialized products like single, dual, and triple pocket specimen transport bags, vacuum sealed containers, and temperature-controlled boxes. These tools ensure the biological integrity of blood, tissue, and urine samples under strict CDC and IATA regulatory frameworks during transit between clinics, reference laboratories, and research hubs.
Key market drivers, restraints, challenges, and opportunities shaping the industry
The market is propelled by surging demand for decentralized clinical diagnostics and stringent biohazard compliance mandates governed by OSHA. However, cold chain logistics failures and high material costs for insulated and corrugated transport boxes act as notable restraints. Opportunities abound for manufacturers developing reusable, sustainable plastic and metal containment units that minimize biomedical waste while protecting sensitive microbiological specimens against thermal excursions.
Emerging trends and technological transformations in specimen logistics
A definitive shift toward smart supply chains is redefining the Specimen Transport Solutions Market industry trends. Laboratories increasingly adopt IoT-enabled temperature-controlled boxes and data-logging transport coolers to monitor real-time thermal conditions of delicate tissue samples and saliva specimens. This technological integration drastically reduces sample rejection rates, favoring innovative suppliers capable of embedding advanced tracking mechanisms into secondary and tertiary container systems.
COVID-19 impact analysis and pandemic-driven recovery trajectories
The pandemic served as an unprecedented stress test for the Specimen Transport Solutions Market analysis, temporarily halting routine elective diagnostics while driving exponential demand for molecular testing kits, biohazard bags, and viral transport media. Post-pandemic recovery has stabilized supply chains, permanently elevating baseline volumes for clinical diagnostics and cementing robust, pandemic-ready distribution pathways across global hospital networks and commercial testing laboratories.
Competitive landscape and strategic positioning of major industry participants
Market concentration remains moderately fragmented, featuring industry heavyweights such as Becton Dickinson and Company, Thermo Fisher Scientific Inc., and Abbott Laboratories alongside specialized players like Copan Diagnostics Inc. and SARSTEDT AG And Co. KG. Leading entities leverage expansive global distribution networks, regulatory compliance expertise, and strategic mergers to dominate primary and secondary container manufacturing, while logistics giants like United Parcel Service Inc. secure vital transport dominance.
Executive summary of high-level findings for the Specimen Transport Solutions Market
Our comprehensive research confirms that the Specimen Transport Solutions Market is poised for exceptional expansion, driven by decentralized testing and advanced biotechnology applications. Key market metrics highlight a solid baseline of $2.83 Billion in 2026, scaling dramatically toward future valuations. Stakeholders must prioritize temperature-compliance and sustainable material sourcing to capture high-margin segments within clinical diagnostics and pharmaceutical testing pipelines.
Market forecast and projected growth trajectory from 2027 to 2033
Based on our econometric modeling, the Specimen Transport Solutions Market is projected to surge from $2.83 Billion in 2026 to reach $5.95 Billion by 2033, expanding at a robust CAGR of 11.19%. This accelerated growth trajectory reflects escalating investments in precision medicine, increased clinical trial volumes, and heightened global emphasis on rapid, contamination-free diagnostic specimen mobility across international supply chains.
Segmentation analysis across end-users, materials, applications, and product types
The market breaks down by end user into healthcare facilities, research institutes, and biotechnology companies; by material into plastic, glass, and metal; and by application spanning clinical diagnostics, biobanking, and R&D. Product categories range from specialized transport bags and rigid boxes to primary, secondary, and tertiary containers. Each segment plays a pivotal role in safeguarding specific specimen types, including blood, tissue, and microbiological samples, against physical and thermal degradation.
Regional market analysis and geographic distribution performance
Geographic performance highlights North America as the dominant revenue contributor, sustained by advanced healthcare infrastructure and stringent FDA transport mandates. Meanwhile, the Asia-Pacific region exhibits the fastest regional growth rate, driven by expanding clinical trial outsourcing in nations like India and China, alongside rapidly modernizing hospital networks requiring sophisticated biohazard transport bags and temperature-controlled cooling kits.
In-depth regional review of key markets and local regulatory constraints
North American growth is underpinned by stringent CDC and Department of Transportation regulations governing infectious substance transport. In Europe, stringent environmental directives encourage the adoption of reusable and recyclable plastic transport boxes. Meanwhile, Latin American and Middle Eastern markets face logistical hurdles related to extreme ambient temperatures, boosting localized demand for insulated transport coolers and vacuum-sealed containers.
Company profiles and competitive strategies of leading market players
Key market participants employ distinct strategic levers to maintain dominance. Avantor Inc. and Cardinal Health Inc. leverage vast distribution footprints to supply comprehensive kit solutions. Cryoport Inc. specializes in ultra-cold chain logistics for cell and gene therapies, whereas Eppendorf SE and Greiner Bio-One International GmbH focus on high-precision plastic and glass primary containers that guarantee sample integrity in molecular research environments.
Porter's Five Forces analysis of competitive intensity in the sector
Industry rivalry is high, driven by numerous established manufacturers vying for hospital group purchasing contracts. Supplier power remains moderate due to the commoditized nature of basic raw plastics, though specialized thermal insulation vendors hold pricing leverage. Threat of substitution is low given strict regulatory mandates for certified biohazard packaging, while buyer power is substantial among large diagnostic laboratory networks.
SWOT analysis highlighting strategic strengths, weaknesses, opportunities, and threats
Market strengths include robust product portfolios compliant with UN3373 regulations, while weaknesses involve vulnerability to raw material price volatility. Opportunities center on expanding emerging market healthcare networks and smart, trackable transport containers. Key threats encompass supply chain bottlenecks, stringent cross-border regulatory hurdles, and potential contamination liabilities during high-risk infectious disease transit.
Value chain analysis detailing industry structure and material-to-end-user flow
The value chain initiates with petrochemical and glass raw material suppliers feeding specialized manufacturers such as Corning or SARSTEDT AG And Co. KG. These firms fabricate primary vials, bags, and insulated boxes. Mid-chain distributors and logistics partners like United Parcel Service Inc. ensure compliant transport to end-users including clinical laboratories, pharmaceutical developers, and academic research biobanks.
Investment insights and strategic recommendations for stakeholders
Investors and market entrants should prioritize opportunities in smart, temperature-monitored transport boxes and eco-friendly, tamper-evident specimen transport bags. Strategic partnerships with cold-chain logistics providers and biotechnology firms offer high-margin revenue streams. Companies investing in automated, leak-proof packaging solutions are best positioned to capture market share as regulatory scrutiny intensifies globally.
Conclusion and key takeaways for the Specimen Transport Solutions Market
The Specimen Transport Solutions Market represents a dynamic, high-growth sector set to achieve $5.95 Billion by 2033 from a 2026 baseline of $2.83 Billion. Driven by decentralized diagnostics and stringent regulatory compliance, the industry favors agile manufacturers investing in smart, temperature-controlled, and sustainable transport innovations to secure long-term competitive advantage.
Research methodology detailing data triangulation and validation protocols
Our proprietary market estimation methodology combines rigorous primary research—featuring executive interviews with logistics directors and laboratory managers—with comprehensive secondary research, including trade registry databases, customs data, and macroeconomic indicators. Bottom-up sizing models cross-reference regional hospital throughput metrics to ensure absolute accuracy in our $2.83 Billion 2026 valuation and subsequent forecast.
Scope of the report, coverage parameters, and analytical limitations
This report covers global market dynamics for specimen transport solutions across North America, Europe, Asia-Pacific, Latin America, and the Middle East & Africa from 2027 to 2033. Limitations include potential macroeconomic disruptions outside our predictive modeling parameters and localized regulatory shifts affecting cross-border medical device and biohazard packaging approvals.
Recent developments, strategic partnerships, and product launches in the industry
Recent industry momentum highlights aggressive portfolio expansions. Thermo Fisher Scientific Inc. and QIAGEN N.V. have introduced advanced, tamper-evident transport kits tailored for molecular diagnostics. Concurrently, specialized cold-chain innovators like Cryoport Inc. have forged strategic logistics alliances with major pharmaceutical developers to secure ultra-low temperature transport for critical gene therapy specimens.