Executive Summary of the Pathology Services Market
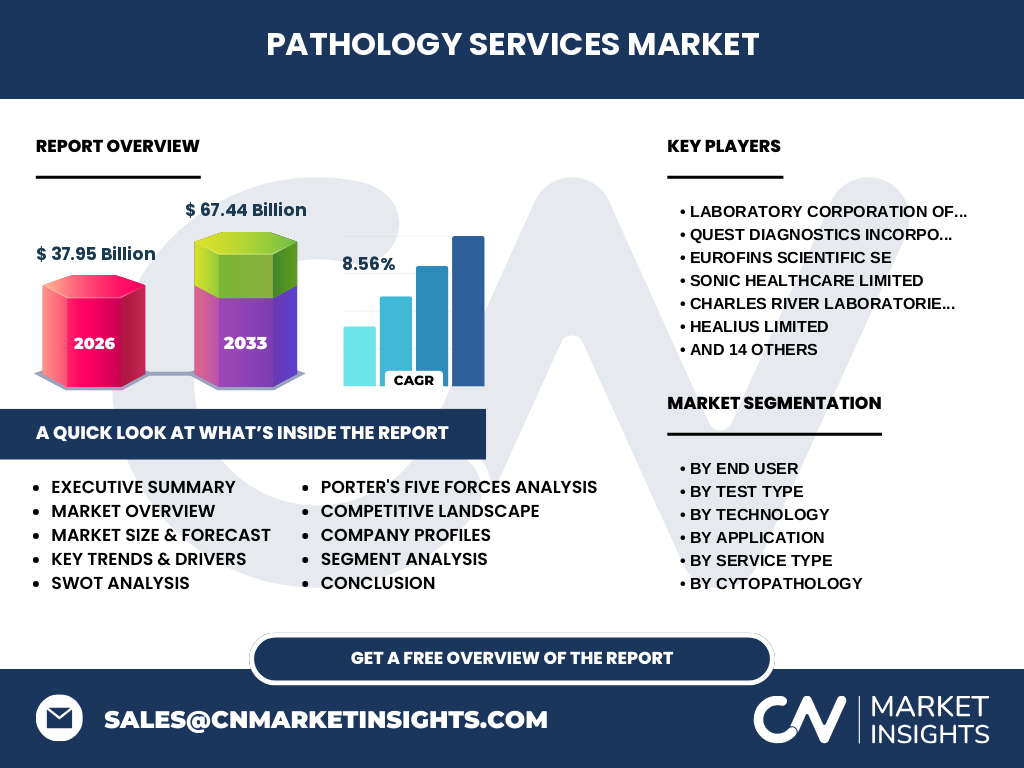
Our analysis indicates that the Pathology Services Market is poised for exceptional expansion, scaling from a baseline valuation of 37.95 Billion in 2026 to reach an impressive 67.44 Billion by 2033. Driven by a robust Compound Annual Growth Rate (CAGR) of 8.56%, this sector reflects critical transformations across clinical diagnostics, driven by technological integration and rising chronic disease burdens regulated by agencies like the FDA and EMA.
What is the scope and market size of the Pathology Services Market?
The Pathology Services Market encompasses specialized diagnostic evaluations across clinical, anatomical, molecular, cytopathology, and forensic disciplines. Valued at 37.95 Billion in 2026, the market forms the backbone of modern clinical decision-making. It operates within strict compliance frameworks overseen by organizations such as the CAP and CLIA, utilizing specialized reagents and automated analysers to process millions of patient samples annually across global healthcare networks.
Structural Growth Drivers and Market Restraints
Key market drivers include the rising prevalence of oncology cases and infectious diseases necessitating advanced molecular diagnostics. Conversely, severe pricing pressures from reimbursement cuts by payers like Medicare and stringent regulatory hurdles for laboratory-developed tests (LDTs) act as notable restraints. Despite these hurdles, the expansion toward personalized medicine offers lucrative opportunities for market participants utilizing platforms from Roche and Abbott.
Emerging Industry Trends in Pathology Services
The pathology services industry trends point toward a profound digital transformation. Laboratories are rapidly adopting digital pathology and artificial intelligence-enabled image analysis to enhance diagnostic accuracy for complex histopathology and surgical pathology slides. This shift significantly reduces turnaround times, minimizes human error, and optimizes workflow efficiency in high-volume reference laboratories managed by major networks.
How did the COVID-19 pandemic impact the Pathology Services Market trajectory?
The COVID-19 pandemic severely disrupted routine elective testing while triggering an unprecedented surge in molecular diagnostics, specifically RT-PCR testing for SARS-CoV-2. This crisis accelerated infrastructural investments in high-throughput automation and supply chain resilience. Consequently, the post-pandemic recovery trajectory has fortified baseline testing volumes, leaving laboratories better equipped for future infectious disease outbreaks and reinforcing long-term market valuation.
Competitive Benchmarking and Market Concentration
The competitive landscape features high market concentration among mega-reference laboratories like Laboratory Corporation of America Holdings and Quest Diagnostics Incorporated, which leverage massive scale and proprietary logistics networks. Meanwhile, specialized innovators such as Fulgent Genetics Inc. and Mayo Clinic Laboratories carve out defensible niches in high-complexity genetic and oncology testing, intensifying strategic competition across the global ecosystem.
Pathology Services Market Forecast Through 2033
Our forecasting models project that the Pathology Services Market will expand from 37.95 Billion in 2026 to 67.44 Billion by 2033, maintaining a steady 8.56% CAGR. This accelerated trajectory is fueled by an aging global demographic, expanded insurance coverage for preventative screenings, and the mainstream adoption of companion diagnostics in oncology therapeutics.
Comprehensive Segmentation Analysis
Market segmentation spans multiple categories: End Users encompass Hospitals, Diagnostic Laboratories, Research Institutions, Physician Offices, and Homecare Settings. Test Types cover Blood Testing, Urine Testing, Tissue Biopsy Testing, Genetic Testing, Microbiological Testing, and Immunological Testing. Technologies range from Laboratory Automation and Digital Pathology to Molecular Diagnostics Technologies and Artificial Intelligence And Data Analytics, while applications focus heavily on Disease Diagnosis and Drug Discovery And Development.
Service Types and Cytopathology Breakdown
Service offerings are categorized into Clinical Pathology, Anatomical Pathology, Molecular Pathology, Cytopathology, and Forensic Pathology. Within cytopathology, sub-segments include Gynecologic Cytology, Non-Gynecologic Cytology, Fine Needle Aspiration (FNA) Cytology, Exfoliative Cytology, Liquid-Based Cytology, Urine Cytology, Respiratory Cytology, and Breast Cytology, each playing a vital role in early cancer detection.
Clinical, Molecular, Anatomical, and Forensic Pathology Sub-segments
Clinical pathology breaks down into Hematology Testing, Clinical Chemistry, Microbiology Testing, Immunology And Serology, Coagulation Testing, Urinalysis, Toxicology Testing, and Blood Banking. Molecular pathology features PCR Testing, Next-Generation Sequencing (NGS), and Companion Diagnostics. Anatomical pathology emphasizes Histopathology and Surgical Pathology, while forensic pathology covers Postmortem Examination and DNA Profiling.
Regional Market Analysis and Geographic Distribution
Geographically, the market performance is led by North America, supported by robust healthcare expenditure and early adoption of molecular diagnostics. Europe follows closely, governed by stringent IVDR regulations. Meanwhile, the Asia-Pacific region demonstrates the fastest growth potential, driven by expanding healthcare infrastructure in countries like India and China, creating high demand for providers such as Dr Lal PathLabs and Guangzhou KingMed Diagnostics Group Co. Ltd.
Strategic Company Profiles in the Pathology Services Market
Industry leaders maintain distinct strategic positioning. Global giants like Eurofins Scientific SE, Sonic Healthcare Limited, and SYNLAB focus on geographic expansion and service portfolio diversification through aggressive mergers and acquisitions. Regional specialists like Krsnaa Diagnostics Limited and MedGenome Labs Ltd. capitalize on public-private partnerships and specialized genomic testing capabilities to capture localized market share.
Porter's Five Forces Assessment
The Porter's Five Forces framework reveals moderate-to-high competitive rivalry among established reference laboratories, balanced by high capital barriers for new entrants requiring stringent CAP and CLIA accreditations. Supplier power remains moderate regarding specialized reagent vendors, while buyer power is high among large hospital networks negotiating volume discounts. Threat of substitution is low due to the irreplaceable nature of pathological diagnosis.
SWOT Analysis of the Pathology Services Sector
Strengths include extensive testing menus and established cold-chain logistics. Weaknesses involve vulnerability to reimbursement cuts and severe pathologist shortages. Opportunities lie in artificial intelligence integration and decentralized point-of-care molecular testing. Threats encompass stringent regulatory compliance costs and evolving cybersecurity risks associated with patient genomic data storage in cloud environments.
Value Chain Analysis from Raw Materials to End-Users
The value chain initiates with raw material suppliers providing assay kits, antibodies, and chemical reagents. These inputs flow to reference laboratories and hospital pathology departments where specimen processing, staining, and genomic sequencing occur. Pathology professionals then interpret findings, delivering critical diagnostic reports to end-users including physicians, clinical researchers, and pharmaceutical companies engaged in drug development.
Investment Insights and Strategic Recommendations
High-potential investment areas center around artificial intelligence diagnostic software, next-generation sequencing infrastructure, and decentralized testing models. Investors should prioritize partnerships with agile laboratories possessing strong digital pathology integration, as these entities are best positioned to overcome workforce shortages and capture margin expansion through automated workflow efficiencies.
Conclusion and Strategic Takeaways
The Pathology Services Market represents a high-value sector projected to reach 67.44 Billion by 2033. Success in this evolving landscape requires continuous technological investment in molecular diagnostics and digital workflows. Organizations that successfully navigate regulatory complexities and forge strategic healthcare partnerships will capture disproportionate market share.
Research Methodology and Baseline Triangulation
Our baseline estimates are rigorously triangulated by combining exhaustive secondary research from trade registries, World Health Organization databases, and macroeconomic indicators with primary interviews involving chief medical officers, laboratory directors, and regulatory affairs specialists. Bottom-up sizing models cross-verified with top-down macroeconomic evaluations ensure high data fidelity.
Scope and Recent Developments in the Market
This report covers global pathology service providers from 2026 to 2033, excluding non-diagnostic wellness sectors. Recent developments highlight active consolidation, with major players like Charles River Laboratories International Inc. and Unilabs expanding their molecular capabilities through strategic acquisitions and partnerships aimed at enhancing oncology and clinical trial support services.