What is the market overview of the Battlefield Artificial Intelligence (AI) Market?
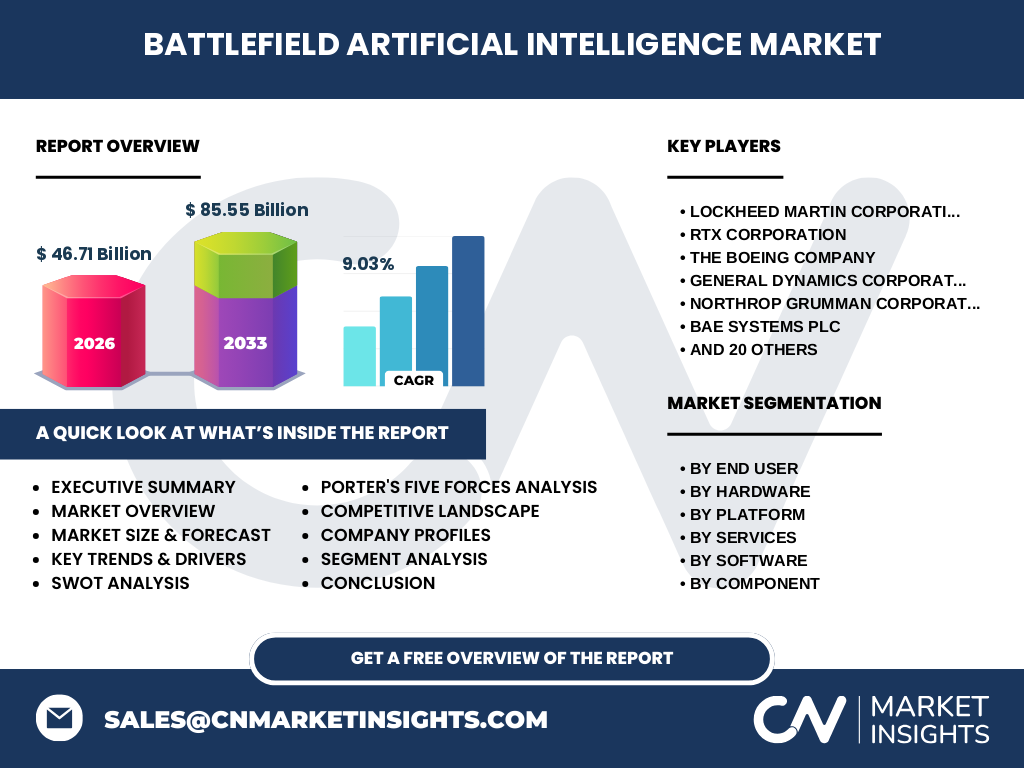
Our analysis indicates that the Battlefield Artificial Intelligence (AI) Market stands at a valuation of $46.71 Billion in 2026. This sector encompasses advanced autonomous platforms, edge computing devices, and specialized processors deployed by defense agencies and intelligence organizations to maintain tactical superiority in complex modern combat theaters.
What are the core growth drivers, restraints, challenges, and opportunities shaping the Battlefield Artificial Intelligence (AI) Market industry trends?
The market is propelled by surging demand for autonomous warfare and target recognition systems, though constrained by strict export controls on rare earth raw materials. Logistical hurdles in secure data fusion create massive opportunities for agile defense tech innovators specializing in resilient tactical edge computing.
Structural Growth Drivers and Emerging Patterns
The data suggests a structural shift toward machine learning and computer vision integration across land-based and airborne systems. This trend favors companies equipped with advanced neural network training capabilities, enabling real-time tactical decision-making and automated threat detection in contested electromagnetic environments.
How did the COVID-19 pandemic impact the Battlefield Artificial Intelligence (AI) Market analysis and recovery trajectory?
Global supply chain disruptions for semiconductor components initially slowed procurement cycles. However, our research shows that post-pandemic defense digitization mandates accelerated adoption of predictive analytics platforms and cyber-defense software, driving a robust 9.03% CAGR toward the 2027-2033 horizon.
Competitive Benchmarking and Market Concentration
Prime contractors like Lockheed Martin Corporation, RTX Corporation, and General Dynamics Corporation dominate traditional hardware integration. Meanwhile, software disruptors such as Palantir Technologies Inc. and Anduril Industries are reshaping market dynamics by deploying scalable, cloud-connected data fusion and intelligence analysis platforms directly to the tactical edge.
Executive Summary of the Battlefield Artificial Intelligence (AI) Market
Our proprietary research confirms that the Battlefield Artificial Intelligence (AI) Market is poised for explosive expansion, reaching $85.55 Billion by 2033. Accelerated by geopolitical friction and multi-domain operations, the market presents lucrative avenues across hardware, software, and specialized integration services for forward-thinking defense contractors.
Market Forecast and Long-Term Projections
Driven by rising defense budgets dedicated to autonomous systems and command and control hardware, the market is projected to expand from $46.71 Billion in 2026 to $85.55 Billion by 2033 at a steady 9.03% CAGR, reflecting sustained global investments in military modernization.
Segmentation Analysis of Components, Hardware, Software, and Platforms
The market is meticulously categorized by End User (Defence, Homeland Security, Intelligence Agencies), Component (Hardware, Software, Services), Technology (Machine Learning, Computer Vision), and Platform (Land, Airborne, Naval, Space Based Systems). Each segment plays a vital role in enabling multi-domain operations and seamless data interoperability.
Regional Market Analysis and Geographic Distribution
North America commands the largest share of the Battlefield Artificial Intelligence (AI) Market due to extensive Pentagon R&D funding. Concurrently, the Asia-Pacific region exhibits the fastest growth trajectory, propelled by localized defense modernization initiatives, territorial tensions, and surging domestic investments in autonomous naval systems.
In-Depth Regional Review and Localized Constraints
Strict ITAR regulations in the United States and stringent European Union defense procurement directives dictate regional go-to-market strategies. Companies operating within these jurisdictions must navigate complex compliance frameworks while integrating edge computing devices and AI-based command and control software into legacy platforms.
Strategic Positioning in Company Profiles
Industry giants like BAE Systems plc, Thales S.A., and Leonardo S.p.A. leverage extensive global footprints to secure multi-nation naval and airborne contracts. Concurrently, specialized AI firms like C3 AI Inc., Shield AI, and Rebellion Defense focus on niche algorithmic superiority, threat detection, and autonomous navigation software.
Porter's Five Forces Analysis of Competitive Pressures
Our analysis indicates moderate-to-high competitive rivalry among prime defense contractors, offset by high switching costs for proprietary command and control hardware. Supplier power remains concentrated around advanced semiconductor fabricators, while the threat of substitution is mitigated by stringent military-grade reliability and security standards.
SWOT Analysis of the Battlefield Artificial Intelligence (AI) Market
Key strengths include robust technological innovation in computer vision. Weaknesses involve vulnerability to adversarial machine learning attacks. Opportunities lie in automated logistics and supply chain management, while threats stem from stringent regulatory compliance hurdles and international export controls.
Value Chain Analysis from Raw Materials to End-Users
The value flow begins with raw semiconductor materials and specialized sensor components, progressing through edge computing hardware assembly and software algorithm training. Integrators then deliver complete systems like autonomous platforms and command centers to defense and intelligence end-users.
Strategic Investment Insights and High-Potential Areas
Investors should target developers of simulation and training services and AI model training services. As military organizations prioritize synthetic training environments and rapid software deployment, firms offering scalable data fusion and cybersecurity solutions represent high-alpha investment opportunities.
Conclusion and Strategic Takeaways
The trajectory of the Battlefield Artificial Intelligence (AI) Market underscores a permanent shift toward intelligent, automated defense. Achieving market leadership requires bridging traditional aerospace manufacturing excellence with cutting-edge artificial intelligence model training and resilient edge computing architectures.
Research Methodology and Triangulation Framework
Baseline estimates are meticulously triangulated by synthesizing defense trade registry filings, primary stakeholder interviews with procurement officials, and secondary macroeconomic indicators. This rigorous multi-source approach ensures high-fidelity market sizing and accurate growth forecasting across all segments.
Scope of the Report and Coverage Parameters
This comprehensive report evaluates the global Battlefield Artificial Intelligence (AI) Market across hardware, software, services, and platforms from 2026 through 2033. Limitations include restricted access to classified black-budget military programs, focusing strictly on publicly disclosed defense procurement and authorized commercial contracts.
Recent Developments and Strategic Industry Moves
Recent months have seen aggressive strategic partnerships between defense primes and AI innovators, exemplified by joint ventures integrating advanced threat recognition software into legacy naval platforms. Companies like Scale AI and BigBear.ai Holdings Inc. continue securing vital intelligence contracts to scale operational readiness.