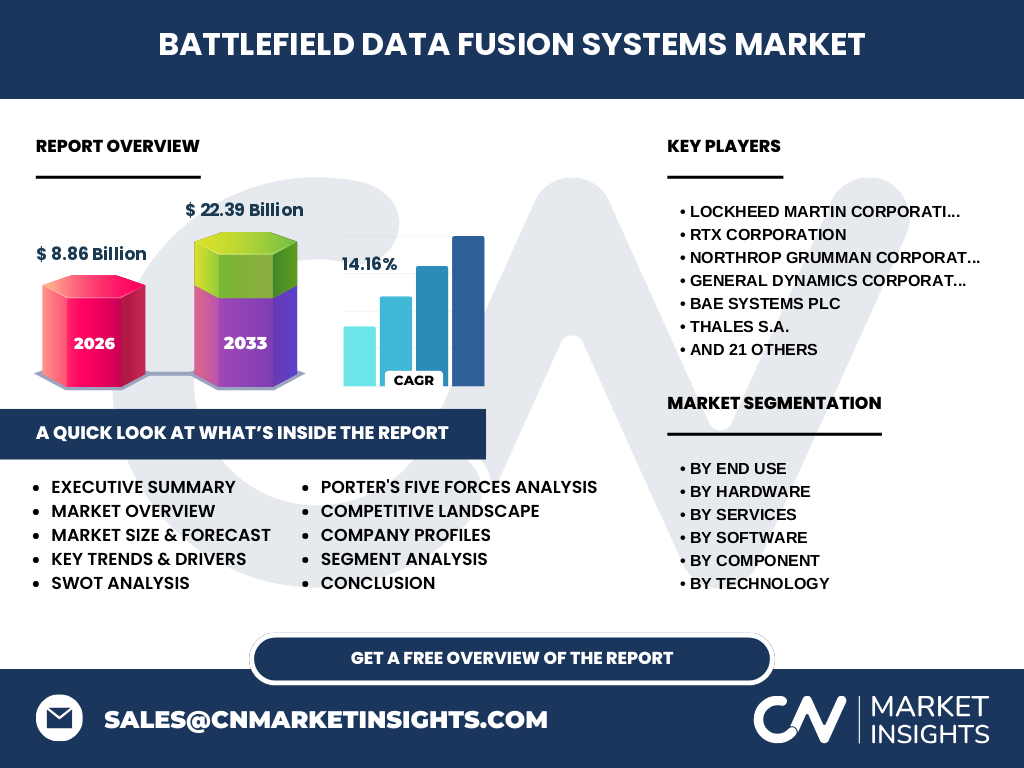
Market overview of the Battlefield Data Fusion Systems Market
Our analysis indicates that the Battlefield Data Fusion Systems Market is valued at $8.86 Billion in 2026. This domain encompasses multi-source information integration hardware, software, and services utilized by defense forces, homeland security agencies, and intelligence bodies to achieve operational superiority in complex, multi-domain modern warfare environments.
What are the core market drivers, restraints, challenges, and opportunities shaping the Battlefield Data Fusion Systems Market industry trends?
The market is driven by escalating geopolitical tensions and the exponential rise of edge computing, big data analytics, and artificial intelligence. However, stringent ITAR export controls, complex military certification hurdles, and high maintenance costs act as major restraints. Opportunities lie in integrating autonomous drone swarms and advanced electronic warfare nodes.
Emerging trends and growth patterns in the Battlefield Data Fusion Systems Market
A defining industry trend is the aggressive shift toward decentralized edge computing architectures. Defense primes are deploying AI-enabled software directly onto ruggedized hardware platforms to minimize latency during high-tempo intelligence, surveillance, and reconnaissance operations, ensuring uninterrupted target acquisition under degraded communication conditions.
COVID-19 impact analysis on the Battlefield Data Fusion Systems Market
The pandemic severely disrupted global microchip supply chains and raw material procurement, stalling defense hardware assembly lines. However, our research confirms a rapid post-pandemic recovery trajectory, accelerated by defense ministries prioritizing resilient, cloud-enabled command and control architectures to secure distributed operations.
Competitive benchmarking and strategic dynamics within the Battlefield Data Fusion Systems Market
Market concentration is high, dominated by aerospace and defense primes like Lockheed Martin Corporation, RTX Corporation, and Northrop Grumman Corporation. These legacy giants increasingly partner with agile innovators like Palantir Technologies Inc. and Anduril Industries Inc. to inject modern AI and machine learning software into legacy hardware.
Executive summary of the Battlefield Data Fusion Systems Market market size
Our comprehensive market analysis reveals that the Battlefield Data Fusion Systems Market will expand from $8.86 Billion in 2026 to $22.39 Billion by 2033, registering a robust CAGR of 14.16%. This growth is heavily underpinned by surging demand for AI-driven intelligence and automated target acquisition software.
Long-term market forecast and trajectory from 2027 to 2033
Driven by sustained defense modernization budgets across major allied nations, the market is poised for accelerated expansion. Between 2027 and 2033, the integration of Internet of Things sensor grids and automated visualization tools will propel cumulative sector revenues to reach $22.39 Billion by the end of the forecast period.
Segmentation analysis across hardware, software, services, and end-use categories
The market breaks down by End Use (Defense Forces, Homeland Security Agencies, Intelligence Agencies), Hardware (Sensors, Communication Devices, Data Processing Units, Display And Visualization Systems, Storage Devices), Services, Software (Data Integration, AI, Visualization, C2), Component, Technology (AI, Big Data, Edge Computing, IoT), Application (ISR, Target Acquisition, C2, Electronic Warfare), and Deployment Mode (On-Premises, Cloud).
Geographic distribution and regional performance in the Battlefield Data Fusion Systems Market
North America commands the largest market share, sustained by massive Department of Defense procurement allocations for Joint All-Domain Command and Control (JADC2) programs. Meanwhile, the Asia-Pacific region exhibits the fastest growth rate, fueled by escalating defense outlays, border security modernization, and strategic tech investments in nations like India and Japan.
In-depth regional review of procurement priorities and localized operational constraints
European nations, constrained by strict GDPR-compliant data sovereignty regulations and complex cross-border defense procurement frameworks, prioritize sovereign cloud deployments and interoperable C2 software. Meanwhile, Middle Eastern markets heavily demand turnkey sensor-to-shooter integration services and localized training solutions from primes like Elbit Systems Ltd. and Israel Aerospace Industries Ltd.
Strategic positioning of leading companies in the Battlefield Data Fusion Systems Market
Industry leaders employ distinct positioning strategies. Defense conglomerates like BAE Systems plc, Thales S.A., and Leonardo S.p.A. leverage deep domain expertise in avionics and naval combat systems. Conversely, software-first players like Palantir Technologies Inc. and Vannevar Labs Inc. focus on scalable data analytics and automated battlefield intelligence platforms.
Porter's Five Forces analysis of competitive intensity
The threat of new entrants is moderate, restricted by extreme capitalization requirements and strict military qualification standards. Bargaining power of buyers is high, given concentrated defense ministry budgets. Rivalry among established primes is intense, driving continuous R&D investment into proprietary AI algorithms and hardware miniaturization.
SWOT analysis evaluating industry positioning and structural viability
Strengths include advanced proprietary multi-sensor fusion algorithms and entrenched supplier relationships with government agencies. Weaknesses involve long, unpredictable sales cycles and vulnerability to supply chain shocks for rare earth materials. Opportunities lie in autonomous systems integration, while threats stem from sophisticated cyber-attacks targeting military networks.
Value chain analysis from raw materials to end-user deployment
The value chain starts with specialty semiconductor and raw material suppliers, progressing to hardware component manufacturers like Curtiss-Wright Defense Solutions. Middle-tier software developers and system integrators then fuse these elements into cohesive platforms before defense forces and intelligence agencies deploy the final solutions.
High-potential investment insights and strategic recommendations
Investors should target niche firms specializing in edge-native AI analytics and resilient cloud architecture. Companies capable of bridging legacy military hardware with modern machine learning software represent the highest-yield acquisition targets for major tier-one prime contractors aiming to future-proof their defense portfolios.
Conclusion and key takeaways for executive decision-makers
The Battlefield Data Fusion Systems Market offers exceptional growth, advancing at a 14.16% CAGR toward a $22.39 Billion valuation by 2033. Success in this sector hinges on mastering secure multi-domain data interoperability, leveraging artificial intelligence, and navigating stringent defense procurement and export compliance frameworks.
Research methodology used for baseline estimations and market triangulation
Our proprietary methodology combines rigorous bottom-up and top-down triangulations. We synthesize primary stakeholder interviews with senior defense officials, exhaustive analysis of defense budget filings, trade registry metrics, and secondary macroeconomic indicators to establish highly accurate baseline valuations and forecast models.
Scope of the report and coverage parameters
This research report covers global market dynamics across North America, Europe, Asia-Pacific, Latin America, and the Middle East & Africa. It evaluates hardware, software, services, and deployment modes through 2033, while excluding civil aviation and commercial maritime navigation data fusion systems from the primary scope.
Recent developments, strategic partnerships, and product launches
Recent market activity is highlighted by aggressive software acquisitions and joint ventures. Innovators like Anduril Industries Inc. and Rebellion Defense Inc. have secured lucrative contracts to deploy autonomous tactical software, while established contractors like CACI International Inc and Leidos Holdings Inc. continue expanding their C4ISR integration capabilities.