What is the market overview of the 503B Outsourcing Facilities Market?
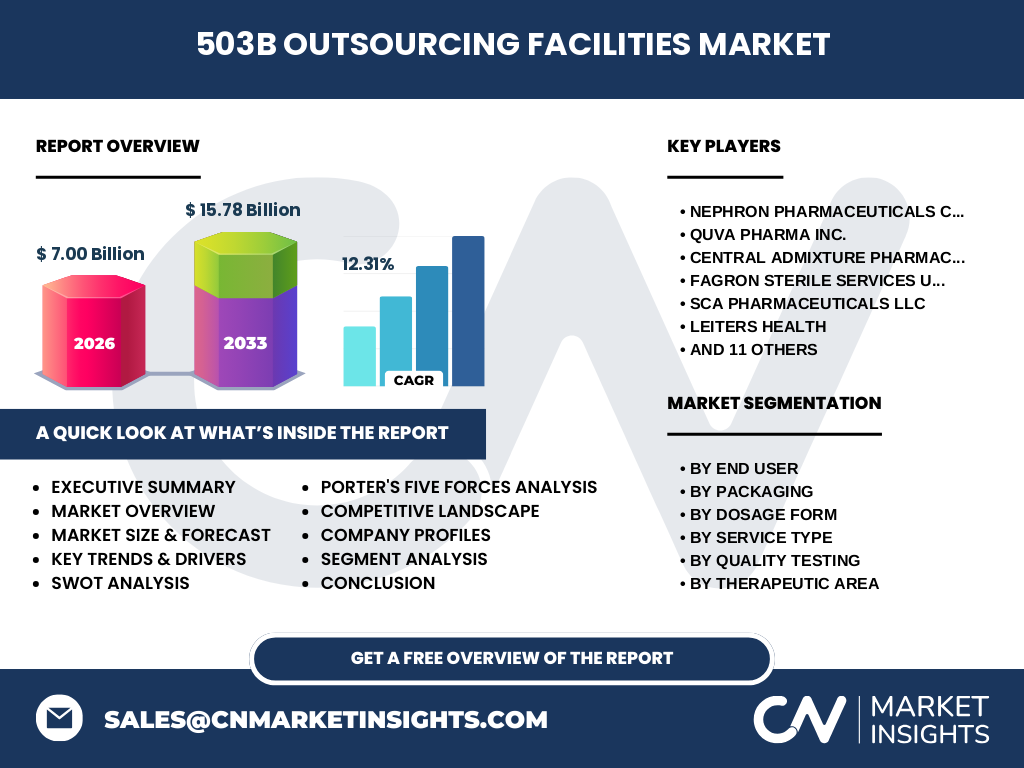
The 503B Outsourcing Facilities Market is valued at $7.00 Billion in 2026, establishing a critical regulated tier between traditional compounding pharmacies and major pharmaceutical manufacturers. These facilities compound sterile and non-sterile medications in bulk without individual patient prescriptions, addressing chronic national drug shortages and supplying acute-care hospitals with essential injectable preparations.
Key market drivers, restraints, challenges, and opportunities shaping the sector
Growth is propelled by severe hospital drug shortages and strict FDA quality mandates under Section 503B. Restraints include high capital expenditures required for Current Good Manufacturing Practice (cGMP) compliance. Opportunities thrive in expanding specialty therapeutic areas like oncology and pain management through advanced prefilled syringes and intravenous admixtures.
Emerging trends and growth patterns in the 503B Outsourcing Facilities Market
Industry trends demonstrate a decisive pivot toward ready-to-administer prefilled syringes and tamper-evident packaging to minimize medication errors in hospital operating rooms. Facilities are modernizing cleanroom technologies and upgrading sterility testing protocols to meet stringent regulatory scrutiny from federal health authorities.
How did COVID-19 impact the 503B Outsourcing Facilities Market and influence its recovery trajectory?
The pandemic exposed extreme vulnerabilities in global active pharmaceutical ingredient supply chains, causing unprecedented spikes in demand for critical care anesthetics and ventilator-associated medications. 503B facilities stepped in to bridge acute supply gaps, accelerating their long-term integration into hospital procurement frameworks and Group Purchasing Organizations.
Competitive benchmarking and strategic dynamics of major industry participants
The landscape features prominent players like Nephron Pharmaceuticals Corporation, QuVa Pharma Inc., and Central Admixture Pharmacy Services Inc. (CAPS) dominating cleanroom capacity. Competition centers on geographic footprint expansion, comprehensive product portfolios spanning sterile injectables to topical formulations, and rapid-response logistics capabilities.
Executive summary of key findings for the 503B Outsourcing Facilities Market
Our analysis projects the 503B Outsourcing Facilities Market to expand from $7.00 Billion in 2026 to $15.78 Billion by 2033 at a robust CAGR of 12.31%. This explosive trajectory reflects permanent shifts in hospital outsourcing habits, rising demand for specialized sterile compounding, and heightened regulatory barriers favoring well-capitalized cGMP facilities.
Market forecast trajectory from 2027 to 2033
Driven by compounding clinical adoption and recurring institutional supply contracts, market valuation will climb steadily to reach $15.78 Billion by 2033. The anticipated 12.31% CAGR underscores sustained capital inflows into advanced packaging lines, sterility testing laboratories, and dedicated cold-chain distribution networks.
Comprehensive segmentation analysis across end-user, packaging, and dosage forms
Segmentation spans multiple operational dimensions. End Users include hospitals, clinics, ambulatory surgical centers, and long-term care facilities. Packaging incorporates unit dose, blister, vial, syringe, and tamper-evident formats. Dosage Forms feature injectables, oral, topical, and ophthalmic formulations handled via sterile or non-sterile service types.
Regional market analysis and geographic performance distribution
Geographic performance is heavily skewed toward North America due to strict FDA oversight and well-established institutional healthcare procurement networks. Regional expansion increasingly relies on localized distribution channels, direct sales teams, and partnerships with major Group Purchasing Organizations to ensure reliable supply delivery.
In-depth regional review of the 503B Outsourcing Facilities Market
The United States represents the undisputed core of this market, supported by federal frameworks distinguishing 503B facilities from traditional pharmacies. Regional growth hotspots cluster around major healthcare hubs where dense networks of hospitals and ambulatory surgical centers demand continuous, validated supplies of critical care medications.
Strategic positioning of leading company profiles in the sector
Market leaders such as Fagron Sterile Services US, SCA Pharmaceuticals LLC, and Leiters Health leverage state-of-the-art manufacturing infrastructure to secure enterprise-wide hospital contracts. Concurrently, specialized innovators like Empower Pharmacy LLC and OSRX Inc. capture high-margin outpatient and specialty clinical segments.
Porter's Five Forces analysis of competitive intensity
Threat of new entrants remains moderate-to-low due to prohibitive cGMP compliance costs and rigorous FDA inspection hurdles. Bargaining power of buyers is tempered by chronic drug shortages that make reliable outsourcing partners indispensable, while rivalry among established 503B leaders focuses on quality compliance and delivery speed.
SWOT analysis evaluating strategic market position
Strengths include established cGMP manufacturing frameworks and deep hospital integration. Weaknesses involve high regulatory compliance costs. Opportunities lie in expanding ophthalmic and oncology compounding services. Threats stem from potential regulatory crackdowns and supply chain disruptions for raw chemical ingredients.
Value chain analysis from raw materials to end-users
The value chain initiates with active pharmaceutical ingredient sourcing, flows through highly regulated cGMP cleanrooms for sterile and non-sterile compounding, utilizes advanced vial and syringe packaging, and concludes via wholesale distributors and direct sales to end-users like hospitals and ambulatory surgical centers.
Investment insights and high-potential strategic growth areas
Investors should target facilities scaling advanced sterile compounding infrastructure, specifically dedicated lines for prefilled syringes and ophthalmic solutions. Companies integrating comprehensive quality testing—such as endotoxin, potency, and stability testing—offer superior risk-adjusted return profiles amid tightening regulatory enforcement.
Conclusion and key strategic takeaways for stakeholders
The 503B Outsourcing Facilities Market represents a high-growth frontier in pharmaceutical manufacturing, anchored by a projected 12.31% CAGR through 2033. Stakeholders must prioritize cGMP compliance, supply chain redundancy, and advanced product packaging to capture expanding institutional demand.
Research methodology for baseline estimates and data triangulation
Our baseline estimates are rigorously triangulated by combining federal trade registry data, primary stakeholder interviews with c-suite executives across major facilities, and secondary macroeconomic indicators. This multi-tiered research approach ensures highly accurate market sizing and verifiable growth forecasts.
Scope of the report, coverage parameters, and analytical limitations
This report covers the global 503B outsourcing landscape across designated end-user verticals, service types, packaging formats, and therapeutic areas from 2026 through 2033. Limitations include potential shifts in federal regulatory enforcement policies and unforeseen global macroeconomic shocks affecting raw material logistics.
Recent developments, facility expansions, and strategic industry moves
Recent market dynamism includes major capacity expansions by key players such as Wells Pharma of Houston LLC and Medivant Healthcare. Industry participants are actively forging strategic distribution agreements with Group Purchasing Organizations to secure long-term institutional market share and insulate against supply chain volatility.