Market overview of the Autonomous Naval Systems Market
The Autonomous Naval Systems Market represents a critical paradigm shift in maritime operations, valued at $6.82 Billion in 2026. This sector encompasses unmanned surface, underwater, and hybrid vessels designed for defense, commercial, and research applications, fundamentally transforming modern naval warfare and oceanographic exploration through advanced artificial intelligence and sensor integration.
Structural Growth Drivers and Market Restraints
Growth in the Autonomous Naval Systems Market is driven by rising geopolitical tensions demanding unmanned surveillance and mine countermeasures. However, stringent international maritime regulations and high cybersecurity vulnerabilities present notable restraints. Key opportunities lie in leveraging solar power and swarm technology to extend operational range and mission persistence across contested littoral waters.
Emerging trends and growth patterns in Autonomous Naval Systems Market
The industry is witnessing an accelerated shift toward swarm-enabled surface vessels and cross-domain hybrid vehicles capable of seamless air-surface-underwater transitions. Companies like Saronic and Saildrone are pioneering edge-computing architectures that allow autonomous systems to execute complex anti-submarine warfare and environmental monitoring tasks with minimal human intervention, redefining operational efficiency.
COVID-19 impact analysis and recovery trajectory
The pandemic initially disrupted global supply chains for critical sensors and rare-earth raw materials, temporarily stalling defense procurement cycles. Nevertheless, the Autonomous Naval Systems Market rebounded aggressively as navies prioritized contactless, remote-operated systems. This crisis catalyzed digital integration and accelerated remote-assisted crewed vessel adoption across major commercial shipping lanes.
Competitive Benchmarking and Strategic Dynamics
Market concentration is characterized by a mix of defense prime contractors and agile technology disruptors. General Dynamics Corporation, BAE Systems plc, and L3Harris Technologies Inc. leverage massive balance sheets for large-scale military integration, while innovators like Anduril Industries and XOCEAN capture market share through disruptive, cost-effective autonomous data collection and surface operations.
Executive summary of Autonomous Naval Systems Market analysis
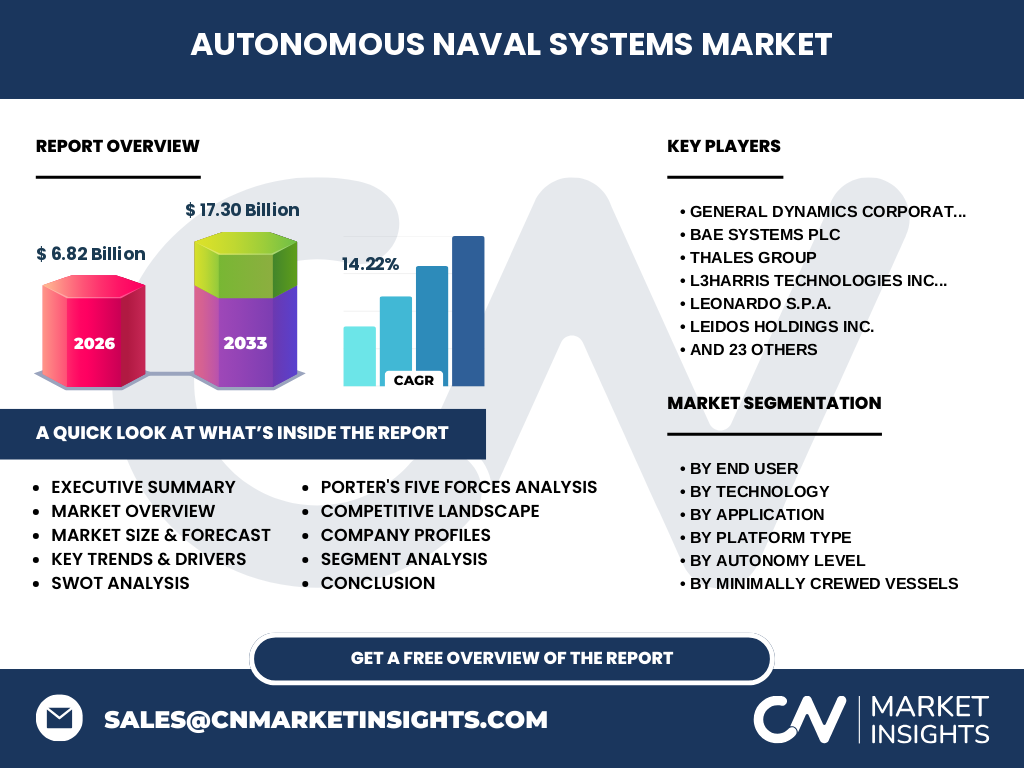
Our analysis indicates that the Autonomous Naval Systems Market is poised for explosive expansion, scaling from $6.82 Billion in 2026 to $17.30 Billion by 2033 at a robust 14.22% CAGR. Defense and military expenditures remain the primary catalyst, supported by rapid commercial adoption in hydrographic surveying and offshore energy infrastructure monitoring.
Long-term market forecast from 2027 to 2033
Driven by sustained naval modernization budgets and commercial autonomy mandates, the market will achieve a stellar 14.22% CAGR. Projections show revenues vaulting from the 2026 baseline to reach $17.30 Billion by 2033. This trajectory underscores a permanent transition toward unmanned underwater vehicles and optionally crewed surface platforms worldwide.
Segmentation analysis across core operational categories
The ecosystem is segmented by end-user, technology, application, platform type, and autonomy level. Defense and Military dominate end-use demand, while Unmanned Underwater Vehicles (UUVs) and Unmanned Surface Vehicles (USVs) anchor platform types. Technological investments heavily target Artificial Intelligence and advanced Sensor Systems to ensure reliable navigation and threat detection.
Regional market distribution and geographic performance
Geographic performance is heavily skewed toward North America and the Indo-Pacific, where naval fleets face complex territorial defense challenges. The Asia-Pacific region demonstrates the fastest growth rate, fueled by aggressive naval fleet expansions from regional powers investing in long-endurance underwater vehicles and coastal surveillance networks.
In-depth regional review of key maritime territories
North America leads in absolute market valuation due to massive R&D outlays by the U.S. Navy and key defense contractors. Meanwhile, European markets, championed by firms like Kongsberg Gruppen ASA and Saab AB, focus intensely on stringent environmental monitoring and Baltic Sea subsea critical infrastructure protection using advanced hydrographic platforms.
Company profiles and strategic positioning of market leaders
Industry leaders combine traditional defense engineering with cutting-edge software agility. Thales Group and Leonardo S.p.A. excel in sonar integration and combat management systems, whereas specialized players like Ocean Infinity Ltd. and Fugro N.V. dominate commercial data harvesting, utilizing remote-operated fleets to slash offshore operational carbon footprints.
Porter's Five Forces analysis of the competitive landscape
The threat of new entrants is moderate, constrained by high capital requirements and strict defense certification hurdles. Bargaining power of suppliers is high for specialized cryptographic and acoustic sensors. Competitive rivalry is intense, forcing established primes like Huntington Ingalls Industries Inc. to acquire agile autonomous drone startups.
SWOT analysis of the Autonomous Naval Systems industry
Key strengths include unprecedented operational reach and zero personnel risk in hazardous zones. Weaknesses involve complex data-link vulnerabilities and battery energy density limitations. Opportunities abound in offshore wind farm security, while threats include asymmetric cyber warfare targeting autonomous navigation algorithms.
Value chain analysis from raw materials to end-users
The value chain originates with raw material suppliers providing titanium, carbon composites, and rare-earth magnets for sonar actuators. Subsystem manufacturers then build AI modules and inertial navigation units before system integrators—such as Elbit Systems Ltd. and Israel Aerospace Industries—deliver turnkey vessels to navies and commercial clients.
High-potential investment insights and strategic recommendations
Investors should direct capital toward cross-domain hybrid vehicles and robust edge-AI communication encryption. Companies mastering long-duration power sources and swarm coordination algorithms will capture disproportionate market value as defense agencies increasingly favor distributed, attritable autonomous maritime swarms over monolithic platforms.
Conclusion and key takeaways for stakeholders
The Autonomous Naval Systems Market is transitioning from experimental prototyping to core naval doctrine, underlined by a projected 14.22% CAGR through 2033. Stakeholders must prioritize software adaptability, modular sensor payloads, and compliance with international maritime laws to secure long-term profitability in this booming sector.
Research methodology for baseline estimates and projections
Our rigorous research methodology triangulates data from multiple authoritative streams. We combine defense budget registries, direct primary stakeholder interviews with defense attachés and chief technology officers, and secondary macroeconomic indicators to build reliable econometric models forecasting the $17.30 Billion market endpoint by 2033.
Scope of the report and coverage parameters
This comprehensive report evaluates the global Autonomous Naval Systems Market across all major platform tiers, including USVs, UUVs, and hybrid systems. Coverage spans historical evaluations leading up to the $6.82 Billion valuation in 2026, extending through detailed forecasts to 2033, while explicitly omitting classified black-budget military programs outside verified public disclosures.
Recent developments, partnerships, and strategic product launches
Recent industry momentum is highlighted by strategic joint ventures and rapid prototyping contracts. Innovators like Exail Technologies and Sea-Kit International have recently secured landmark commercial and naval contracts for remote-operated mine clearance and offshore survey missions, validating the commercial viability of scalable maritime autonomy.