Market overview and structural significance of the Resistive Loss Type Absorbing Material Market
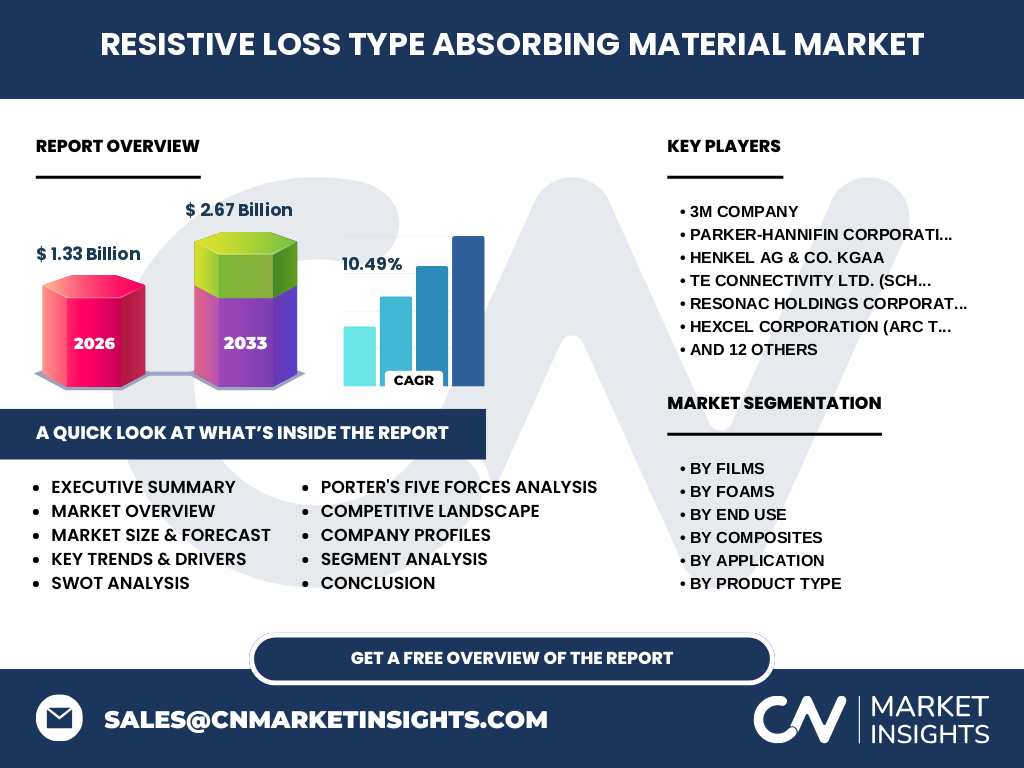
The Resistive Loss Type Absorbing Material Market represents a vital technical sector valued at $1.33 Billion in 2026. Our analysis indicates these advanced formulations are critical for mitigating electromagnetic interference and radar signatures across high-frequency electronics. Industry significance stems from stringent electromagnetic compatibility mandates governing modern commercial aviation and 5G infrastructure.
What primary catalysts and barriers are shaping the Resistive Loss Type Absorbing Material Market?
Structural growth is heavily driven by denser PCB layouts and millimeter-wave telecommunications expansion. Conversely, market constraints involve the high cost of specialized carbon-based and magnetic resistive hybrid raw materials. Supply chain bottlenecks around high-purity binders create logistical hurdles for tier-one manufacturers navigating international trade compliance.
Emerging Innovation Patterns in Resistive Loss Type Absorbing Material Market Industry Trends
The shift toward lightweight, flexible multi-layer absorbing films and hybrid composite matrices is redefining industry standards. Technical advancements prioritize broadband attenuation capabilities over narrow-band tuning, favoring firms possessing proprietary filler dispersion technologies capable of maintaining mechanical flexibility under extreme thermal stress.
How did the pandemic influence the post-crisis recovery trajectory of the Resistive Loss Type Absorbing Material Market?
Pandemic-induced supply chain disruptions temporarily delayed aerospace and defense procurement cycles. However, accelerated digital transformation and remote connectivity investments rapidly propelled post-crisis recovery, cementing a robust valuation baseline leading directly into our forecast window.
Competitive Benchmarking and Strategic Dynamics in the Resistive Loss Type Absorbing Material Market
Market concentration remains moderately high, with industry leaders like 3M Company, Parker-Hannifin Corporation (Chomerics Division), and TDK Corporation dominating through extensive patent portfolios. Strategic dynamics involve aggressive vertical integration and joint ventures aimed at securing proprietary nano-carbon raw material inputs.
Executive Summary of Key Analytical Findings
Our comprehensive research establishes that the market is poised for robust expansion, driven by relentless miniaturization in electronics. Key findings highlight that proprietary formulation capabilities and global distribution networks will dictate long-term market dominance among key industry participants.
Long-Term Market Forecast and Expansion Projections
The market is projected to expand from $2.67 Billion between 2027 and 2033, achieving a notable compound annual growth rate of 10.49%. This accelerated trajectory reflects burgeoning demand from autonomous vehicle sensor suites and defense modernization initiatives globally.
Detailed Segmentation Analysis Across Product and Material Categories
Segmentation spans diverse categories including films, foams, and composites. Specifically, film sub-segments feature Magnetic Loss Films and Conductive Polymer Films, while foam categories comprise Carbon Loaded Foams and Silicone Based Foams. Material types include Dielectric Loss Materials and Carbon Based Resistive Materials, each fulfilling specialized attenuation roles.
Geographic Distribution and Macro Regional Performance
Geographic performance is heavily anchored by heavy industrial output and advanced electronics manufacturing hubs across North America, Asia-Pacific, and Europe. Regional variances underscore the influence of localized automotive electrification initiatives and defense budget allocations on material consumption patterns.
In-Depth Regional Review of High-Growth Geographies
Asia-Pacific leads consumption volume due to dense electronics manufacturing clusters in Shenzhen, Taiwan, and South Korea, coupled with expanding regional aerospace initiatives. Meanwhile, North America prioritizes high-end defense applications, driven by strict military electromagnetic standards enforced by domestic regulatory bodies.
Strategic Positioning of Leading Enterprise Profiles
Industry giants such as Henkel AG & Co. KGaA, Rogers Corporation, and Saint-Gobain Performance Plastics leverage specialized chemical synthesis expertise. Meanwhile, firms like Hexcel Corporation (ARC Technologies) focus heavily on custom radar-absorbing structures for aerospace OEMs.
Porter's Five Forces Assessment of Competitive Intensity
The threat of new entrants remains low due to high intellectual property barriers and strict aerospace qualification hurdles. Bargaining power of suppliers is moderate, constrained by specialized raw material needs, while rivalry among established players is intense regarding thermal and electrical performance metrics.
SWOT Analysis of the Global Ecosystem
Strengths include high-performance dissipation properties and established supplier relationships. Weaknesses involve high production costs for specialized elastomers. Opportunities lie in expanding EV charging infrastructure, while threats stem from raw material price volatility affecting gross margins.
Value Chain Analysis from Raw Inputs to End-User Delivery
The value chain initiates with base resin, carbon allotrope, and magnetic powder synthesis. Intermediate processing involves compounding and precision coating. Finished goods flow through direct OEM supply, industrial distributors, and online B2B platforms toward electronics, defense, and automotive end-users.
High-Potential Investment Insights and Strategic Recommendations
Investors should target early-stage innovators specializing in hybrid filler foams and lightweight shielding tapes. Strategic M&A activity is expected to center around acquiring proprietary resin formulation patents and expanding proprietary manufacturing footprints in emerging Asian industrial corridors.
Conclusion and Definitive Industry Takeaways
The sector presents compelling long-term upside underpinned by a 10.49% CAGR through 2033. Success will disproportionately reward enterprises capable of scaling advanced composite manufacturing while meeting increasingly stringent aerospace and telecommunications regulatory mandates.
Proprietary Research Methodology and Data Triangulation
Our baseline estimates are rigorously triangulated by combining customs trade registry data, primary qualitative interviews with C-level engineering executives, and secondary macroeconomic indicators from global semiconductor and defense manufacturing associations.
Scope of the Report and Analytical Parameters
This report covers global market sizing, volumetric demand metrics, and competitive landscapes from 2027 through 2033. Analysis specifically evaluates commercial and military applications, excluding consumer-grade passive components that lack certified electromagnetic loss ratings.
Recent Strategic Developments, Partnerships, and Product Launches
Recent industry momentum features major capacity expansions by Würth Elektronik GmbH & Co. KG and strategic joint ventures by Resonac Holdings Corporation focused on next-generation EV thermal-electromagnetic interface pads, reflecting ongoing demand for integrated shielding solutions.