What is the scope and industry significance of the Air Compression Recovery Boots Market?
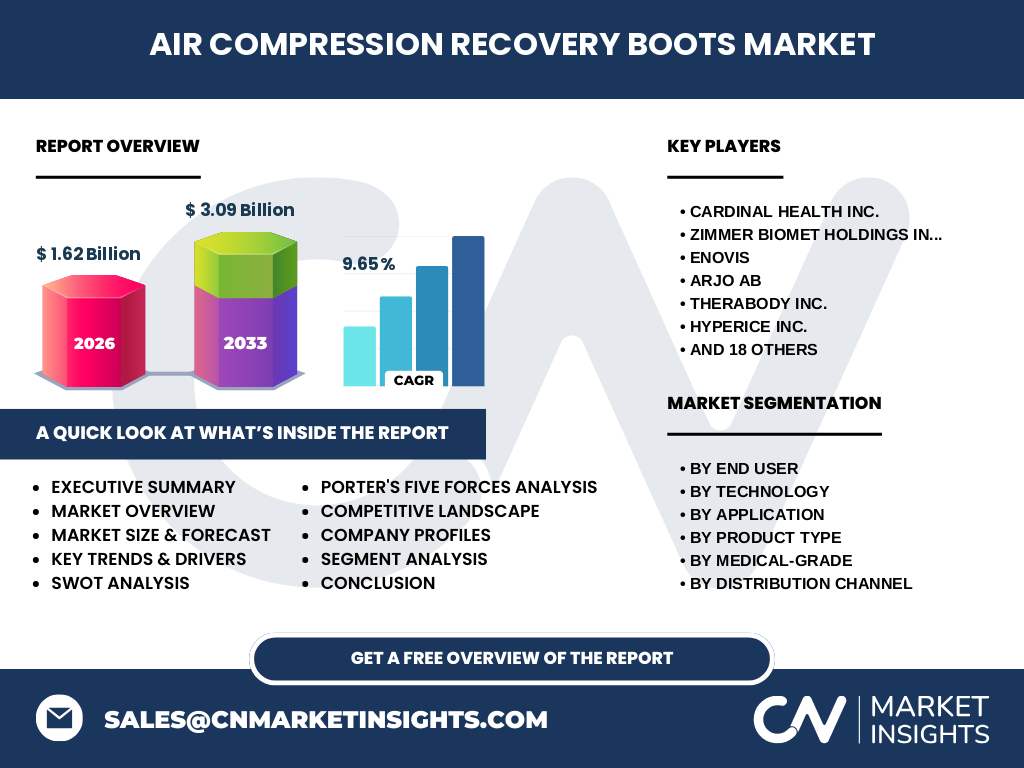
Our analysis indicates the Air Compression Recovery Boots Market values at $1.62 Billion in 2026, driven by rising clinical and athletic demand. This sector encompasses medical-grade and wellness-grade pneumatic compression devices used for lymphatic drainage, deep vein thrombosis prevention, and enhanced muscular lactate clearance across global healthcare and fitness ecosystems.
Key market drivers, restraints, challenges, and opportunities shaping Air Compression Recovery Boots Market
Growth is accelerated by rising consumer health spending and advanced six-chamber sequential systems. However, strict FDA and CE regulatory compliance creates market entry barriers. Supply chain bottlenecks for medical-grade pneumatic valves and TPU fabrics challenge manufacturers, while expanding remote patient monitoring offers lucrative global opportunities.
Emerging trends and growth patterns in Air Compression Recovery Boots Market
The shift toward smart, app-connected recovery systems dominates current industry trends. Consumers increasingly demand portable, travel-friendly wellness-grade boots featuring customizable pressure gradients. Brands like Hyperice and Therabody lead this wave by integrating Bluetooth pressure adjustments and biometric feedback into home-use and athletic recovery units.
COVID-19 impact analysis and recovery trajectory
The pandemic initially disrupted supply chains relying on Asian manufacturing hubs for medical textiles and micro-pumps. Conversely, it catalyzed an unprecedented boom in home wellness systems and telehealth physical therapy. Post-COVID recovery trajectories show accelerated adoption of direct-to-consumer channels as remote athletic training and home-based rehabilitation became permanent lifestyle fixtures.
Competitive landscape and strategic dynamics
Market concentration features a split between established medical giants like Zimmer Biomet and agile consumer wellness disruptors like Rapid Reboot. Strategic dynamics center on patent portfolios covering overlapping chamber overlap technology, aggressive digital marketing, and direct-to-consumer e-commerce scaling to capture both clinical rehabilitation and high-end athletic segments.
Executive summary of key findings
The Air Compression Recovery Boots Market is poised for substantial expansion, registering a robust 9.65% CAGR to reach $3.09 Billion by 2033. Convergence of clinical therapy efficacy with consumer wellness adoption drives this trajectory, requiring manufacturers to balance FDA compliance with sleek, consumer-friendly app-enabled designs.
Market forecast from 2027 to 2033
Based on our research, the market will scale from its 2026 baseline to $3.09 Billion by 2033 at a 9.65% CAGR. Accelerated compound growth stems from aging demographics requiring venous disorder management alongside explosive expansion in professional sports and marathon recovery ecosystems.
Segmentation analysis across end-users, technology, and application
Segmentation breaks down by end-user (Wellness Facilities, Home Users, Sports Centers, Hospitals), technology (Three, Four, Six-Chamber, Sequential, Intermittent), application (Venous Disorder, Post-Operative, Sports Recovery, Wellness), product type (Medical vs. Wellness-grade), and distribution channel (Online, Offline, Direct). Six-chamber sequential systems dominate high-end clinical and athletic rehabilitation settings.
Regional market distribution and performance
North America leads global revenue share owing to high healthcare expenditures and dense professional sports adoption. Meanwhile, Asia-Pacific represents the fastest-growing regional market, propelled by expanding disposable incomes, rising health awareness in urban centers, and localized manufacturing hubs in China and South Korea.
In-depth regional review of key markets
North America benefits from entrenched insurance reimbursement pathways for medical-grade lymphedema therapy systems. Europe demonstrates steady growth governed by stringent medical device regulations (MDR). Asia-Pacific displays high-velocity adoption of consumer wellness-grade boots, driven by direct-to-consumer e-commerce proliferation and burgeoning fitness cultures in Japan, China, and Australia.
Company profiles and strategic positioning
Industry participants exhibit diverse strategic focus areas. Cardinal Health and Arjo AB anchor the clinical lymphedema and post-surgical sectors. Meanwhile, Therabody, Hyperice, and Air Relax dominate consumer athletic recovery through sleek branding, influencer partnerships, and intuitive portable interfaces.
Porter's Five Forces analysis of the industry
Rivalry is intense among consumer wellness brands, driving continuous product innovation. Supplier power remains moderate due to specialized TPU and micro-pump components. Threat of substitutes is low given the unique physiological efficacy of pneumatic compression, while barrier to entry is high for medical-grade clearances but low for wellness-grade entrants.
SWOT analysis of the sector
Strengths include proven physiological efficacy for lactate clearance and edema reduction. Weaknesses involve high price points for premium systems. Opportunities lie in emerging corporate wellness programs and travel recovery niches. Threats encompass regulatory crackdowns on unverified medical claims by wellness brands and counterfeit online competitors.
Value chain analysis from raw materials to end-users
The value chain starts with raw material sourcing for medical-grade TPU fabrics, micro-compressors, and electronic control boards. Mid-stream assembly occurs primarily in specialized manufacturing facilities across East Asia and North America. Downstream distribution flows through hospitals, specialty clinics, wellness facilities, and direct-to-consumer e-commerce platforms.
Investment insights and strategic recommendations
Investors should target manufacturers developing hybrid medical-wellness systems that bridge clinical rehabilitation and home use. Strategic M&A activity is expected as major medical device conglomerates seek to acquire direct-to-consumer wellness brands to capture high-margin lifestyle fitness demographics.
Conclusion and key takeaways
The Air Compression Recovery Boots Market offers compelling growth backed by a 9.65% CAGR toward $3.09 Billion by 2033. Success in this landscape requires navigating complex regulatory frameworks while capitalizing on consumer demand for portable, app-driven athletic and wellness recovery technology.
Research methodology and data triangulation
Our baseline estimates are triangulated by synthesizing primary stakeholder interviews with key opinion leaders, sports medicine physicians, and manufacturing executives. This primary research is cross-referenced with secondary trade registry data, customs import-export logs, and macroeconomic healthcare expenditure indicators to ensure robust market sizing.
Scope of the report and coverage parameters
This report evaluates the global Air Compression Recovery Boots Market across four major geographic regions, six core segmentation pillars, and historical data from 2024 through a forecast horizon of 2033. Excluded from this scope are passive compression garments and static compression stockings lacking pneumatic pump mechanisms.
Recent developments and strategic moves
Recent industry momentum includes major product launches featuring ultra-quiet, cordless pneumatic pumps by brands like Hyperice and Therabody. Strategic partnerships between wellness boot manufacturers and professional sports leagues have accelerated mainstream brand visibility, while clinical players focus on securing expanded insurance reimbursement codes.