Market overview and structural significance of the Open-Source Intelligence (OSINT) Fusion For Defense Intelligence Market
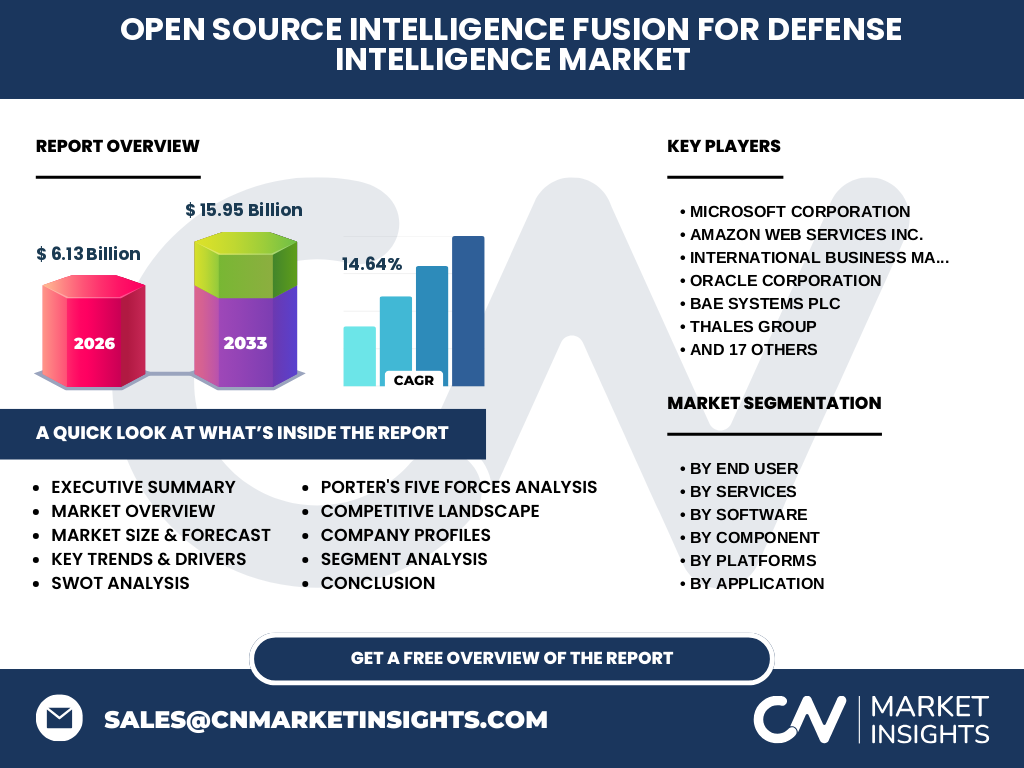
Our analysis indicates that the Open-Source Intelligence (OSINT) Fusion For Defense Intelligence Market represents a critical paradigm shift in modern military operations, valued at $6.13 Billion in 2026. This sector encompasses the systematic integration of publicly available information into classified workflows, leveraging advanced artificial intelligence and knowledge graph based fusion engines to support intelligence agencies and defense contractors like Palantir Technologies Inc. and RTX Corporation in maintaining tactical superiority.
Structural Growth Drivers and Market Restraints
The market is propelled by exponential data proliferation across social platforms and dark web repositories, though restrained by stringent regulatory compliance frameworks such as GDPR and strict data sovereignty laws. Geospatial analysis software and threat intelligence software adoption is surging as agencies counter asymmetric warfare. Logistical hurdles involve managing petabytes of unstructured data while ensuring zero-latency edge deployment for forward units operating under strict bandwidth constraints.
Emerging Trends in Open-Source Intelligence (OSINT) Fusion For Defense Intelligence Market Industry Trends
The shift toward Artificial Intelligence Driven Platforms and computer vision systems defines current Open-Source Intelligence (OSINT) Fusion For Defense Intelligence Market industry trends. Defense organizations increasingly rely on automated sentiment tracking and predictive link analysis to neutralize border security threats before kinetic engagement occurs. Innovators like Babel Street Inc. and BlackSky Technology Inc. are leading the charge in real-time multi-INT correlation.
COVID-19 Impact Analysis and Market Resilience
The pandemic accelerated digital transformation across defense ecosystems, forcing a rapid migration toward cloud-based platforms and remote collaborative intelligence environments. Despite supply chain disruptions impacting hardware procurement for edge deployments, demand for remote border security and automated surveillance solutions surged. Agencies partnered with tech giants like Microsoft Corporation and Amazon Web Services Inc. to secure distributed intelligence workflows during global lockdowns.
Competitive Benchmarking and Market Concentration
The Open-Source Intelligence (OSINT) Fusion For Defense Intelligence Market analysis reveals a moderately consolidated landscape dominated by defense primes and agile pure-play software vendors. Companies like BAE Systems plc, Thales Group, and CACI International Inc. leverage massive government contracting networks, whereas specialized players like Maltego Technologies GmbH and ShadowDragon LLC carve out niches by providing granular link analysis and social media monitoring software.
Executive Summary of Key Analytical Findings
Driven by compounding geopolitical instability and exponential digital growth, the Open-Source Intelligence (OSINT) Fusion For Defense Intelligence Market is projected to reach $15.95 Billion by 2033, expanding at a robust 14.64% CAGR from 2027. Strategic investments in natural language processing tools and hybrid cloud architectures will dictate market leadership, offering lucrative entry points for defense technology investors navigating complex procurement cycles.
Long-Term Market Forecast from 2027 to 2033
Our econometric forecasting models project stellar expansion, scaling the market from its 2026 baseline of $6.13 Billion to an impressive $15.95 Billion by the conclusion of 2033. This trajectory reflects a steady 14.64% CAGR, fueled by widespread adoption of automated data aggregation software and real-time intelligence platforms across both military and homeland security end-user segments.
Segmentation Analysis Across End Users, Software, and Services
Market segmentation spans multiple dimensions critical for strategic planning:
- End User: Military, Homeland Security, Law Enforcement, Intelligence Agencies.
- Software: Data Aggregation, Geospatial Analysis, Social Media Monitoring, Threat Intelligence.
- Services: Integration, Consulting, Managed Services, Training.
- Deployment: On-Premises, Cloud-Based, Hybrid, Edge Systems.
Regional Market Distribution and Comparative Performance
Geographic performance highlights North America as the dominant revenue generator, bolstered by heavy defense budgets and close integration between the Pentagon and innovators like Palantir Technologies Inc. and Leidos Holdings Inc. Meanwhile, the Asia-Pacific region exhibits the fastest growth rate, driven by escalating maritime border security disputes and rapid investments in artificial intelligence or machine learning platforms by regional defense forces.
In-Depth Regional Review of High-Growth Geographies
European markets are heavily shaped by cross-border regulatory compliance and collaborative intelligence mandates under EU frameworks. Nations in this region prioritize secure hybrid architectures and multilingual text analytics software to monitor regional instability. Concurrently, Middle Eastern defense agencies are aggressively procuring advanced image and video analysis software and border security surveillance platforms to fortify critical infrastructure against asymmetric threats.
Strategic Positioning of Leading Company Profiles
Industry titans such as Northrop Grumman Corporation, RTX Corporation, and Lockheed Martin integrate comprehensive OSINT suites into broader command-and-control frameworks. Simultaneously, specialized firms like Flashpoint Intelligence Inc., Strider Technologies Inc., and Semantic Visions sro focus on proprietary threat intelligence software and risk analytics, serving specialized intelligence agencies that demand turnkey data fusion capabilities.
Porter's Five Forces Analysis of the Competitive Landscape
Bargaining power of buyers remains moderate to high, as defense procurement agencies demand bespoke customization and strict security clearances. Threat of new entrants is constrained by high switching costs, stringent military-grade accreditation, and the complex intellectual property required for advanced knowledge graph based fusion engines. Rivalry among established defense contractors and agile analytics software providers ensures continuous innovation cycles.
SWOT Analysis of the Global OSINT Fusion Sector
Strengths include unmatched predictive threat modeling and rapid data aggregation capabilities. Weaknesses stem from vulnerabilities in processing unstructured multi-language social feeds. Opportunities abound in expanding edge-computed surveillance for remote military outposts. Threats involve evolving data privacy legislations and sophisticated cyber-attacks targeting centralized intelligence repositories maintained by contractors like CACI International Inc. and General Dynamics.
Value Chain Analysis from Raw Data to End-User Intelligence
The value flow initiates with raw unstructured data harvested from public web scrapers, IoT sensors, and satellite constellations operated by firms like Planet Labs PBC. This data flows through processing layers involving natural language processing and computer vision systems before being synthesized into actionable intelligence reporting software for end-users in military and law enforcement command centers.
Strategic Investment Insights and High-Potential Areas
Investors should target early-stage developers specializing in edge-deployed AI architectures and automated data visualization software. As defense budgets increasingly prioritize real-time tactical awareness, companies offering seamless hybrid platform integration and robust compliance with international data protection standards present exceptional acquisition and venture capital opportunities.
Conclusion and Strategic Takeaways for Market Entrants
The transformation of public data into classified operational advantage is no longer optional for modern defense forces. With market valuation soaring toward $15.95 Billion, success hinges on delivering modular, highly secure, and AI-driven fusion platforms that integrate smoothly with legacy military infrastructure while maintaining compliance with stringent geopolitical mandates.
Research Methodology and Baseline Estimation Triangulation
Our baseline estimates are rigorously triangulated by synthesizing proprietary trade registry data, primary stakeholder interviews with chief technology officers across defense primes, and secondary macroeconomic indicators. We cross-reference defense budget allocations across NATO and allied nations with public earnings reports of key market participants to ensure absolute financial accuracy.
Scope of the Report and Operational Parameters
This report covers global deployment trends, software categorization, and service models across military, homeland security, and intelligence sectors from 2026 through 2033. Excluded from this scope are purely commercial consumer intelligence applications and unencrypted social listening tools that lack defense-grade security protocols or tactical interoperability features.
Recent Industry Developments, Partnerships, and Product Launches
Recent market dynamism features aggressive strategic acquisitions and defense contract awards, such as Palantir Technologies Inc. securing expanded intelligence fusion deals and Planet Labs PBC enhancing its geospatial constellation integration. Furthermore, firms like I-TRACING and FTI Consulting Inc. have formed strategic alliances to bolster managed OSINT security services for critical infrastructure protection.