What is the market overview and scope of the Anteroom Containment Systems Market?
Our analysis indicates the Anteroom Containment Systems Market values at 1.50 Billion in 2026. This ecosystem encompasses specialized physical barriers, modular isolation chambers, and pressure-controlled airlocks utilized across sterile processing and bio-containment zones. These systems ensure uninterrupted particulate control when personnel transition between cleanroom grades, complying strictly with ISO 14644 and FDA aseptic processing guidelines.
Structural Growth Drivers and Market Restraints
The Anteroom Containment Systems Market is propelled by strict biosafety regulations and surging demand for targeted biological therapies. Key growth drivers include escalating investments in advanced viral vector manufacturing and containment upgrades. Conversely, high capital expenditure requirements for cleanroom infrastructure and stringent validation protocols act as notable market restraints, challenging smaller research facilities.
Emerging Trends Shaping the Industry
Industry trends highlight a massive pivot toward rapid deployment and flexibility. Facilities increasingly adopt cleanroom compatible modular anterooms and foldable portable anterooms to minimize facility downtime during retrofits. Manufacturers like Modular Cleanrooms Inc. and HEPACART Inc. lead this shift by providing mobile framing solutions that maintain negative or positive pressure differentials seamlessly.
COVID-19 Impact Analysis and Recovery Trajectory
The pandemic dramatically accelerated adoption across healthcare facilities and vaccine production plants. Demand surged for rapid containment setups, prompting suppliers to scale production of mobile and modular units. Our research shows the post-pandemic recovery trajectory stabilized supply chains while embedding permanent biosecurity protocols, directly supporting the projected market expansion through 2033.
Competitive Landscape and Strategic Dynamics
Competitive benchmarking reveals a fragmented yet highly specialized marketplace. Market leaders such as Lindner Group KG, Esco Micro Pte Ltd., and Plascore Inc. dominate through turnkey architectural cleanroom solutions and proprietary wall panel engineering. Meanwhile, firms like STARC Systems Inc. focus heavily on healthcare renovation containment, securing a distinct competitive advantage in hospital infrastructure.
Executive Summary: High-Level Synthesis
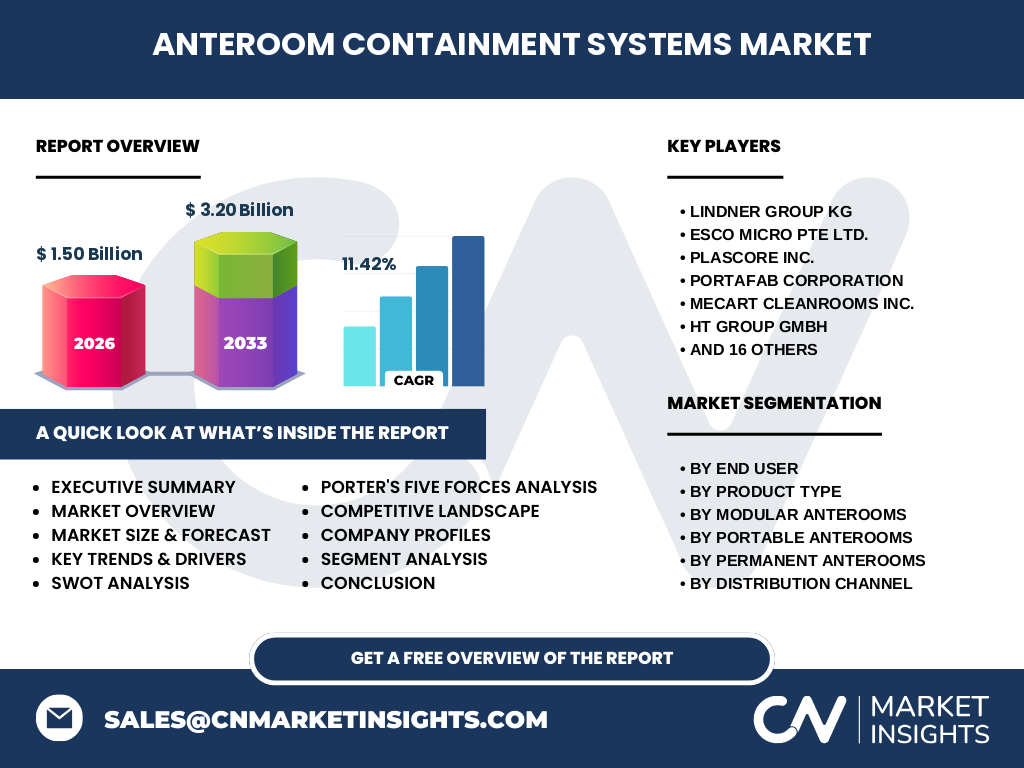
The Anteroom Containment Systems Market is poised for exceptional expansion, registering a robust 11.42% CAGR from 2027 to 2033. Our data projects the market valuation to surge from 1.50 Billion in 2026 to 3.20 Billion by 2033. Strategic investments in modular and portable configurations will capture the lion's share of this unprecedented fiscal growth.
Market Forecast from 2027 to 2033
Driven by compounding biosafety investments, the Anteroom Containment Systems Market industry trends forecast steady acceleration. Starting from its 2026 baseline of 1.50 Billion, the market will achieve an impressive valuation of 3.20 Billion by 2033. This trajectory reflects a sustained 11.42% CAGR, fueled by heightened containment mandates in pharmaceutical manufacturing.
Segmentation Analysis Across Key Categories
The market divides by End User into Healthcare Facilities, Research Institutes, Pharmaceutical Companies, and Other End Users. By Product Type, it spans Permanent Anterooms, Portable Anterooms, and Modular Anterooms. Modular units feature customizable, prefabricated, expandable, and cleanroom-compatible variants. Portable types include foldable, mobile frame, rapid deployment, and lightweight options, while permanent structures feature fixed wall, hard panel, hospital grade, and cleanroom designs.
Regional Market Analysis and Geographic Distribution
Geographic performance highlights North America and Europe as dominant revenue contributors due to stringent FDA and EMA containment guidelines. Asia-Pacific exhibits the fastest regional growth rate, propelled by massive biopharmaceutical facility investments in South Korea, Singapore, and China. Direct sales and specialized distributors serve as the primary distribution channels across these core geographies.
In-Depth Regional Review of Core Markets
North America leads adoption, driven by stringent USP <797> and USP <800> pharmacy compounding compliance. European markets prioritize energy-efficient cleanroom integration, leveraging local innovators like ABN Cleanroom Technology B.V. and HT Group GmbH. Concurrently, Asia-Pacific accelerates infrastructure builds, creating high-demand zones for companies like Terra Universal Inc. and PortaFab Corporation.
Company Profiles and Strategic Positioning
Leading industry participants secure their standing through distinct engineering capabilities. Mecart Cleanrooms Inc. and Clean Rooms International Inc. focus on high-durability permanent installations, whereas Abatement Technologies Inc. and Temporary Wall Systems LLC specialize in agile, temporary containment. Their strategic moves emphasize rapid installation without sacrificing particulate filtration efficacy.
Porter's Five Forces Analysis of Competitive Intensity
Industry rivalry is moderately high, driven by technological differentiation in modular sealing mechanisms. Bargaining power of buyers remains moderate due to specialized customization needs in pharmaceutical labs. Threat of substitutes stays low because strict ISO containment certifications preclude standard drywall alternatives, cementing the defensibility of established containment manufacturers.
SWOT Analysis of the Anteroom Containment Systems Market
Strengths include high regulatory compliance and advanced modular engineering. Weaknesses involve high initial capital expenditure. Opportunities emerge from expanding cell and gene therapy production lines globally. Threats stem from raw material price volatility for aluminum and high-grade composite panels utilized by fabricators like Allied Modular Building Systems Inc.
Value Chain Analysis from Raw Materials to End-Users
The value chain begins with raw material sourcing—primarily antimicrobial coatings, anodized aluminum frames, and HEPA filtration media. Tier-1 manufacturers process these components into prefabricated or modular systems. Distribution occurs via direct sales, specialized distributors, and online channels, ultimately delivering turnkey containment solutions to pharmaceutical plants and hospital surgical suites.
Investment Insights and High-Potential Areas
High-potential investment pockets center on cleanroom compatible modular anterooms and rapid deployment mobile units. Venture capital and strategic acquirers should target innovators providing IoT-enabled pressure monitoring within their containment structures. Companies capable of reducing installation downtime for active healthcare facilities will capture superior valuation multiples through 2033.
Conclusion and Key Takeaways
The Anteroom Containment Systems Market represents a high-growth, technically resilient sector anchored by strict biosecurity demands. Surging from 1.50 Billion in 2026 to 3.20 Billion by 2033 at an 11.42% CAGR, the industry rewards technological agility, particularly in modular and portable engineering disciplines.
Research Methodology and Baseline Triangulation
Our analysis builds upon rigorous primary stakeholder interviews with chief compliance officers, cleanroom architects, and procurement heads across pharmaceutical firms. We triangulate these primary insights with trade registry data, customs import-export logs for high-efficiency filtration components, and secondary macroeconomic indicators to establish reliable 2026 baseline estimates and forward-looking forecasts.
Scope of the Report and Coverage Parameters
This report covers global deployment parameters of anteroom containment systems across healthcare, research, and pharmaceutical sectors. Limitations include exclusion of standard commercial HVAC installations that lack dedicated pressure-controlled airlock containment capabilities. Geographic scope comprehensively spans North America, Europe, Asia-Pacific, Latin America, and the Middle East and Africa.
Recent Developments in the Industry
Recent market activities feature aggressive product launches focusing on tool-less assembly and smart pressure monitoring. Companies such as EZee Hoarding Inc. and Imperial Privacy Systems have expanded their modular cleanroom portfolios through strategic regional distribution partnerships, aiming to capture rising demand in ambulatory surgical centers and academic research laboratories.