What is the scope and industry significance of the Live Biotherapeutics Market?
Our analysis indicates that the Live Biotherapeutics Market represents a transformative paradigm in modern pharmacology, focusing on live microorganisms to treat specific diseases. With a baseline valuation of 113.01 Billion in 2026, this sector redefines traditional drug development by moving away from small molecules toward complex microbial consortia and genetically engineered strains regulated strictly by bodies like the US FDA and EMA.
Key market drivers, restraints, challenges, and opportunities shaping the Live Biotherapeutics Market
Growth is heavily propelled by rising clinical trials in microbiome modulation and increasing investments in Defined Bacterial Consortium Therapeutics. However, stringent cold-chain logistics and complex manufacturing scaling act as primary restraints. Industry participants like Seres Therapeutics Inc. and Vedanta Biosciences Inc. are capitalizing on oncology supportive care and gastrointestinal disorders to capture immense commercial upside.
Emerging trends and growth patterns in Live Biotherapeutics Market
The shift toward Synthetic Biology Based Therapeutics and precision microbiome consortia marks a vital evolution from broad-spectrum probiotics to targeted, mechanism-driven drugs. Based on our research, companies are increasingly utilizing Clustered Regularly Interspaced Short Palindromic Repeats Engineered Microbial Therapeutics to enhance target delivery, optimizing colonization persistence within the human gastrointestinal tract.
How did the COVID-19 pandemic impact the Live Biotherapeutics Market and what is the recovery trajectory?
The pandemic initially disrupted clinical trial recruitment and strained raw material procurement for lyophilized fecal microbiota products. Despite these headwinds, the sector demonstrated robust recovery as regulatory agencies streamlined virtual oversight frameworks. Ferring Pharmaceuticals SA and Rebiotix Inc. successfully navigated supply chain bottlenecks, accelerating the commercialization of standardized stool-derived therapeutics for recurrent infections.
Competitive landscape: major players, market concentration, and strategic dynamics
The competitive ecosystem is characterized by strategic consolidation and aggressive patent acquisitions by frontrunners like MaaT Pharma SA, EnteroBiotix Limited, and BiomX Inc. Market concentration is moderate-to-high in clinical-stage assets, where smaller innovators often partner with global pharma giants to fund expensive Phase III trials in autoimmune and inflammatory diseases.
Executive summary of the Live Biotherapeutics Market
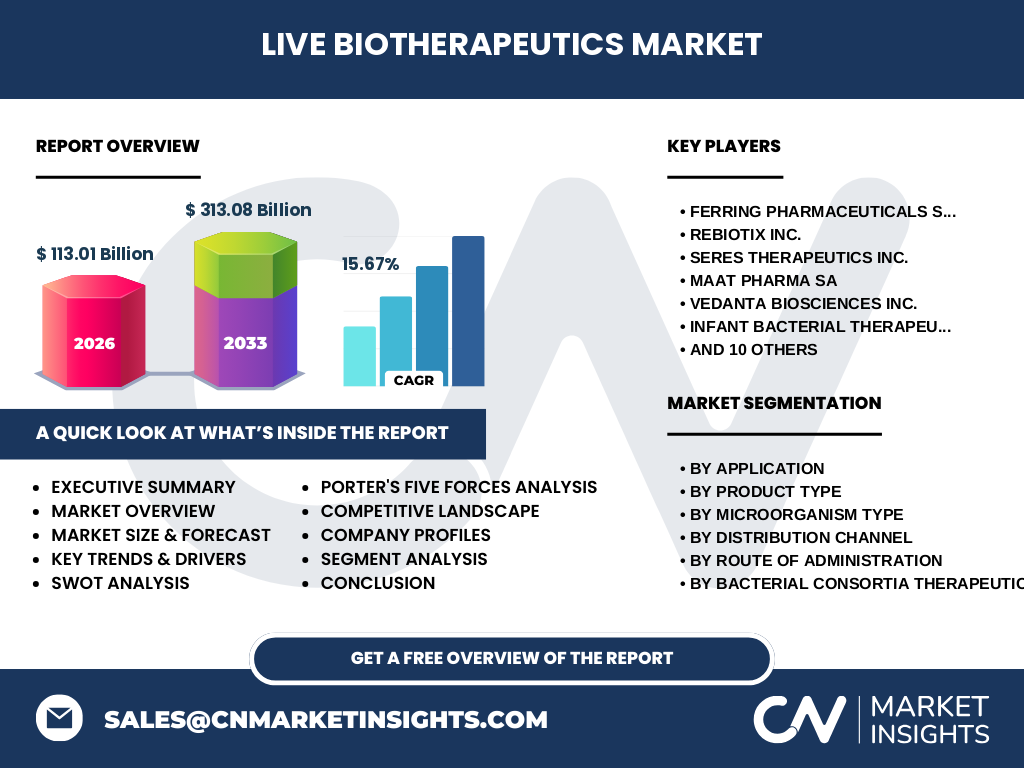
Valued at 113.01 Billion in 2026, the Live Biotherapeutics Market is poised for explosive expansion, projected to reach 313.08 Billion by 2033 at a CAGR of 15.67%. This robust trajectory reflects surging demand for innovative microbiome therapies across hospital and retail channels, driven by breakthroughs in bacterial consortia and genetically engineered live biotherapeutics.
Market forecast: projected growth from 2027 to 2033
The data suggests the market will scale from its 2026 baseline of 113.01 Billion to an impressive 313.08 Billion by 2033, expanding at a compound annual growth rate of 15.67%. This sustained momentum is underpinned by commercial approvals in Defined Bacterial Consortium Therapeutics and rising patient adoption of oral and rectal administration routes.
Segmentation analysis across product types, applications, and delivery channels
Segmentation spans multiple dimensions: by application (including Gastrointestinal Disorders and Oncology Supportive Care), product type (ranging from Single Strain Live Biotherapeutics to Fecal Microbiota Based Therapeutics), and microorganism type (bacteria, yeast, and viral phage). Distribution heavily relies on hospital pharmacies and specialized online channels, favoring cold-chain proficient logistics providers.
Regional market analysis and geographic distribution performance
Geographic performance highlights North America as the dominant revenue generator, bolstered by progressive FDA frameworks supporting microbiome drug applications. Meanwhile, Europe exhibits strong growth driven by initiatives from players like MRM Health NV and Microbiotica Limited, while Asia-Pacific rapidly emerges due to expanding clinical research infrastructure and rising metabolic disorder burdens.
In-depth regional review of key markets
North America leads through dense venture capital funding and advanced manufacturing hubs for oral fecal microbiota transplantation capsules. Conversely, European markets prioritize stringent centralized EMA approvals, heavily influencing how companies like Infant Bacterial Therapeutics AB structure their clinical trials for neonatal and pediatric indications.
Company profiles and strategic positioning of leading market participants
Key innovators maintain distinct strategic moats: Vedanta Biosciences Inc. focuses on rationally designed consortia, while Azitra Inc. targets dermatological conditions using genetically modified strains. Firms like BiomeBank Pty Ltd and Scioto Biosciences Inc. leverage proprietary donor screening and delivery technologies to secure competitive differentiation.
Porter's Five Forces analysis of the Live Biotherapeutics Market
Industry rivalry is intense, driven by continuous patent filings in gene-edited microbial therapies. Supplier power remains low regarding raw microbial strains but high for specialized GMP manufacturing facilities. Threat of substitutes is moderate, restricted by the unique mechanism of live biotherapeutics in restoring complex gut microbiota ecosystems.
SWOT analysis of the industry
Strengths include high therapeutic specificity and novel mechanisms of action. Weaknesses involve complex manufacturing scale-up and short shelf-lives. Opportunities lie in expanding into Neurological Disorders and Respiratory Disorders. Threats center on unforeseen immunogenic adverse events and stringent, evolving regulatory compliance standards.
Value chain analysis from raw materials to end-users
The value chain initiates with precise donor sourcing or synthetic strain engineering, transitioning through fermentation, lyophilization, and formulation into Oral Fecal Microbiota Transplantation Capsules. Downstream distribution utilizes specialized cold-chain logistics to supply hospital pharmacies and retail networks serving end patients.
Investment insights and high-potential areas
Investors should target early-stage biotechs specializing in Precision Microbiome Consortia and Metabolite Producing Engineered Bacteria. Companies utilizing automated fermentation and standardized stool-derived therapeutics present high-yield acquisition targets for large pharmaceutical conglomerates seeking pipeline diversification.
Conclusion and key takeaways
The Live Biotherapeutics Market represents a frontier of biopharmaceutical innovation, backed by a compelling 15.67% CAGR heading toward 2033. Success in this sector demands rigorous adherence to GMP standards, robust supply chain resilience, and continuous investment in advanced genetic engineering and bacterial consortia platforms.
Research methodology for baseline estimates and data triangulation
Our baseline estimates are rigorously triangulated by cross-referencing trade registry data, clinical trial registries, and primary stakeholder interviews with key opinion leaders. This is synthesized alongside macroeconomic indicators and secondary databases from regulatory authorities like the FDA and EMA to ensure high-fidelity market sizing.
Scope of the report, coverage parameters, and analytical limitations
This report covers global revenue projections from 2026 to 2033, segmenting the market by application, product type, microorganism type, distribution channel, and route of administration. Limitations include potential delays in regulatory approvals and unforeseen macroeconomic shifts affecting clinical trial funding velocities.
Recent developments, partnerships, and strategic moves in the industry
Recent industry momentum is defined by strategic acquisitions, co-development partnerships, and FDA fast-track designations for microbiome therapies. Companies like Servatus Biopharmaceuticals Pty Ltd and AOB Pharma Inc. have actively forged clinical alliances to accelerate Phase II and III trials across multi-strain and defined bacterial categories.