Market overview and structural scope of the Neuralink-Class Implantable Neural Interface Market
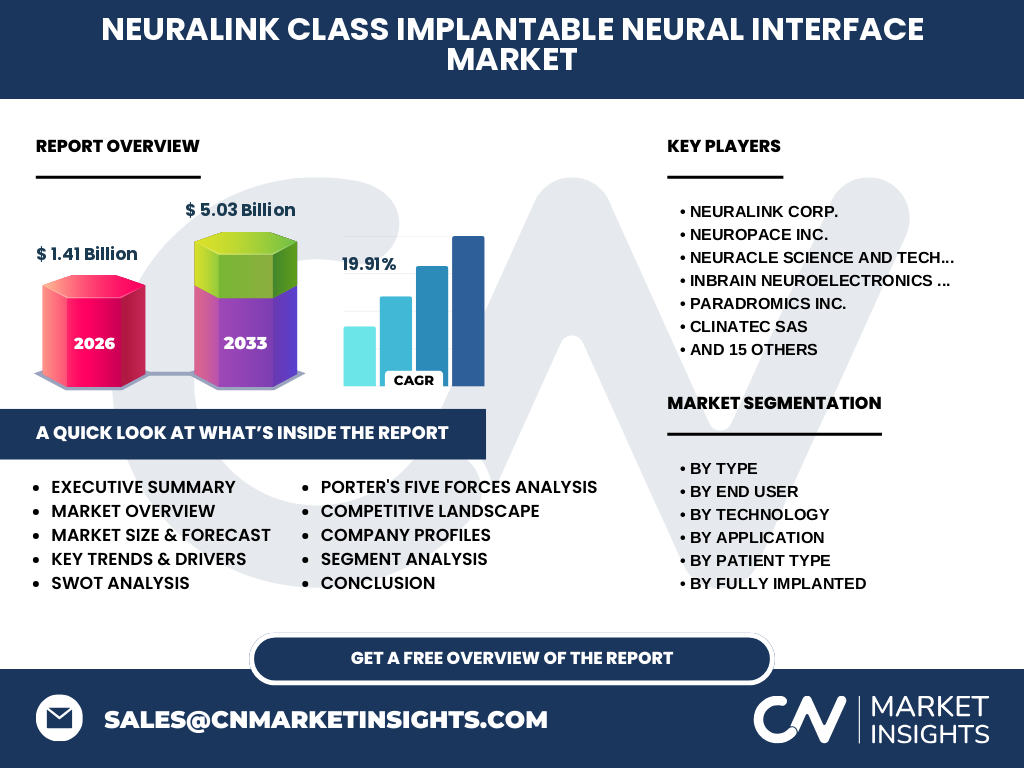
Our analysis indicates that the Neuralink-Class Implantable Neural Interface Market valued at $1.41 Billion in 2026 represents a paradigm shift in neurotechnology. This sector encompasses ultra-high-channel-count intracortical arrays and high-bandwidth telemetry designed to restore motor and cognitive functions via direct bi-directional communication between neural tissue and digital processors.
Structural Growth Drivers and Market Restraints
The market is propelled by a robust CAGR of 19.91%, driven by breakthroughs in biocompatible polymers, flexible thin-film electrodes, and increasing venture capital backing. However, strict regulatory oversight by agencies like the FDA and the complexities of biocompatibility testing for long-term intracranial implants remain formidable clinical hurdles.
Emerging Technological Trends in High-Bandwidth Brain-Computer Interfaces
The shift toward minimally invasive endovascular approaches pioneered by companies like Synchron stands out alongside ultra-dense intracortical arrays from Neuralink and Blackrock Neurotech. Industry trends prioritize wireless telemetry and energy-harvesting rechargeable power systems to eliminate percutaneous infection risks.
Pandemic Aftershocks: COVID-19 Impact and Recovery Trajectory
The COVID-19 pandemic severely disrupted early-stage preclinical trials and strained supply chains for medical-grade titanium and platinum-iridium raw materials. Post-pandemic recovery has accelerated as hospitals and specialized neurosurgery centers resume elective neurosurgical procedures and clinical validation trials.
Competitive Benchmarking and Strategic Landscape Dynamics
The competitive landscape features a dynamic interplay between venture-backed innovators like Paradromics, Precision Neuroscience, and Science Corporation, and legacy medtech giants such as Medtronic and Abbott. Market concentration is currently moderate but shifting rapidly as early pioneers secure proprietary channel-density patents.
Executive Summary of the Neuralink-Class Implantable Neural Interface Market Report
Our comprehensive research confirms the Neuralink-Class Implantable Neural Interface Market will expand dramatically to reach $5.03 Billion by 2033. This hyper-growth trajectory is anchored by expanding indications in medical therapeutics, neuroprosthetics, and advanced cognitive enhancement research.
Market Forecast and Valuation Trajectory from 2027 to 2033
Driven by a sustained 19.91% CAGR, the market will scale from its 2026 baseline of $1.41 Billion to $5.03 Billion by 2033. This expansion reflects the transition of ultra-high-channel neural interfaces from experimental academic studies to commercial neurosurgical adoption.
Comprehensive Segmentation Analysis across Technology and Application Vectors
The market is segmented by type into Partially Implanted, Fully Implanted, and Electrocorticography Arrays. End-user deployment spans hospitals, specialized research institutes, rehabilitation centers, and defense organizations utilizing invasive and semi-invasive technologies for adult and pediatric patient cohorts.
Geographic Distribution and Regional Performance Analysis
North America commands the largest market share, bolstered by robust venture capital ecosystems and streamlined FDA breakthrough device designations. Meanwhile, Europe demonstrates strong adoption led by specialized academic consortia, while Asia-Pacific markets show accelerated growth fueled by robust government-backed medtech initiatives in China.
In-Depth Regional Review of North America, Europe, and Asia-Pacific
North America remains the epicenter for high-density neural interface innovation, supported by advanced neurosurgical hubs in major metropolitan clusters. Concurrently, European markets focus heavily on translational clinical research, while Asian markets rapidly scale manufacturing capabilities for biocompatible micro-electrode arrays.
Company Profiles and Strategic Positioning of Industry Leaders
Pioneering firms like Neuralink Corp., Synchron, and Blackrock Neurotech lead the charge in intracortical and endovascular modalities, respectively. Meanwhile, established giants like Medtronic, Boston Scientific, and Abbott leverage extensive distribution networks and regulatory expertise to capture adjacent neurostimulation and neuromodulation segments.
Porter's Five Forces Analysis of the Neuralink-Class Implantable Neural Interface Market
Rivalry is intense among venture-backed innovators, while the threat of new entrants is mitigated by exceptionally high capital requirements and rigorous clinical validation barriers. Bargaining power of suppliers is moderate due to specialized raw material dependencies, whereas buyer power remains low given the scarcity of alternative therapeutic modalities.
SWOT Analysis: Evaluating Strengths, Weaknesses, Opportunities, and Threats
Key strengths include unprecedented data transmission bandwidth and precision motor restoration capabilities. Critical weaknesses involve battery lifespan limitations and surgical invasiveness. Growth opportunities lie in commercializing closed-loop systems, while regulatory delays and neuroethical concerns represent overarching market threats.
Value Chain Analysis from Raw Material Sourcing to Clinical End-Users
The value chain begins with high-purity raw material suppliers providing platinum, iridium, and biocompatible silicone. This flows into semiconductor fabrication of micro-electrode arrays, system integration by device manufacturers, and final deployment within specialized neurosurgery centers and rehabilitation hospitals.
Investment Insights and High-Potential Strategic Opportunities
Investors should prioritize companies developing wireless closed-loop fully implantable systems and energy-harvesting rechargeable architectures. These technologies address primary clinical pain points regarding device longevity and patient safety, offering superior long-term valuation potential.
Conclusion and Strategic Takeaways for Industry Stakeholders
The Neuralink-Class Implantable Neural Interface Market represents a transformative frontier in healthcare, set to reach $5.03 Billion by 2033. Stakeholders must navigate stringent clinical validation pathways and prioritize wireless, biocompatible engineering to capture market share.
Research Methodology and Data Triangulation Protocols
Our baseline estimates are established through rigorous data triangulation, combining trade registry datasets, primary interviews with neurosurgeons and regulatory experts, and secondary macroeconomic indicators. This multi-layered approach ensures high fidelity in market sizing and forecasting models.
Scope of the Report and Analytical Coverage Parameters
This report covers the global Neuralink-Class Implantable Neural Interface Market across all major technology types, patient demographics, and geographic regions. Limitations include the exclusion of non-implantable EEG consumer headsets and purely theoretical academic neural models without active hardware prototypes.
Recent Developments, Strategic Partnerships, and Product Launches
Recent industry momentum is highlighted by expanding human clinical trials for intracranial implants by Neuralink and Synchron, alongside strategic acquisitions by major medtech players seeking to integrate high-density electrocorticography arrays and wireless telemetry systems into their product portfolios.