What is the scope and industry significance of the Intelligent Blood Collection Management Systems Market?
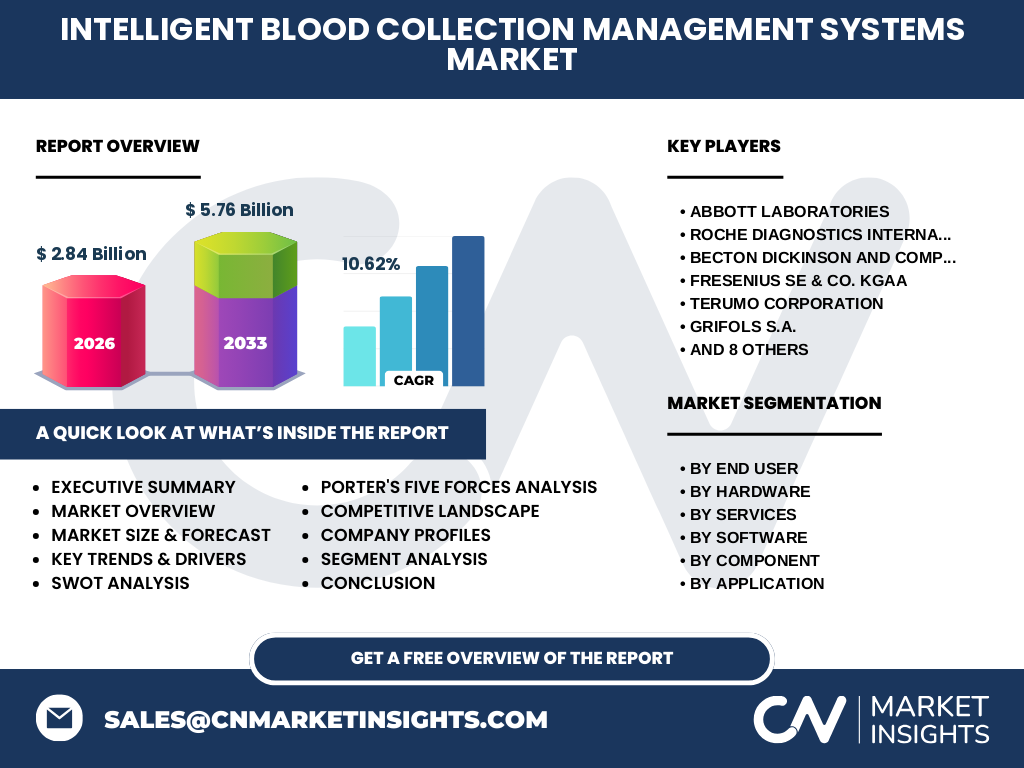
Our analysis indicates that the Intelligent Blood Collection Management Systems Market represents a critical digital transformation vector in healthcare, valued at $2.84 Billion in 2026. This sector encompasses advanced hardware, specialized software, and integration services designed to eliminate pre-analytical errors, optimize phlebotomy workflows, and secure traceability across clinical laboratories and blood donation centers worldwide.
Structural Growth Drivers and Market Restraints
Growth is propelled by rising regulatory mandates from bodies like the FDA regarding patient sample safety and a surge in surgical procedures requiring secure blood supplies. However, the market faces significant restraints, notably the high upfront capital expenditure required to upgrade legacy hospital information systems and stringent data privacy compliance hurdles associated with cloud-based donor management deployments.
Emerging Industry Trends and Adoption Patterns
The shift toward cloud-based software deployment and automated barcode scanner integration is accelerating across Tier-1 research laboratories. Institutions increasingly demand real-time data analytics software to track blood inventory perishability, driving a paradigm shift from reactive record-keeping to predictive supply chain intelligence in modern blood banking operations.
How did the COVID-19 pandemic impact market trajectories?
The pandemic severely disrupted routine blood drives and hospital phlebotomy schedules, yet it paradoxically accelerated digital adoption. Healthcare facilities rapidly invested in appointment scheduling software and touchless donor management systems to maintain social distancing compliance, establishing a resilient recovery trajectory centered on touchless automation and remote inventory oversight.
Competitive Benchmarking and Market Concentration
The landscape features high market concentration among multinational diagnostics giants and specialized informatics providers. Industry leaders leverage extensive distribution networks and proprietary hardware-software ecosystems. Companies such as Abbott Laboratories, Roche Diagnostics, and Becton Dickinson and Company dominate through bundled offerings spanning blood collection monitors and advanced data analytics platforms.
Executive Summary of Key Research Findings
Driven by compounding clinical demand for error-free sample tracking, the Intelligent Blood Collection Management Systems Market is poised for rapid expansion. Our research projects the market to surge from $2.84 Billion in 2026 to $5.76 Billion by 2033, demonstrating a robust CAGR of 10.62% over the forecast period.
Long-Term Market Forecast from 2027 to 2033
Sustained by accelerated hospital digitization and expanding blood bank infrastructures, our analysis forecasts the market will more than double. Growing from its 2026 baseline, the sector will achieve a valuation of $5.76 Billion by 2033, expanding at a steady 10.62% CAGR fueled by widespread adoption of automated hemoglobin testing devices.
Segmentation Analysis Across Hardware, Software, and Services
The market is comprehensively segmented by End User (Hospitals, Blood Banks, Research Laboratories), Hardware (Blood Collection Monitors, Hemoglobin Testing Devices, Barcode Scanners, Label Printers), Services (Installation, Maintenance, Training, Consulting), Software (Donor Management, Inventory Management, Appointment Scheduling, Data Analytics), Component, Application, and Deployment Mode, providing targeted optimization for every clinical workflow.
Geographic Distribution and Regional Performance
Regional performance varies based on healthcare expenditure and regulatory maturity. North America leads adoption due to stringent compliance frameworks enforced by federal agencies, while the Asia-Pacific region demonstrates the fastest growth trajectory, driven by massive investments in healthcare infrastructure modernization across metropolitan hospital networks and regional blood transfusion centers.
In-Depth Regional Review of Adoption Constraints
While developed economies prioritize seamless interoperability with existing electronic health records, developing regional markets often struggle with high maintenance costs for sophisticated hardware like automated blood collection monitors. Localized logistical hurdles, including cold-chain transport variability, further dictate whether facilities choose on-premises or cloud-based software architectures.
Strategic Positioning of Leading Industry Innovators
Key market participants employ distinct differentiation strategies. Terumo Corporation and Fresenius SE & Co. KGaA focus on integrated hardware-software bleed units, while WellSky Corporation and Macopharma SA specialize in robust donor and inventory management software. Meanwhile, specialists like Inpeco and Delcon S.r.l. engineer high-precision automation for laboratory pre-analytics.
Porter's Five Forces Assessment
Competitive rivalry is intense among established diagnostics conglomerates, while the threat of new entrants remains moderate due to high switching costs and stringent medical device certifications. Bargaining power of buyers is high as large hospital groups demand integrated solutions, whereas supplier power is mitigated by standardized raw material components for hardware production.
SWOT Analysis of the Industry Ecosystem
Strengths include high sample traceability and reduced pre-analytical error rates. Weaknesses involve complex system integration requirements and steep staff training curves. Opportunities lie in expanding cloud-based deployment across emerging markets, while threats stem from cybersecurity vulnerabilities targeting interconnected hospital networks and sensitive donor databases.
Value Chain Analysis from Raw Materials to End-Users
The value chain initiates with raw material sourcing for hardware components, advancing through precision manufacturing of barcode scanners and label printers. Software developers then integrate these devices with analytics engines before channel partners deliver installation, setup, and maintenance services to end-users like hospitals and specialized research laboratories.
Strategic Investment Insights and High-Potential Areas
Investors should target developers of cloud-based data analytics and blood inventory management software, as these segments offer high scalability and recurring revenue models. Strategic partnerships between hardware manufacturers and specialized software firms represent high-potential avenues for capturing market share in rapidly modernizing healthcare systems.
Conclusion and Critical Industry Takeaways
The Intelligent Blood Collection Management Systems Market is transitioning into an indispensable pillar of modern healthcare logistics. With a projected valuation of $5.76 Billion by 2033 growing at a 10.62% CAGR, stakeholders must prioritize interoperability, cybersecurity, and intuitive software design to capture sustained, long-term value.
Research Methodology and Baseline Triangulation
Our baseline estimates are rigorously triangulated by combining exhaustive trade registry data, primary stakeholder interviews with hospital chief medical officers, and secondary macroeconomic indicators. This multi-tiered research approach ensures accurate sizing of hardware, software, and service segments across all tracked geographical regions.
Scope of the Report and Analytical Parameters
This report covers global market dynamics for Intelligent Blood Collection Management Systems from 2026 to 2033. Parameters include detailed evaluations of hardware, software, services, deployment modes, and end-user verticals, though macroeconomic fluctuations and regional regulatory policy shifts are noted as inherent analytical limitations.
Recent Developments and Strategic Industry Moves
Recent market activity is characterized by strategic acquisitions and software upgrade rollouts among market leaders like Sysmex Corporation, Grifols S.A., and Haemonetics Corporation. Companies are actively forging technological partnerships to enhance cloud-based data analytics capabilities and expand their geographic footprints in response to evolving healthcare compliance standards.