What is the scope and industry significance of the Hyperthermia Cancer Treatment Market?
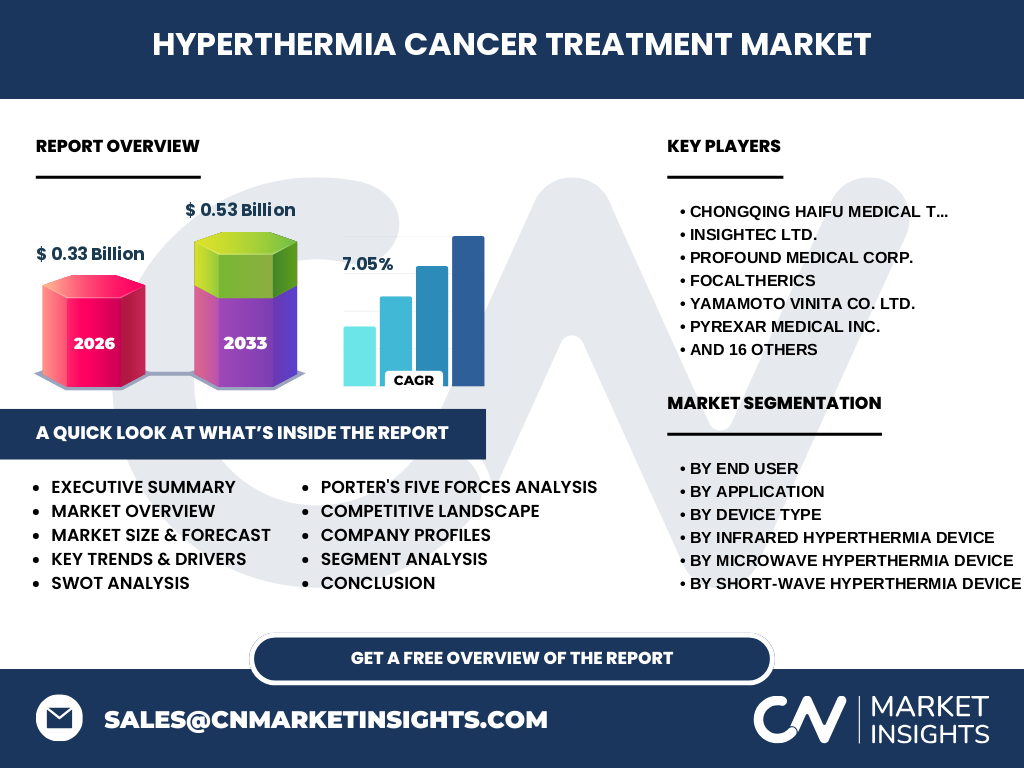
Our analysis indicates that the Hyperthermia Cancer Treatment Market is valued at $0.33 billion in 2026, establishing a vital clinical frontier in oncology. This sector encompasses advanced therapeutic systems designed to heat malignant tissues, enhancing the efficacy of radiotherapy and chemotherapy by exploiting tumor hypoxia and localized blood flow vulnerabilities.
What are the primary growth drivers, restraints, challenges, and opportunities shaping the sector?
The market is propelled by rising oncology investments and technological integrations combining thermal therapies with image-guided systems. Regulatory hurdles from agencies like the FDA and EMA create strict validation timelines, yet substantial opportunities persist in upgrading regional healthcare infrastructure across underserved emerging economies.
Emerging trends and technological growth patterns in oncology hyperthermia
The industry is witnessing a definitive shift toward precision thermal delivery systems, particularly High Intensity Focused Ultrasound (HIFU) and advanced microwave configurations. Innovators like InSightec Ltd. and Profound Medical Corp. are pioneering MR-guided ablation solutions that drastically minimize off-target thermal damage during complex interventions.
How did the COVID-19 pandemic impact market trajectories and recovery?
Pandemic-induced supply chain disruptions for medical-grade transducers and electronic components temporarily stalled elective oncology procedures. However, our research reveals a robust post-pandemic recovery trajectory, driven by hospital capital expenditure rebounds and accelerated adoption of minimally invasive outpatient thermal oncology modalities.
Competitive benchmarking and strategic market concentration
The Hyperthermia Cancer Treatment Market exhibits moderate concentration, with specialized pioneers like Oncotherm Kft, Pyrexar Medical Inc., and Chongqing Haifu Medical Technology Co. Ltd dominating regional clinical footprints. Competitors frequently engage in strategic distribution partnerships with hospital networks to secure long-term consumable and maintenance service contracts.
Executive summary of key findings and market trajectory
Our comprehensive assessment highlights a robust compound annual growth rate of 7.05% from 2027 to 2033, expanding the market baseline from $0.33 billion to $0.53 billion by 2033. This expansion is anchored by expanding clinical indications in soft tissue sarcoma and recurrent breast malignancies.
Long-term market forecast from 2027 to 2033
Projected data dictates steady acceleration, moving the market valuation from its 2026 base toward $0.53 billion by 2033. This trajectory underscores sustained clinical demand for adjuvant thermal therapies that improve local tumor control rates without compounding systemic patient toxicity.
Detailed segmentation analysis across applications and device types
The market breaks down across key clinical verticals: By End User (Hospitals, Cancer Treatment Centers, Research Organizations), By Application (Breast Cancer, Liver Cancer, Soft Tissue Sarcoma, Leukemia, Head And Neck Tumors, Prostate Cancer), and By Device Type encompassing Microwave, Ultrasound, Infrared, and Short-Wave platforms.
Geographic distribution and regional performance dynamics
North America maintains a dominant revenue share due to high reimbursement acceptance and dense hospital infrastructure. Meanwhile, Asia-Pacific represents the fastest-growing regional segment, spurred by expanding oncology clinical trials in localized tumor treatments spearheaded by firms like Yamamoto Vinita Co. Ltd.
In-depth regional review of key markets and reimbursement landscapes
European adoption is heavily influenced by localized health technology assessments across Germany and France, favoring manufacturers such as Celsius42 GmbH and Heckel Medizintechnik GmbH. Reimbursement coding availability remains the single most critical variable dictating regional unit placement velocity for specialized thermotherapy suites.
Company profiles and strategic positioning of industry leaders
Industry stalwarts leverage distinct competitive advantages: Sonablate Corp. and Theraclion SA focus on focused ultrasound precision, while Hydrosun GmbH and Elmedical Ltd. specialize in targeted infrared and localized electromagnetic heating architectures tailored for outpatient oncology clinics.
Porter's Five Forces analysis of the hyperthermia treatment sector
Supplier power remains moderate due to specialized raw material requirements for radiofrequency amplifiers and ceramic transducers. Conversely, buyer power is constrained by high switching costs associated with integrated hospital radiotherapy suites, while threat of substitution is mitigated by thermal therapy's unique radio-sensitizing synergy.
SWOT analysis of the global thermal oncology market
Key strengths include high clinical synergy with radiation oncology; weaknesses involve high initial capital expenditure requirements. Opportunities lie in expanding interstitial microwave applications, while existential threats center on protracted health technology assessment approval cycles for novel device iterations.
Value chain analysis from raw material sourcing to clinical end-users
The value chain originates with rare-earth magnetic suppliers, specialized alloy manufacturers, and piezoelectric crystal growers. These components are integrated by OEMs like Rand S.r.l. and Sensius B.V., flowing through specialized logistics hubs directly to hospital surgical suites and academic research institutes.
Strategic investment insights and high-potential market pockets
Investors should prioritize companies developing interstitial ultrasound heating and deep tissue microwave systems, as these segments offer superior thermal dosimetry control. Venture capital and strategic medtech acquirers are actively targeting firms with proprietary software algorithms capable of real-time magnetic resonance thermal imaging.
Conclusion and strategic industry takeaways
The Hyperthermia Cancer Treatment Market is transitioning from a niche adjuvant modality into an essential pillar of modern multi-modal oncology. Achieving the forecasted $0.53 billion valuation by 2033 will require sustained clinical trial investments and streamlined regulatory navigation.
Proprietary research methodology and data triangulation
Our baseline estimates are rigorously triangulated by combining secondary macroeconomic indicators from global health registries, primary stakeholder interviews with clinical oncologists, and exhaustive trade registry data tracking capital equipment shipments across major international maritime and air cargo hubs.
Scope of the report, coverage parameters, and operational limitations
This report covers global commercial revenue for microwave, ultrasound, infrared, and short-wave hyperthermia devices across hospitals, treatment centers, and research bodies from 2026 to 2033. Excluded from this scope are generic physiotherapy thermal packs and non-oncological aesthetic hyperthermia applications.
Recent industry developments, strategic partnerships, and product launches
Recent market velocity is marked by aggressive R&D collaborations between device manufacturers like Clinical Laserthermia Systems AB and academic medical centers. Companies are heavily investing in artificial intelligence-driven thermal mapping tools to optimize clinical workflows and reduce operator dependency during treatments.