What is the market overview of the Spasticity Management Drugs Market?
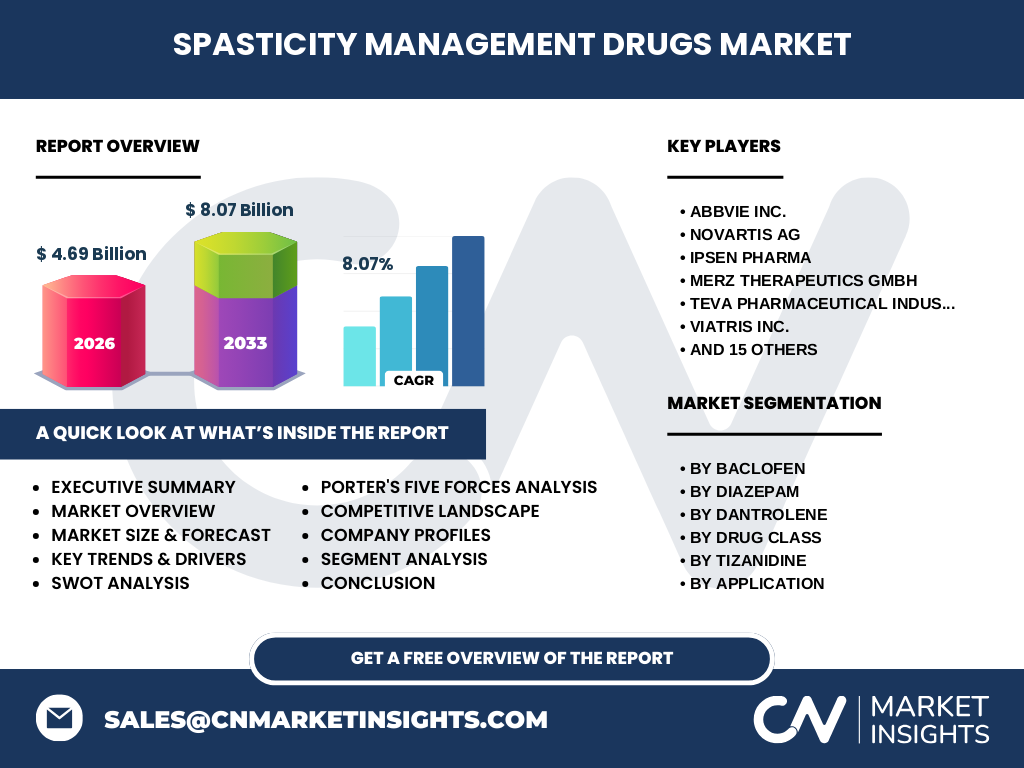
Our analysis indicates that the Spasticity Management Drugs Market is defined by the commercialization and clinical utilization of therapeutic agents targeting hypertonicity resulting from upper motor neuron lesions. Valued at 4.69 Billion in 2026, this sector encompasses critical pharmacological interventions overseen by regulatory bodies like the FDA and EMA, addressing muscle stiffness associated with multiple sclerosis and cerebral palsy.
Key market drivers, restraints, challenges, and opportunities shaping Spasticity Management Drugs Market
The market is propelled by an aging global demographic and rising incidences of stroke and spinal cord injuries. However, growth is restrained by stringent regulatory approvals for complex neurotoxins and logistical hurdles in cold-chain distribution for injectable formulations. Opportunities lie in expanding generic formulations and advancing targeted intrathecal delivery mechanisms.
Emerging trends and growth patterns in Spasticity Management Drugs Market
The shift toward combination spasticity therapies and extended-release profiles is redefining clinical standards. Industry innovators are increasingly focusing on cannabinoid-based drugs and long-acting botulinum formulations to improve patient adherence and minimize systemic side effects associated with traditional oral muscle relaxants.
How did the COVID-19 pandemic impact the Spasticity Management Drugs Market and its recovery trajectory?
The pandemic caused severe supply chain disruptions for active pharmaceutical ingredients sourced globally, alongside delayed elective neurological assessments. The recovery trajectory has been robust, driven by the resumption of specialized outpatient clinics and increased reliance on online pharmacies for chronic medication refills.
Competitive Benchmarking in the Spasticity Management Drugs Market
The competitive landscape is characterized by a mix of multinational innovators and aggressive generic manufacturers. Companies like AbbVie Inc. and Novartis AG dominate proprietary neurotoxins and branded oral agents, while firms such as Teva Pharmaceutical Industries Ltd. and Dr. Reddy’s Laboratories Ltd. drive volume through extensive generic portfolios.
Executive Summary: Spasticity Management Drugs Market Analysis
Our comprehensive research projects the Spasticity Management Drugs Market to expand significantly from 2027 to 2033, achieving a projected valuation of 8.07 Billion at a robust CAGR of 8.07%. Strategic consolidation, pipeline diversification into combination therapies, and rising neurological disorder prevalence underpin this high-growth trajectory.
Market forecast for the Spasticity Management Drugs Market from 2027 to 2033
Driven by rising neurological disorder prevalence and improved diagnostic rates, the market is set to scale rapidly through the forecast window. Sustained R&D investments by key players like Pfizer Inc. and Ipsen Pharma will catalyze the commercial adoption of advanced therapeutic classes, reaching the 8.07 Billion milestone by 2033.
Segmentation analysis across drug classes, routes of administration, and distribution channels
The market segments by drug class into Baclofen, Tizanidine, Diazepam, Dantrolene, and Botulinum Toxin. Routes of administration span oral, injectable, and other specialized delivery methods. Distribution is anchored by hospital pharmacies and retail pharmacies, catering to pediatric, adult, and geriatric patient demographics across diverse applications.
Regional market analysis and geographic distribution performance
Geographic performance highlights North America and Europe as dominant revenue generators, bolstered by advanced healthcare infrastructure and favorable reimbursement policies for specialized neurotoxins. Meanwhile, the Asia-Pacific region demonstrates the fastest regional growth, propelled by expanding access to essential medicines in emerging economies like India.
In-depth regional review of high-growth territories
North America leads consumption due to high concentrations of specialized rehabilitation centers and strong market penetration by firms like Amneal Pharmaceuticals Inc. and Viatris Inc. In contrast, Latin America and the Middle East face localized logistical constraints but offer untapped potential for generic suppliers like Sun Pharmaceutical Industries Ltd.
Company profiles and strategic positioning of leading market participants
Industry leaders maintain distinct competitive moats: Merz Therapeutics GmbH focuses heavily on specialized neurotoxin delivery, whereas Cipla Limited and Lupin Limited leverage broad manufacturing footprints to dominate generic oral and injectable segments across domestic and international regulatory jurisdictions.
Porter's Five Forces analysis of the Spasticity Management Drugs Market
The industry exhibits moderate-to-high supplier power due to stringent regulatory validation required for active pharmaceutical ingredients. Competitive rivalry is intense among generic manufacturers, while the threat of substitution remains low given the clinical necessity of targeted pharmacological agents in severe motor neuron disorders.
SWOT analysis highlighting internal and external market factors
Key strengths include robust pipelines of long-acting formulations, whereas weaknesses involve high clinical trial costs. Opportunities abound in expanding geriatric care markets, offset by external threats such as stringent drug price controls and regulatory scrutiny from bodies like the US FDA.
Value chain analysis from raw materials to end-users
The value chain initiates with chemical raw material synthesis, progressing through active pharmaceutical ingredient manufacturing, formulation by tier-1 pharma companies, and distribution via specialized cold chains to hospital and retail pharmacies, ultimately serving adult, pediatric, and geriatric patients.
Investment insights and strategic recommendations for stakeholders
Investors should direct capital toward companies pioneering extended-release profiles and combination therapies, as these innovations offer superior patent protection and pricing power. High-potential emerging markets present lucrative licensing and acquisition opportunities for mid-sized generic players.
Conclusion and key takeaways for the Spasticity Management Drugs Market industry
The market represents a resilient, high-value segment within neurology, underpinned by steady demographic shifts and therapeutic advancements. Strategic alignment with localized regulatory requirements and investment in novel drug delivery technologies will dictate long-term commercial success for participating enterprises.
Research methodology used to triangulate baseline estimates
Our proprietary research methodology triangulates data by combining exhaustive trade registry analytics, primary stakeholder interviews with clinical neurologists, and secondary macroeconomic indicators sourced from global health organizations to establish rigorous, validated market sizing figures.
Scope of the report, coverage parameters, and analytical limitations
This report covers global revenue performance, segment breakdowns by drug class, route of administration, and distribution channel, alongside competitive positioning from 2026 through 2033. Limitations include unforeseen macroeconomic policy shifts and localized disruptions in pharmaceutical manufacturing supply chains.
Recent developments, product launches, partnerships, and strategic moves
Recent industry activity features strategic portfolio expansions by companies like Zydus Lifesciences Limited and Torrent Pharmaceuticals Ltd., focusing on abridged drug applications for generic tizanidine and baclofen, alongside collaborative distribution agreements targeting emerging pediatric neurology markets.