Market overview of the Handheld X-Rays Market
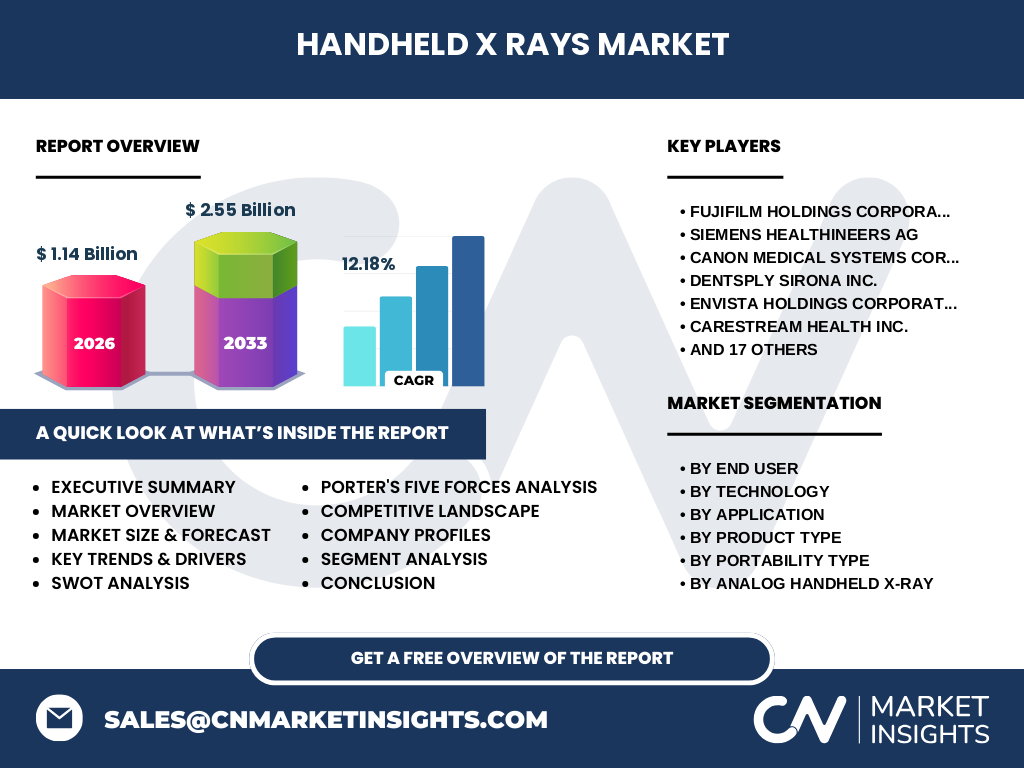
Our analysis indicates that the Handheld X-Rays Market valued at 1.14 Billion in 2026 plays a pivotal role in decentralized medical and dental diagnostics. This sector encompasses portable imaging hardware designed for point-of-care environments where traditional wall-mounted equipment is impractical.
Structural Growth Drivers and Restraints
The market is propelled by a rising demand for point-of-care diagnostics and technological miniaturization. However, strict radiation safety regulations by bodies like the FDA and high initial capital expenditures act as notable restraints for emerging market entrants.
Emerging Trends in Handheld X-Ray Technology
The industry is witnessing a rapid shift toward cloud-connected imaging systems and wireless digital detectors. MinXray Inc. and OXOS Medical Inc. are pioneering real-time remote diagnostics, allowing clinicians to instantly share scans via secure cloud protocols.
COVID-19 Impact Analysis and Recovery Trajectory
The pandemic severely disrupted supply chains for critical raw materials like rare-earth scintillators, yet accelerated the adoption of portable isolation-room imaging. Post-pandemic recovery has been robust, driven by investments in mobile emergency care infrastructure globally.
Competitive Benchmarking and Market Concentration
The Handheld X-Rays Market exhibits a moderately consolidated landscape. Industry titans like Siemens Healthineers AG, Fujifilm Holdings Corporation, and Canon Medical Systems Corporation leverage extensive distribution networks, while specialists like Dexcowin Co. Ltd. focus on dental niches.
Executive Summary of the Handheld X-Rays Market
Our comprehensive research projects the market to expand from 1.14 Billion in 2026 to 2.55 Billion by 2033, registering a robust CAGR of 12.18%. This growth is heavily underpinned by surging demand across ambulatory surgical centers and veterinary clinics.
Long-Term Market Forecast from 2027 to 2033
Based on our econometric modeling, the Handheld X-Rays Market analysis reveals an exponential trajectory, scaling to reach 2.55 Billion by the end of 2033. Adoption rates will accelerate as wireless digital detectors become the clinical standard.
Segmentation Analysis Across Applications and Technologies
The market is segmented by end user (Hospitals, Diagnostic Centers, Ambulatory Surgical Centers, Veterinary Clinics, Other End Users), technology (Digital and Computed Radiography), application (Dental, Orthopedic, Veterinary, Emergency Care), product type, and portability type. Digital Handheld X-Ray variants dominate due to superior image processing.
Geographic Distribution and Regional Performance
North America currently captures the largest revenue share due to sophisticated healthcare infrastructure and early technology adoption. Meanwhile, Asia-Pacific represents the fastest-growing region, fueled by expanding healthcare access in rural tier-2 and tier-3 cities.
In-Depth Regional Review of Healthcare Infrastructure
Regional performance is dictated by regulatory clearance timelines from agencies such as the FDA and EMA. Localized hurdles include reimbursement code complexities for mobile imaging, forcing manufacturers like VATECH Co. Ltd. to adapt regional market entry strategies.
Strategic Positioning of Leading Companies
Market leaders such as DENTSPLY SIRONA Inc., Envista Holdings Corporation, and Planmeca Oy concentrate on dental integration ecosystems. Meanwhile, Turner Imaging Systems Inc. targets orthopedic trauma applications with ruggedized, battery-powered portable units.
Porter's Five Forces Analysis of Competitive Dynamics
Bargaining power of buyers remains moderate due to high switching costs and brand loyalty. Supplier power for specialized high-resolution digital detectors is high, creating significant entry barriers for new manufacturers attempting to source core semiconductor components.
SWOT Analysis of the Handheld X-Rays Industry
Strengths include unmatched mobility and reduced patient transfer times. Weaknesses involve strict radiation shielding requirements. Opportunities lie in emerging veterinary diagnostics, while threats stem from intense price competition among low-cost analog device manufacturers.
Value Chain Analysis from Raw Materials to End-Users
The value chain initiates with raw material sourcing for radiation shielding (lead, tungsten) and solid-state sensors. It flows through precision manufacturing, assembly by innovators like Genoray Co. Ltd., and distribution via specialized medical device dealers to end hospitals.
Strategic Investment Insights and High-Potential Areas
Investors should direct capital toward cloud-connected imaging systems and battery-powered digital units. Companies possessing proprietary AI-assisted image enhancement software represent prime acquisition targets for major conglomerates seeking portfolio diversification.
Conclusion and Key Takeaways for Industry Stakeholders
The Handheld X-Rays Market industry trends confirm a decisive pivot toward digital portability and point-of-care efficiency. Achieving a 12.18% CAGR through 2033 underscores the immense commercial viability for stakeholders investing in wireless and cloud-integrated solutions.
Research Methodology and Baseline Estimation
Our baseline estimates are rigorously triangulated by combining customs trade registry data, primary stakeholder interviews with chief technology officers, and secondary macroeconomic indicators from global health organizations to ensure absolute data integrity.
Scope of the Report and Coverage Parameters
This report covers global revenue performance for the Handheld X-Rays Market market size from 2026 to 2033. Limitations include excluding unverified grey-market medical devices and focusing strictly on FDA- and CE-cleared commercial grade hardware manufacturers.
Recent Developments and Strategic Industry Moves
Recent milestones feature strategic partnerships between portable scanner developers and cloud software providers. Companies like ACTEON Group and DÜRR DENTAL SE have recently launched upgraded wireless detectors designed to withstand rigorous field decontamination protocols.