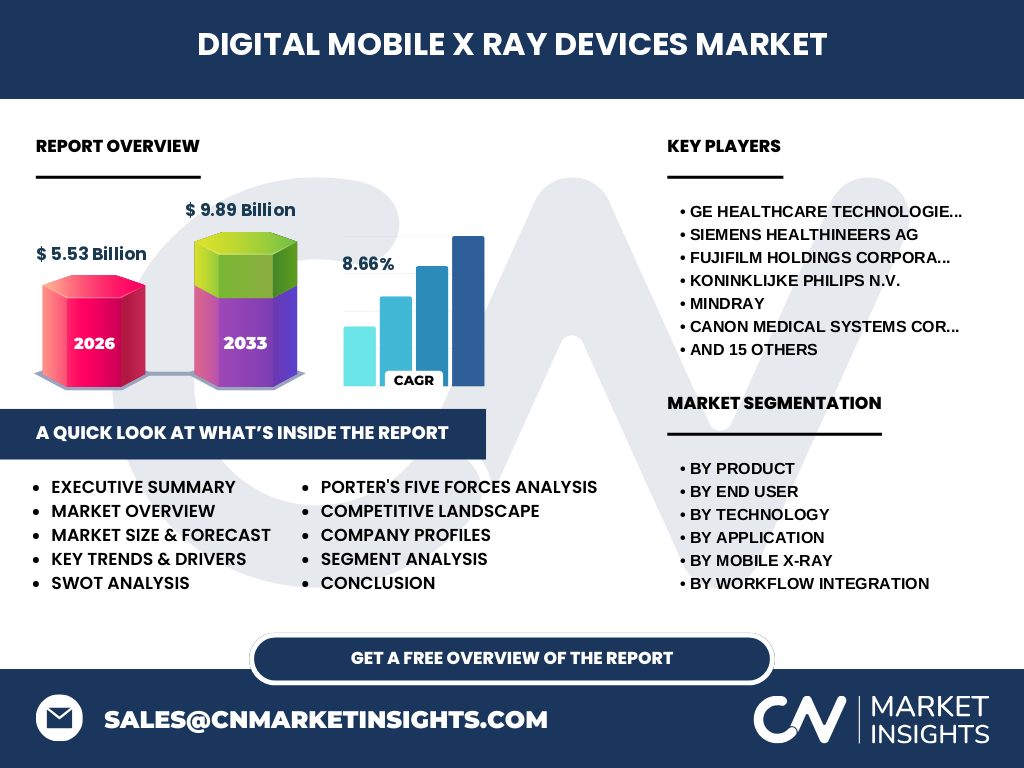
Market overview of the Digital Mobile X-Ray Devices Market
Our analysis indicates that the Digital Mobile X-Ray Devices Market represents a critical paradigm shift in point-of-care diagnostics, with the market size reaching $5.53 Billion in 2026. This sector encompasses advanced radiological systems designed for bedside, emergency, and remote clinical deployment, significantly minimizing patient transport risks while accelerating diagnostic turnaround times across high-acuity hospital departments.
Key market drivers, restraints, challenges, and opportunities shaping Digital Mobile X-Ray Devices Market
The market is propelled by rising geriatric populations and surging demand for rapid bedside diagnostics, though stringent FDA and CE regulatory frameworks present notable commercialization hurdles. Opportunities abound in integrating artificial intelligence for automated chest radiography triage, favoring agile innovators like OXOS Medical Inc. and KA Imaging Inc. in overcoming traditional workflow bottlenecks.
Emerging trends and growth patterns in Digital Mobile X-Ray Devices Market
The industry is witnessing a definitive transition toward lightweight wireless detector mobile X-ray systems and ultra-low-dose flat panel detectors. This technological migration enhances operational efficiency in crowded intensive care units, allowing established players such as Shimadzu Corporation and Carestream Health Inc. to capture high-margin replacement cycles.
COVID-19 impact analysis and recovery trajectory
The pandemic served as an unprecedented catalyst, driving urgent emergency procurement of cart-based and portable digital radiography systems to manage overwhelming respiratory infection caseloads. Post-pandemic recovery has stabilized supply chains originating from major manufacturing hubs, cementing mobile digital radiography as an indispensable element of modern hospital pandemic-preparedness strategies.
Competitive landscape and strategic dynamics
Market concentration remains moderately high, dominated by global heavyweights like GE HealthCare Technologies Inc., Siemens Healthineers AG, and Koninklijke Philips N.V. Strategic positioning relies heavily on proprietary tube design, advanced power-assist drive mechanisms for effortless navigation, and robust PACS/EMR interoperability to secure enterprise-wide hospital group purchasing contracts.
Executive summary of the Digital Mobile X-Ray Devices Market report overview
Driven by robust clinical demand, the Digital Mobile X-Ray Devices Market is projected to expand from $5.53 Billion in 2026 to $9.89 Billion by 2033, registering a solid 8.66% CAGR. Our research highlights direct radiography integration and battery-powered mobility as primary value levers for medical device investors seeking high-growth healthcare technology assets.
Market forecast from 2027 to 2033
The data suggests sustained acceleration, scaling the market from its 2026 baseline to $9.89 Billion by 2033 at a consistent 8.66% CAGR. This expansion is heavily underpinned by capital expenditure renewals in North American and European health systems focusing on decentralized imaging solutions.
Segmentation analysis across product, technology, and application
Segmentation spans Mobile X-Ray and Hand-Held X-Ray Device product lines, utilizing Computed Radiography and Direct Radiography technologies. Applications are heavily weighted toward orthopedic and chest imaging across hospitals, radiology centres, and outpatient clinics, with specialized subsets including battery-powered systems and wireless detectors driving clinical adoption.
Regional market analysis and geographic distribution
Geographic performance shows North America leading revenue generation due to advanced healthcare infrastructure, while the Asia-Pacific region demonstrates the fastest growth trajectory. Favorable government reimbursement policies in mature markets contrast with surging healthcare modernization initiatives across emerging economies in Southeast Asia.
In-depth regional review of key markets
North America anchors global demand, supported by stringent hospital quality metrics that mandate reduced patient transfer times within intensive care units. Meanwhile, Europe exhibits steady adoption governed by strict medical device regulations, and Asia-Pacific markets display rapid uptake driven by expanding tier-two and tier-three city healthcare facilities.
Company profiles and strategic positioning of leading innovators
Industry leaders leverage distinct competitive moats; for instance, Samsung Electronics (NeuroLogica Corp.) and Shanghai United Imaging Healthcare Co. Ltd. focus on high-fidelity imaging with ergonomic maneuverability. Concurrently, specialized firms like MinXray Inc. and DRGEM Corporation target decentralized and military field-hospital segments with ruggedized, compact portable systems.
Porter's Five Forces analysis of the industry
Competitive rivalry is intense among established multinational original equipment manufacturers, while supplier power remains moderate due to specialized rare-earth raw materials required for scintillators. Buyer power is high as large group purchasing organizations negotiate volume discounts, and threat of substitution is mitigated by continuous advancements in digital image quality.
SWOT analysis of the Digital Mobile X-Ray Devices Market
Key strengths include superior diagnostic speed and reduced radiation exposure, balanced by weaknesses such as high upfront capital acquisition costs. Opportunities lie in artificial intelligence-assisted diagnostic software integration, whereas threats involve stringent regulatory compliance timelines and vulnerabilities in global semiconductor supply chains.
Value chain analysis from raw materials to end-users
The value chain initiates with raw material suppliers providing specialized glass substrates, cesium iodide scintillators, and X-ray tube components to manufacturers like Varex Imaging. These components are assembled by OEMs, distributed through specialized healthcare logistics networks, and finally deployed in clinical workflows by radiology technicians.
Investment insights and strategic recommendations
Investors should prioritize companies emphasizing flat panel detector based mobile X-ray systems and wireless workflow integration. Strategic capital deployment toward artificial intelligence diagnostic integration will likely yield superior multiples as hospitals increasingly automate emergency radiological workflows.
Conclusion and key takeaways
The Digital Mobile X-Ray Devices Market industry trends confirm an irreversible shift toward decentralized point-of-care imaging. Achieving an 8.66% CAGR through 2033, the market rewards enterprises capable of combining mechanical mobility with advanced direct radiography and seamless PACS connectivity.
Research methodology and triangulation of baseline estimates
Our analysis is built upon a rigorous triangulation methodology, combining primary stakeholder interviews with C-level radiology executives, exhaustive secondary trade registry data, and macroeconomic healthcare expenditure indicators. This multi-layered approach ensures high fidelity in market sizing and growth projections across all segments.
Scope of the report and coverage parameters
This comprehensive report evaluates the global Digital Mobile X-Ray Devices Market market size across designated product formats, technologies, and end-user verticals from 2026 through 2033. Limitations include macroeconomic variables such as unforeseen currency fluctuations and regulatory policy shifts across developing trade zones.
Recent developments, partnerships, and strategic moves
Recent industry momentum features collaborative product launches integrating advanced AI triage software directly onto mobile units. Innovators like Lumitron Technologies Inc. and Metaltronica continue to secure strategic partnerships and regulatory clearances, expanding the operational capabilities of modern wireless detector mobile X-ray systems.