What is the market overview, definition, and industry significance of the Passenger Coach Market?
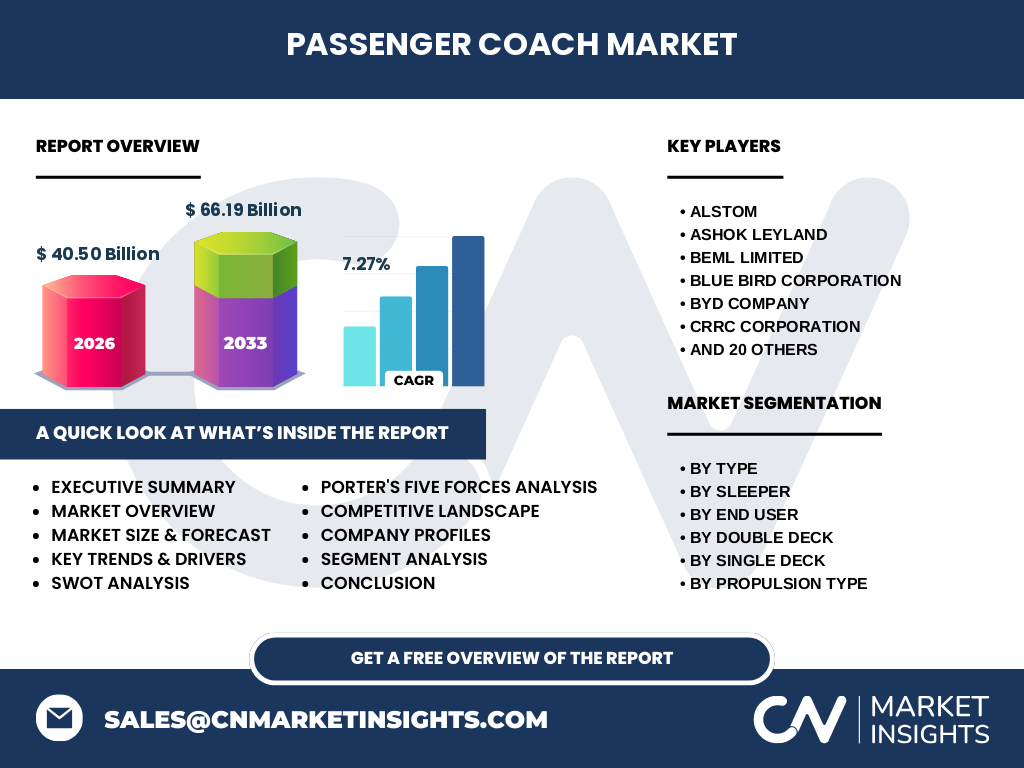
Our analysis indicates the Passenger Coach Market is valued at 40.50 Billion in 2026, serving as the backbone for intercity, tourism, and commuter transit. This ecosystem relies heavily on steel, aluminum, and advanced composite materials, operating under stringent regulatory frameworks set by agencies like the Federal Motor Carrier Safety Administration (FMCSA) and the European Union Agency for Railways (ERA).
Key market drivers, restraints, challenges, and opportunities shaping the Passenger Coach Market
Growth is propelled by urbanization and green transit mandates, though high capital expenditure for zero-emission fleets acts as a primary restraint. Infrastructure bottlenecks in developing regions present notable logistics hurdles, yet operators pivoting toward electric and hybrid architectures unlock substantial opportunities for long-term operational savings and government subsidies.
Emerging trends and growth patterns in the Passenger Coach Market
The industry is experiencing a definitive shift toward sustainable mobility, with electrification and digital fleet management redefining passenger expectations. Fleets are increasingly adopting telematics for predictive maintenance, while passenger-facing innovations like high-speed Wi-Fi and ergonomic seating redefine long-distance travel comfort across major transport corridors.
COVID-19 impact analysis and the recovery trajectory
The pandemic drastically suppressed demand as lockdowns and travel restrictions crippled tourism and intercity transit. Recovery has been steered by fiscal stimulus packages and mandatory health protocols, allowing operators to rebuild ridership through contactless ticketing and enhanced cabin air filtration systems utilizing HEPA technology.
Competitive Benchmarking and Market Concentration
The landscape features intense rivalry among global heavyweights like Daimler Truck, Volvo Group, and Yutong Bus Co., alongside specialized rail-to-road heavyweights such as Alstom and Siemens Mobility. Market concentration is moderate to high, with industry leaders leveraging extensive dealer networks and modular manufacturing to capture municipal and private contracts.
Executive Summary of the Passenger Coach Market report
Our research underscores a robust trajectory, projecting the market to expand from 40.50 Billion in 2026 to 66.19 Billion by 2033 at a CAGR of 7.27%. Strategic consolidation, aggressive electrification mandates, and surging tourism demand are the primary catalysts reshaping operational paradigms worldwide.
Passenger Coach Market forecast and projected growth from 2027 to 2033
The sector is poised for accelerated expansion, scaling from its 2026 baseline to reach 66.19 Billion by 2033. Driven by a robust 7.27% CAGR, investments will heavily favor zero-emission propulsion and high-capacity commuter configurations to alleviate urban congestion.
Segmentation analysis across vehicle types, propulsion, and end users
Segmentation breaks down by Type (Single Deck, Double Deck, Sleeper), Sleeper variants, End User (Government Owned Transport Operators, Private Bus And Coach Operators, Tourism And Travel Agencies, Educational Institutions, Corporate Fleets), Double Deck subtypes, Single Deck sub-categories, Propulsion Type (Diesel, Electric, Hybrid, Other), and Seating Capacity (Up To 30 Seats, 31 To 50 Seats, Above 50 Seats), each dictating distinct manufacturing priorities.
Regional market analysis and geographic distribution performance
Geographic performance varies significantly, with Asia-Pacific leading in volume due to rapid urbanization and state-backed EV rollouts. North America and Europe focus on stringent safety compliance, fleet modernization, and premium luxury coach adoption, while Latin America and MEA exhibit steady demand driven by expanding tourism corridors.
In-depth regional review of key growth territories
European markets prioritize decarbonization, complying strictly with Euro VI and upcoming zero-emission mandates supported by manufacturers like Iveco Group and Scania. Meanwhile, the Asia-Pacific territory relies heavily on domestic powerhouses such as BYD Company and Tata Motors to fulfill massive municipal transit tenders and intercity connectivity projects.
Company profiles and strategic positioning of leading market participants
Industry leaders occupy distinct market niches: Daimler Buses and Volvo Group emphasize premium safety and electrification; Yutong Bus Co. and BYD Company dominate volume-driven EV production; and rail conglomerates like Stadler Rail AG and CRRC Corporation bridge intermodal transport gaps through integrated rolling stock and coach solutions.
Porter's Five Forces analysis of competitive intensity
Supplier power remains moderate due to specialized battery and chassis component requirements. Buyer power is high among large municipal operators, while the threat of substitution is mitigated by the unmatched cost-per-passenger-mile efficiency of buses and coaches relative to private automobiles.
SWOT analysis of the global sector
Strengths lie in established global manufacturing footprints and high-capacity transport efficiency. Weaknesses include high upfront EV battery costs. Opportunities abound in autonomous fleet trials and green transit subsidies, while threats involve volatile raw material prices and geopolitical trade barriers affecting supply chains.
Value chain analysis from raw materials to end-users
The value chain begins with raw material extraction (steel, lithium, aluminum), flowing through tier-1 component suppliers and Original Equipment Manufacturers (OEMs) like Marcopolo S.A. and MAN Truck & Bus, culminating in distribution to private operators, government transit authorities, and final consumer deployment.
Investment insights and strategic recommendations
Investors should direct capital toward electric propulsion technology and charging infrastructure partnerships. Companies boasting modular chassis designs and advanced telematics capabilities offer superior risk-adjusted returns amidst tightening environmental regulations and shifting municipal transit budgets.
Conclusion and key takeaways for industry stakeholders
The Passenger Coach Market represents a high-growth arena anchored by a 7.27% CAGR through 2033. Stakeholders must embrace electrification and digital fleet optimization to secure market share in an increasingly competitive, sustainability-driven global transport ecosystem.
Research methodology and data triangulation techniques
Our baseline estimates are rigorously triangulated by combining official trade registry data, primary executive interviews with C-level stakeholders across Alstom, Ashok Leyland, and Blue Bird Corporation, and secondary macroeconomic indicators sourced from international transport federations and monetary authorities.
Scope of the report, coverage parameters, and analytical limitations
This report covers global revenue streams, volume shipments, and strategic developments from 2026 to 2033. Limitations include unforeseen macroeconomic shocks, regulatory policy shifts in emerging economies, and rapid technological disruptions that may alter near-term adoption curves.
Recent developments, strategic partnerships, and product launches
Recent market activity highlights aggressive joint ventures in hydrogen fuel cell technology and battery-electric platforms by key players such as NFI Group, Irizar Group, and Karsan Otomotiv. These strategic moves underline the industry's rapid pivot toward zero-emission compliance and autonomous depot operations.