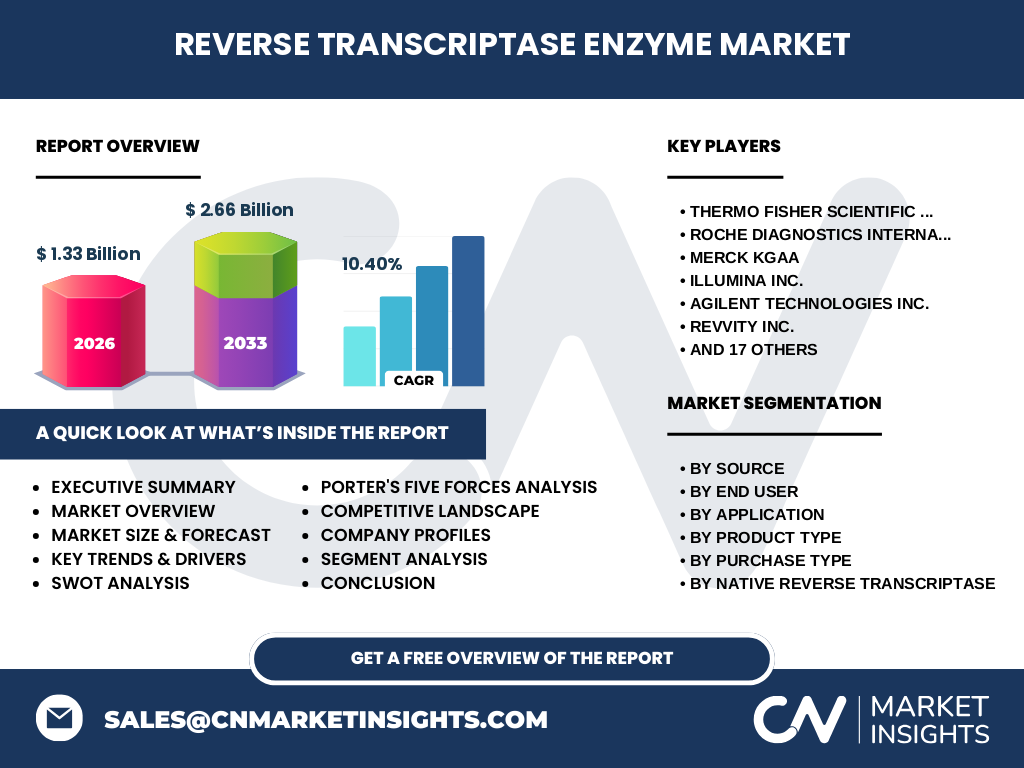
Market overview of the Reverse Transcriptase Enzyme Market
Our analysis indicates that the Reverse Transcriptase Enzyme Market is foundational to modern molecular diagnostics and synthetic biology. Valued at 1.33 Billion, this sector provides critical biochemical tools used by research institutes, pharmaceutical companies, and contract research organizations to convert single-stranded RNA into complementary DNA for downstream applications like RT-qPCR.
Structural Growth Drivers and Restraints
The market is propelled by surging demand for personalized medicine and transcriptomics profiling, contrasted by cold-chain logistics hurdles and stringent regulatory frameworks overseen by bodies like the FDA. Companies such as Thermo Fisher Scientific Inc. and Roche Diagnostics International Ltd. actively innovate to overcome stability constraints during international transit.
Emerging Trends in the Reverse Transcriptase Enzyme Market
A definitive shift toward genetically engineered reverse transcriptase and thermally stable variants is reshaping procurement patterns. End-users increasingly demand enhanced accuracy and reduced ribonuclease activity to minimize experimental failure rates in high-throughput oncology screening workflows deployed globally.
COVID-19 Impact Analysis and Recovery Trajectory
The pandemic catalyzed unprecedented volume expansion for viral-derived and recombinant reverse transcriptase enzymes, driven by massive RT-PCR diagnostic testing requirements. Post-pandemic, the market has recalibrated toward oncology research and infectious disease surveillance, with suppliers stabilizing production capacities across major biotech hubs.
Competitive Benchmarking and Strategic Dynamics
Market concentration remains moderate to high, featuring heavyweights like Merck KGaA, Illumina Inc., and Agilent Technologies Inc. Competing on enzyme fidelity and processivity, firms leverage strategic acquisitions and proprietary engineering platforms to secure market share against agile domestic competitors.
Executive Summary of Key Findings
Our comprehensive report reveals a robust growth trajectory for the sector, projecting the market size to reach 2.66 Billion by 2033. Exhibiting a steady CAGR of 10.40%, the ecosystem offers high-margin opportunities for firms specializing in recombinant variants and direct online distribution channels.
Market Forecast from 2027 to 2033
Driven by expanding clinical diagnostic applications and rising R&D expenditures, our forecast models strong expansion through 2033. The valuation path from the 2026 baseline reflects accelerating adoption of modified reverse transcriptase formulations across commercial biopharmaceutical pipelines worldwide.
Segmentation Analysis by Product, Source, and Application
The market bifurcates across multiple dimensions, including viral, bacterial, and yeast sources, alongside recombinant, native, and modified product types. Applications span molecular biology, clinical diagnostics, and R&D, with research institutes and pharmaceutical firms dominating the end-user landscape.
Regional Market Analysis and Geographic Performance
North America commands a dominant revenue share due to dense clusters of biotechnology innovators, while Asia-Pacific registers the fastest growth rate. Localized market constraints, including import duties on cold-storage enzymes, heavily influence distribution strategies in emerging Latin American and MEA economies.
In-Depth Regional Review
Regional performance highlights heavy reliance on cold-chain logistics hubs near major international airports. North America and Europe emphasize clinical diagnostic integration, whereas Asia-Pacific markets like China and Japan exhibit rapid scale-up in contract research organization capacities and local enzyme manufacturing.
Company Profiles and Strategic Positioning
Leading industry participants such as QIAGEN N.V., Takara Bio Inc., and New England Biolabs Inc. maintain strong competitive moats through patent portfolios covering thermostable and high-fidelity enzymes. Meanwhile, specialized challengers like Watchmaker Genomics Inc. focus on high-yield sequencing applications.
Porter's Five Forces Analysis of the Sector
Bargaining power of buyers is moderate due to standardized assay requirements, whereas supplier power remains low given abundant recombinant expression hosts. Threat of substitution is minimal, though high R&D entry barriers successfully deter unbacked new market entrants.
SWOT Analysis of the Industry Ecosystem
Key strengths include high enzyme specificity and vital utility in gene expression analysis, offset by weaknesses such as cold-chain vulnerability. Opportunities abound in transcriptomic profiling for rare diseases, while regulatory compliance shifts pose ongoing monitoring threats.
Value Chain Analysis from Raw Materials to End-Users
The value chain originates with raw material providers supplying expression vectors and host cells, flowing through enzymatic purification by manufacturers like Promega Corporation and Toyobo Co. Ltd., and terminating with direct or distributor sales to diagnostic laboratories.
Investment Insights and High-Potential Areas
Investors should target developers of high processivity reverse transcriptase and reduced-RNase formulations. These technological niches command premium pricing and align closely with the burgeoning clinical diagnostics and precision oncology segments.
Conclusion and Key Takeaways
The market demonstrates exceptional financial health, underscored by a projected 10.40% CAGR leading to 2.66 Billion by 2033. Strategic focus on modified enzyme engineering will remain the primary differentiator for market leaders seeking sustainable competitive advantage.
Research Methodology and Data Triangulation
Baseline estimates are triangulated by combining proprietary trade registry data, primary stakeholder interviews with key opinion leaders, and secondary macroeconomic indicators from global life science associations to ensure absolute market sizing accuracy.
Scope of the Report and Coverage Parameters
This report covers global revenue estimations across viral, bacterial, and yeast source segments from 2027 to 2033. Limitations include restricted primary visibility into privately held domestic Chinese reagent manufacturers outside major commercial registries.
Recent Developments and Strategic Industry Moves
Recent market activities feature targeted product launches and distribution partnerships by firms like Vazyme Biotech Co. Ltd. and Bioneer Corporation. These strategic maneuvers aim to capture expanding clinical diagnostic demand across decentralized testing networks globally.