What is the scope and industry significance of the Robotic Visualization Systems Market?
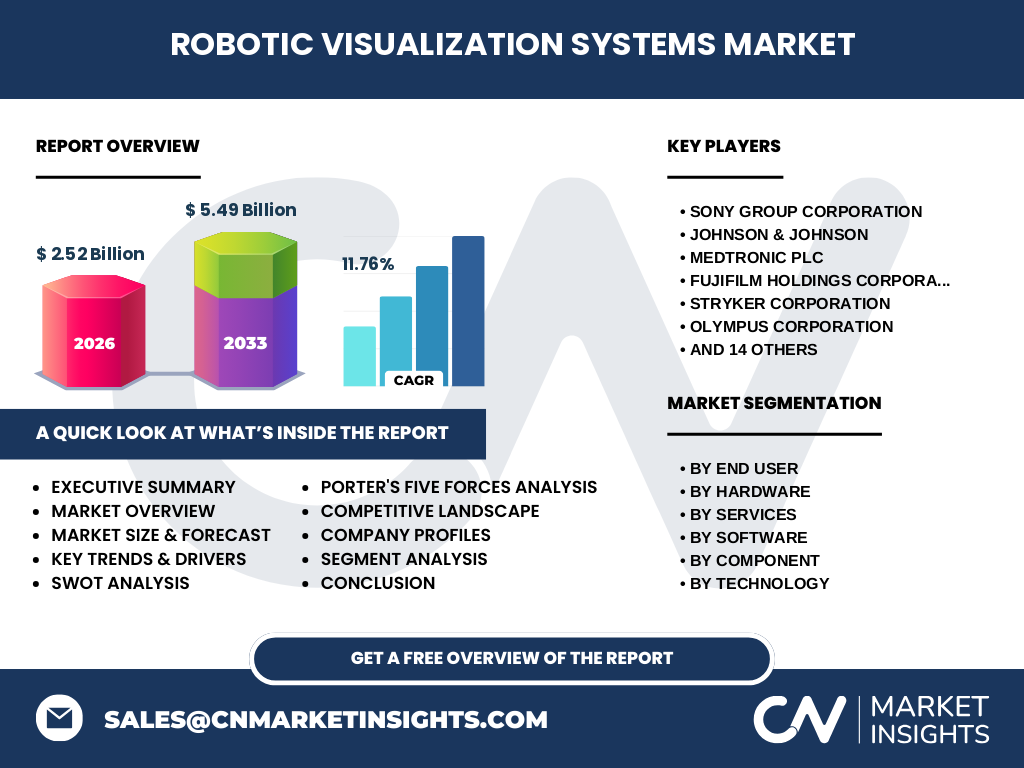
Our analysis indicates that the Robotic Visualization Systems Market reached a valuation of $2.52 Billion in 2026. This sector encompasses advanced optical modules, robotic arms, and specialized software facilitating high-precision surgical and rehabilitation workflows globally.
Key market drivers, restraints, challenges, and opportunities shaping the sector
Growth is accelerated by rising demand for minimally invasive procedures and ultra-high definition imaging. However, supply chain constraints for rare-earth optical components and stringent FDA compliance remain critical hurdles for emerging innovators.
Emerging trends and growth patterns in Robotic Visualization Systems
The industry is witnessing an aggressive pivot toward artificial intelligence analytics software and cloud-integrated systems. These technological shifts allow hospitals to process real-time stereoscopic data with unprecedented sub-millimeter precision during neurosurgeries.
How did the COVID-19 pandemic impact the Robotic Visualization Systems industry trajectory?
Pandemic-era elective surgery halts initially suppressed capital equipment deployment. Yet, post-crisis healthcare modernization initiatives by groups like Medtronic plc and Stryker Corporation catalyzed a robust rebound, prioritizing sterile, remote visualization tools.
Competitive landscape and strategic market concentration
The market features high consolidation among tier-one medtech giants like Johnson & Johnson, Intuitive Surgical Inc., and Olympus Corporation. These players leverage extensive distribution networks to maintain dominance over specialized startups.
Executive summary of the Robotic Visualization Systems Market report
Our research forecasts the market to expand from $2.52 Billion in 2026 to $5.49 Billion by 2033, exhibiting a compound annual growth rate of 11.76% driven by widespread technological integration across global clinical facilities.
Market forecast from 2027 to 2033
Driven by rising healthcare expenditures in emerging economies, the market is projected to achieve $5.49 Billion by 2033. This reflects a steady CAGR of 11.76%, underpinned by heightened demand for 3D and 4K visualization hardware.
Segmentation analysis across hardware, software, and end-user verticals
The market divides across hardware like Robotic Arms and endoscopic modules, alongside software including Surgical Planning Software. End users range from major metropolitan hospitals to specialized ambulatory surgical centers seeking ergonomic efficiency.
Geographic distribution and regional performance dynamics
North America retains the dominant revenue share, supported by advanced reimbursement frameworks and early hospital adoption. Meanwhile, Asia-Pacific represents the fastest-growing frontier due to rapid healthcare infrastructure upgrades in urban medical hubs.
In-depth regional review of key markets
Regional performance is heavily influenced by local regulatory stringency. While FDA clearances dictate North American commercialization velocity, CE mark regulations and localized hospital procurement tenders dictate strategic expansion across European Union member states.
Strategic positioning of leading industry players
Industry leaders such as Karl Storz SE & Co. KG, Zimmer Biomet, and Smith & Nephew plc focus heavily on proprietary ecosystem lock-in. They pair advanced hardware components with dedicated maintenance and training services to secure long-term hospital contracts.
Porter's Five Forces analysis of competitive pressures
Supplier power remains moderate due to specialized optical raw material needs. Conversely, competitive rivalry is fierce as innovators like Moon Surgical SAS and Activ Surgical Inc. challenge legacy incumbents with disruptive visualization platforms.
SWOT analysis for market stakeholders
Strengths include high clinical precision and proprietary AI analytics. Weaknesses involve prohibitive capital expenditure requirements. Opportunities lie in post-stroke rehabilitation applications, while threats stem from complex international medical device compliance audits.
Value chain analysis from raw materials to end-users
The value chain originates with raw optical glass and semiconductor fabrication, flowing through hardware assembly by firms like CONMED Corporation and software developers, ultimately culminating in deployment across clinical and rehabilitation environments.
Investment insights and high-potential areas
Venture capital and strategic acquirers are prioritizing artificial intelligence analytics software and cloud-connected stereoscopic vision systems. These niches offer superior recurring revenue models compared to traditional capital hardware sales.
Conclusion and key strategic takeaways
The projected surge to $5.49 Billion by 2033 underscores the indispensable nature of advanced visualization. Companies successfully merging hardware ergonomics with robust software integration will capture outsized market share.
Research methodology for baseline estimates
Our baseline figures are triangulated by cross-referencing trade registry data, primary qualitative interviews with C-level medtech executives, and secondary macroeconomic indicators from global healthcare expenditure databases.
Scope of the report and coverage parameters
This report evaluates the global Robotic Visualization Systems Market across eight core dimensions, including hardware, software, services, and end-user deployment models, constrained explicitly within the 2026 to 2033 forecasting window.
Recent developments and strategic industry movements
Recent milestones include strategic acquisitions and regulatory clearances secured by firms like ForSight Robotics Ltd. and Brainlab AG. These moves highlight an industry-wide race toward miniaturized, AI-enhanced visualization ecosystems.