What is the market overview and scope of the Managed Domain Name System Market?
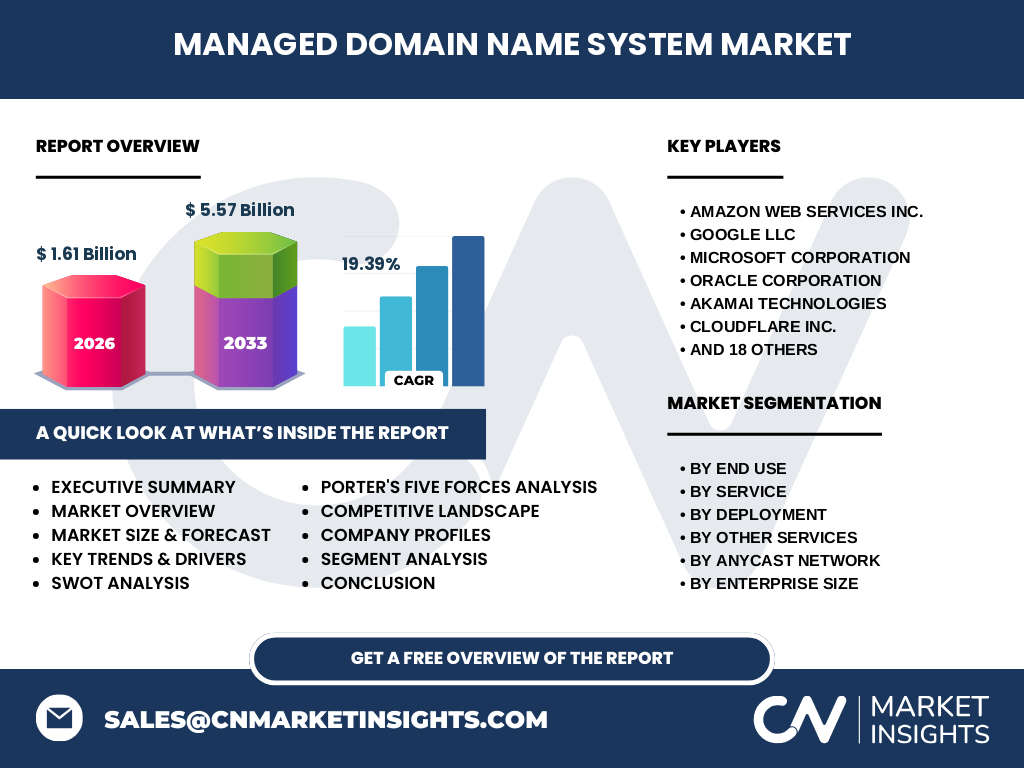
The Managed Domain Name System Market is valued at 1.61 Billion in 2026, serving as the critical infrastructure layer ensuring low-latency internet routing. Our analysis indicates this sector encompasses Anycast networks and DDoS protection, safeguarding enterprise workloads against sophisticated volumetric exploits.
Structural Growth Drivers and Market Restraints
Growth is propelled by surging multi-cloud adoption, requiring robust Geo Domain Name System services. Conversely, the market faces restraints from high migration costs and complex B2B integration hurdles across legacy systems, limiting rapid enterprise deployment.
Emerging Trends Shaping the Industry Landscape
The shift toward API-based DNS management platforms and edge DNS resolution networks defines current Managed Domain Name System Market industry trends. Enterprises increasingly demand real-time attack detection and automated failover traffic steering to maintain uninterrupted uptime.
How did the COVID-19 pandemic impact this sector?
The pandemic accelerated digital transformation, forcing a surge in remote workforce connectivity that stressed corporate DNS architectures. Post-pandemic recovery trajectories show sustained enterprise investments in resilient, cloud-deployed DNS redundancy frameworks.
Competitive Benchmarking and Market Concentration
The Managed Domain Name System Market analysis reveals high concentration among hyperscalers and specialized security vendors. Industry leaders like Amazon Web Services Inc., Cloudflare Inc., and Microsoft Corporation leverage vast Anycast footprints to dominate enterprise traffic handling.
Executive Summary of Key Analytical Findings
Driven by a robust 19.39% CAGR, the Managed Domain Name System Market is projected to surge from 1.61 Billion in 2026 to 5.57 Billion by 2033. Security demands and distributed edge computing are primary catalysts for this expansion.
Market Forecast and Long-Term Projections (2027-2033)
Based on our research, the market will experience exponential scaling, expanding from 2027 through 2033 to reach 5.57 Billion by 2033. This trajectory underscores the critical necessity of advanced DNS security extensions and domain health monitoring.
Segmentation Analysis Across Deployment and Services
The market segments by deployment into On-Premises and Cloud models. Service categories encompass Anycast networks, Distributed Denial of Service Protection, and Geographic DNS, catering to diverse operational demands across large and small enterprises alike.
Geographic Distribution and Regional Performance
Regional performance varies based on telecommunications infrastructure density and regulatory compliance frameworks. North America maintains market leadership, while Asia-Pacific exhibits the fastest adoption rate driven by rapid cloud data center expansions.
In-Depth Regional Review of Growth Hotspots
North America and Europe prioritize strict regulatory compliance, boosting demand for DNS security extensions management. Meanwhile, emerging markets in Asia-Pacific focus heavily on scalable edge DNS resolution networks to combat localized latency issues.
Strategic Positioning of Leading Enterprise Players
Key market participants such as Oracle Corporation, Akamai Technologies, and IBM NS1 Connect differentiate through proprietary Anycast routing and advanced traffic scrubbing. Infoblox Inc. and GoDaddy Inc. target diverse enterprise sizes with tailored domain management solutions.
Porter's Five Forces Industry Competitiveness Assessment
Bargaining power of buyers remains moderate due to specialized technical requirements. Threat of substitutes is low, as DNS is irreplaceable for web routing, while competitive rivalry is intense among dominant cloud providers and dedicated security firms.
Comprehensive SWOT Analysis of the Sector
Strengths lie in ultra-reliable Anycast routing and automated failover. Weaknesses involve complex migration paths. Opportunities exist in API-driven platforms, while threats include increasingly sophisticated, targeted DDoS attacks evading standard rate-limiting filters.
Value Chain Analysis and Industry Structure
The value chain flows from core network infrastructure providers and software developers to managed service platforms, ultimately delivering secure resolution to end-users across banking, retail, and healthcare verticals.
High-Potential Investment Insights and Strategic Recommendations
Investors should target providers offering integrated IP reputation filtering and real-time attack detection. Companies specializing in API-based DNS management platforms represent high-growth vectors as enterprises automate cloud-native architectures.
Conclusion and Definitive Market Takeaways
The Managed Domain Name System Market market size expansion to 5.57 Billion by 2033 highlights mission-critical reliance on secure, resilient routing. Organizations must prioritize advanced cloud deployment and DDoS mitigation to stay competitive.
Robust Research Methodology and Data Triangulation
Our baseline estimates are rigorously triangulated by combining trade registry data, primary stakeholder interviews with network architects, and secondary macroeconomic indicators to ensure precise, actionable market sizing.
Scope of the Report and Coverage Parameters
This report covers global trends across banking, IT, healthcare, and retail sectors from 2026 to 2033. Limitations include restricted data visibility into privately held regional DNS service providers operating outside major peering exchanges.
Recent Industry Developments and Strategic Moves
Recent market activities feature strategic acquisitions, enhanced API integrations, and product launches focused on edge domain name system resolution networks. Competitors continually update their rate-limiting and query-filtering capabilities to counter evolving cyber threats.