Market overview and industry significance of the Total-Body Positron Emission Tomography (PET) Imaging Market
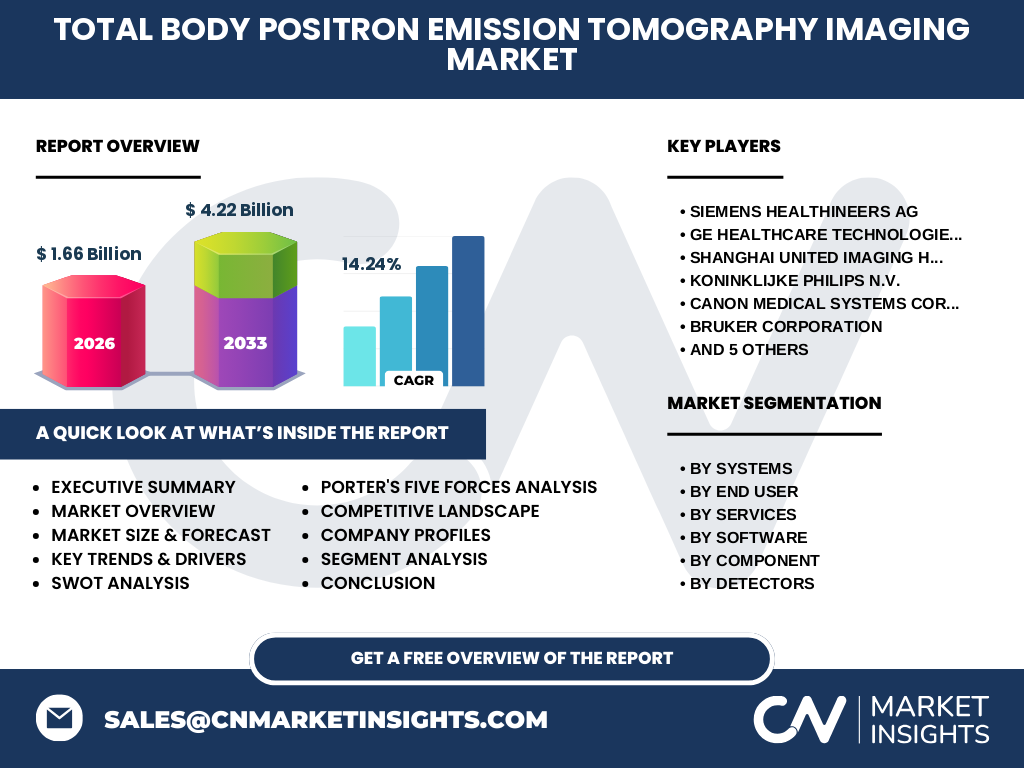
The Total-Body Positron Emission Tomography (PET) Imaging Market represents a paradigm shift in molecular diagnostics, offering axial fields of view exceeding one meter. Our analysis indicates this sector is valued at 1.66 Billion in 2026. This technology enables simultaneous multi-organ imaging, drastically reducing radiopharmaceutical injection doses while capturing kinetic data previously inaccessible with standard clinical scanners.
Structural Growth Drivers, Restraints, Challenges, and Opportunities
Growth is propelled by rising oncology and neurology diagnostic demands, though high capital expenditure remains a severe restraint. Supply chain vulnerabilities regarding Lutetium Yttrium Orthosilicate Detectors and Bismuth Germanate Detectors create logistical hurdles. However, technological maturation in Artificial Intelligence Based Imaging Software presents vast opportunities for automated lesion detection and quantitative kinetic modeling.
The Shift Toward Ultra-High Sensitivity Scanners
Industry trends reveal a rapid pivot from conventional short-axial scanners to total-body architectures. This transition allows for up to 40-fold gains in effective sensitivity. Based on our research, healthcare providers are increasingly prioritizing these systems to capture ultra-fast dynamic scans, fundamentally altering how clinical trials and advanced oncological assessments are conducted globally.
COVID-19 Impact Analysis and Recovery Trajectory
The pandemic severely disrupted capital equipment procurement within the Total-Body Positron Emission Tomography (PET) Imaging Market industry trends due to deferred elective procedures and supply chain bottlenecks for critical scintillator crystals. The recovery trajectory has since rebounded sharply, driven by hospital system capital restructurings and post-pandemic prioritization of advanced early-detection oncology infrastructure.
Competitive Benchmarking and Strategic Dynamics
The market features high consolidation among tier-one medical device manufacturers. Industry leaders like Siemens Healthineers AG, GE HealthCare Technologies Inc., and Shanghai United Imaging Healthcare Co. Ltd. dominate through proprietary detector innovations. Meanwhile, specialized players such as PETsys Electronics S.A. and MILabs B.V. compete by supplying high-performance ASIC readout electronics and specialized preclinical systems.
Executive Summary of the Total-Body Positron Emission Tomography (PET) Imaging Market Analysis
Our proprietary research confirms that the Total-Body Positron Emission Tomography (PET) Imaging Market analysis highlights an inflection point for molecular imaging. Driven by unprecedented diagnostic clarity and expanding clinical applications, the sector is positioned for rapid enterprise adoption across Tier-1 research institutions and specialized diagnostic imaging networks over the coming decade.
Market Forecast and Revenue Projections Through 2033
The data suggests explosive expansion, with the market projected to reach 4.22 Billion by 2033. Achieving a robust CAGR of 14.24% from 2027 to 2033, this trajectory reflects accelerating global reimbursement approvals and widespread clinical validation of total-body systems over legacy hardware configurations in major metropolitan hospital networks.
Comprehensive Segmentation Analysis
The ecosystem is segmented across multiple dimensions to guide procurement strategies.
- By Systems: Standalone PET, Hybrid PET/CT, and PET/MRI systems.
- By End User: Hospitals, Diagnostic Imaging Centers, Research Institutes, and Other End Users.
- By Services: Installation, Maintenance, Repair, and Calibration Services.
- By Software: Image Reconstruction, Quantification and Analysis, and AI-Based Software.
Regional Market Analysis and Geographic Distribution
Geographic performance is heavily concentrated in North America and Western Europe, supported by mature healthcare infrastructure and favorable reimbursement codes. Concurrently, Asia-Pacific markets, led by domestic manufacturing initiatives in China and South Korea, represent the fastest-growing frontier for total-body scanner installations in oncology-focused tertiary medical hubs.
In-Depth Regional Review of Adoption Constraints
Regional dynamics vary significantly based on regulatory frameworks enforced by bodies such as the US FDA and EMA in Europe. While North American institutions readily integrate hybrid Positron Emission Tomography And Magnetic Resonance Imaging Systems, emerging markets face logistical constraints due to stringent shielding requirements and limited domestic availability of short-lived radiotracers.
Company Profiles and Strategic Positioning
Industry giants leverage distinct technical advantages. Koninklijke Philips N.V. and Canon Medical Systems Corporation focus on ultra-fast timing resolution detectors. Concurrently, isotope innovators like NorthStar Medical Radioisotopes secure the vital supply chain for radiopharmaceuticals, while niche entities like MR Solutions Ltd. and Mediso Medical Imaging Systems Ltd. cater to preclinical and specialized translational research applications.
Porter's Five Forces Analysis of Competitive Pressures
Our assessment indicates that competitive rivalry is intense among established conglomerates, while the threat of new entrants remains low due to formidable intellectual property barriers in scintillator crystal production and digital silicon photomultiplier (SiPM) integration. Buyer power is moderate, balanced by the specialized, non-substitutable nature of ultra-high sensitivity whole-body axial imaging technology.
SWOT Analysis of the Total-Body PET Sector
Strengths include revolutionary signal-to-noise ratios and ultra-low radiation exposure. Weaknesses involve extreme unit acquisition costs and heavy facility infrastructure demands. Opportunities lie in neurological tracking for Alzheimer's disease, while threats stem from lingering global semiconductor shortages impacting advanced data acquisition board manufacturing.
Value Chain Analysis from Raw Materials to End-Users
The value chain originates with raw rare-earth raw materials utilized in manufacturing Lutetium Oxyorthosilicate Detectors. These components are integrated by OEMs into complete systems, distributed globally through specialized maritime and air freight corridors, and finally commissioned by certified technicians at hospital sites utilizing specialized Image Reconstruction Software.
Investment Insights and High-Potential Opportunities
Strategic capital should target emerging manufacturers pioneering scalable silicon photomultiplier designs and developers of Artificial Intelligence Based Imaging Software. These solutions mitigate radiotracer dosage limitations and accelerate reconstruction times, offering high-margin recurring revenue models for medical technology venture portfolios and institutional investors.
Conclusion and Strategic Takeaways
The Total-Body Positron Emission Tomography (PET) Imaging Market is redefining clinical standards in oncology and neurology. Stakeholders must align their product roadmaps with software-driven enhancements and hybrid system integration to capture value within this rapidly scaling 1.66 Billion to 4.22 Billion market landscape.
Research Methodology and Baseline Estimation Techniques
Our baseline estimates are triangulated through a rigorous methodology combining exhaustive trade registry data, primary executive stakeholder interviews across major imaging centers, and secondary macroeconomic indicators. We cross-reference institutional procurement filings with regulatory device clearance databases to ensure absolute market sizing accuracy.
Scope of the Report and Coverage Parameters
This report encompasses global revenue streams, volume shipments, and technology adoption rates across all specified system configurations, detector types, and software categories from 2027 through 2033. Excluded from this scope are conventional planar nuclear medicine equipment and standard non-total-body PET/CT configurations not meeting the one-meter axial field-of-view threshold.
Recent Developments in Strategic Partnerships and Product Launches
Recent market activity is characterized by aggressive R&D joint ventures between tier-one vendors and academic medical centers. Leading participants have announced strategic FDA clearances for next-generation digital detectors and cloud-connected Quantification And Analysis Software, aimed at streamlining multi-center clinical trials and expanding routine diagnostic accessibility globally.