Market overview and structural significance of the Self-Centering Vise Market
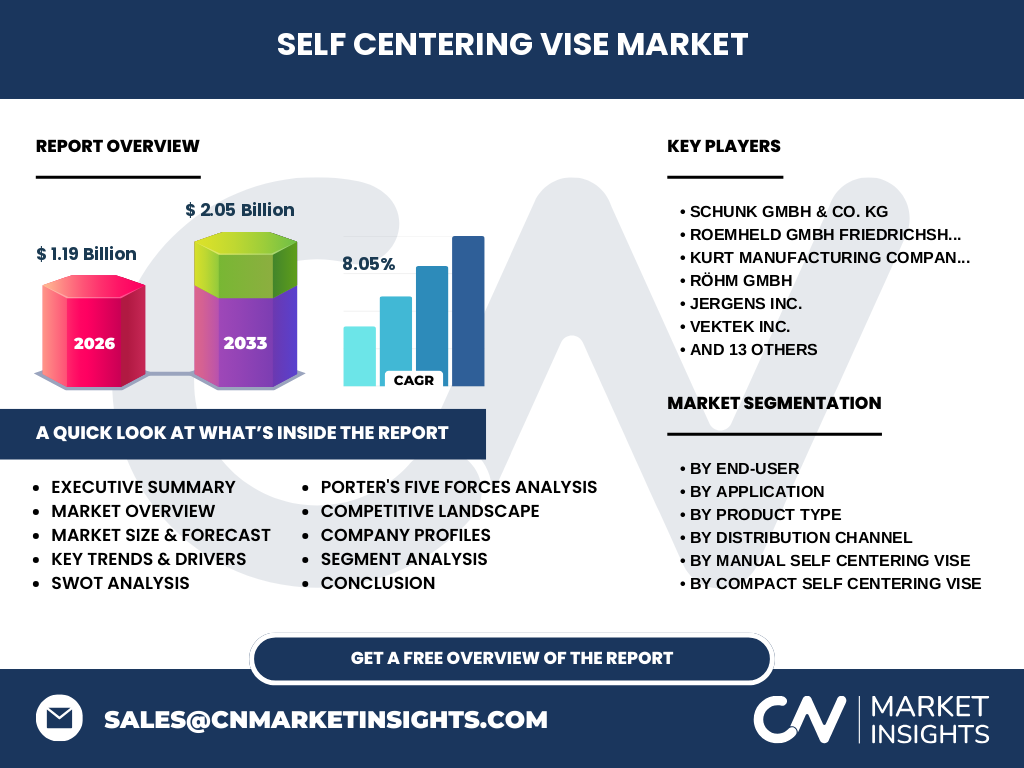
Our analysis indicates that the Self-Centering Vise Market valuation stands at 1.19 Billion in 2026. This sector encompasses high-precision workholding systems essential for modern multi-axis machining centers. These devices guarantee absolute symmetry during workpiece clamping, directly influencing geometric tolerances in high-value manufacturing sectors across global industrial hubs.
What are the primary market drivers, restraints, challenges, and opportunities shaping the industry?
The market is propelled by a relentless push toward automated manufacturing and unattended cell machining. Structural restraints involve high initial capital expenditures for advanced hydraulic and pneumatic workholding retrofits. Growth opportunities emerge heavily within rapid-change modular setups demanded by modern aerospace and automotive component fabricators.
Emerging trends and growth patterns in the Self-Centering Vise Market
The shift toward lights-out manufacturing has accelerated the adoption of automated clamping solutions. Based on our research, smart vise integration featuring IoT-enabled pressure sensors is redefining shop-floor productivity. This trend favors tier-one innovators capable of blending mechanical rigidity with digital monitoring capabilities.
How did the COVID-19 pandemic affect market dynamics and subsequent recovery?
The pandemic initially disrupted global supply chains and halted capital investments in heavy metalworking equipment. Post-pandemic recovery has been swift, fueled by supply chain reshoring initiatives and urgent demand for localized, highly flexible machining cells that reduce dependency on offshore labor.
Competitive benchmarking and strategic market concentration
The landscape features intense competition among specialized engineering firms such as SCHUNK GmbH & Co. KG, ROEMHELD GmbH, and Kurt Manufacturing Company Inc. Market concentration is moderately high in precision tiers, where proprietary quick-change jaw patents and high clamping repeatability separate market leaders from regional commodity suppliers.
Executive summary of key findings
Our comprehensive findings show that the Self-Centering Vise Market is on an aggressive expansion path, driven by strict precision demands in aerospace and electronics manufacturing. Strategic investments in modular and computer numerical control compatible vises will yield the highest returns through 2033.
Market forecast and growth trajectory from 2027 to 2033
The data suggests the market will surge from 1.19 Billion in 2026 to reach 2.05 Billion by 2033, expanding at a robust 8.05% CAGR. This growth trajectory reflects accelerated factory automation and the pervasive need for micron-level machining accuracy across complex milling operations.
Segmentation analysis across end-users, applications, and product types
Segmentation spans end-users like Automotive, Aerospace, Metalworking, Electronics, and General Manufacturing. Applications cover Milling, Drilling, Grinding, Electrical Discharge Machining, and Turning. Product lines range from Computer Numerical Control Self Centering Vise and Hydraulic variants to Heavy Duty and Compact designs, serving diverse clamping parameters.
Geographic distribution and regional market performance
Regional performance mirrors the concentration of advanced automotive and aerospace clusters. North America and Europe lead in early adoption of automated hydraulic and CNC-compatible systems, whereas Asia-Pacific exhibits the fastest volume growth driven by rapid electronics and general manufacturing expansion in localized industrial zones.
In-depth regional review of key industrial territories
In Europe, stringent ISO manufacturing guidelines and established automotive hubs in Germany foster continuous demand for high-end precision vises from players like RÖHM GmbH and Gressel AG. Meanwhile, North American facilities prioritize heavy-duty pneumatic retrofits to maximize spindle uptime against rising labor costs.
Strategic positioning of leading companies in the industry
Market leaders leverage distinct strategic moats. SCHUNK and ROEMHELD focus on high-end hydraulic automation, while Kurt Manufacturing and 5th Axis specialize in rapid-change 5-axis workholding. Companies like Jergens Inc. and Chick Workholding Solutions emphasize modular versatility to minimize tooling downtime for job shops.
Porter's Five Forces analysis of competitive intensity
Supplier power remains moderate due to specialized alloy steel availability. Buyer power is high given numerous regional distributors. Threat of substitutes is low because standard vises cannot match the centering accuracy required for complex 5-axis milling, reinforcing the defensibility of proprietary designs.
SWOT analysis of the Self-Centering Vise Market
Strengths include exceptional centering repeatability and rigid clamping integrity. Weaknesses involve high tooling costs for complex multi-station setups. Opportunities lie in smart IoT-enabled clamping systems, while threats stem from low-cost counterfeit modular clones flooding localized import channels.
Value chain analysis from raw materials to end-users
The value chain originates with alloy steel and ductile iron smelters, moving through precision CNC machining, heat treatment, and grinding. Component assemblers then distribute through direct sales channels and specialized dealers to end-users in aerospace, automotive, and die-mold engineering sectors.
Investment insights and high-potential areas for stakeholders
High-potential areas center on quick-change three-jaw and compact hydraulic systems tailored for automated robotic tending. Investors should target agile manufacturers possessing proprietary quick-release jaw technology and robust digital integration capabilities to capture high-margin retrofit opportunities.
Conclusion and key strategic takeaways
Sustained success in this market requires continuous innovation in material rigidity and automation compatibility. As the industry marches toward 2.05 Billion by 2033, firms that bridge mechanical engineering excellence with smart sensor integration will dominate market share.
Research methodology and data triangulation framework
Our baseline estimates are rigorously triangulated by cross-referencing trade registry export data, primary stakeholder interviews with chief manufacturing engineers, and secondary macroeconomic indicators tracking global machine tool production indices and automation capital expenditure reports.
Scope of the report and analytical boundaries
This report covers global revenue estimations, volume shipments, and strategic profiles across specified product classifications, end-user verticals, and regional territories. Macroeconomic variables such as currency fluctuations and localized tariff shifts are factored into our medium-term forecasting models.
Recent developments, corporate announcements, and strategic moves
Recent industry momentum highlights strategic partnerships between workholding innovators and robotic automation integrators. Major players have launched IoT-enabled hydraulic vises featuring real-time clamping force feedback, directly addressing the stringent quality control demands of modern lights-out manufacturing facilities.