What is the market overview and scope of the Military Digital Twin Market?
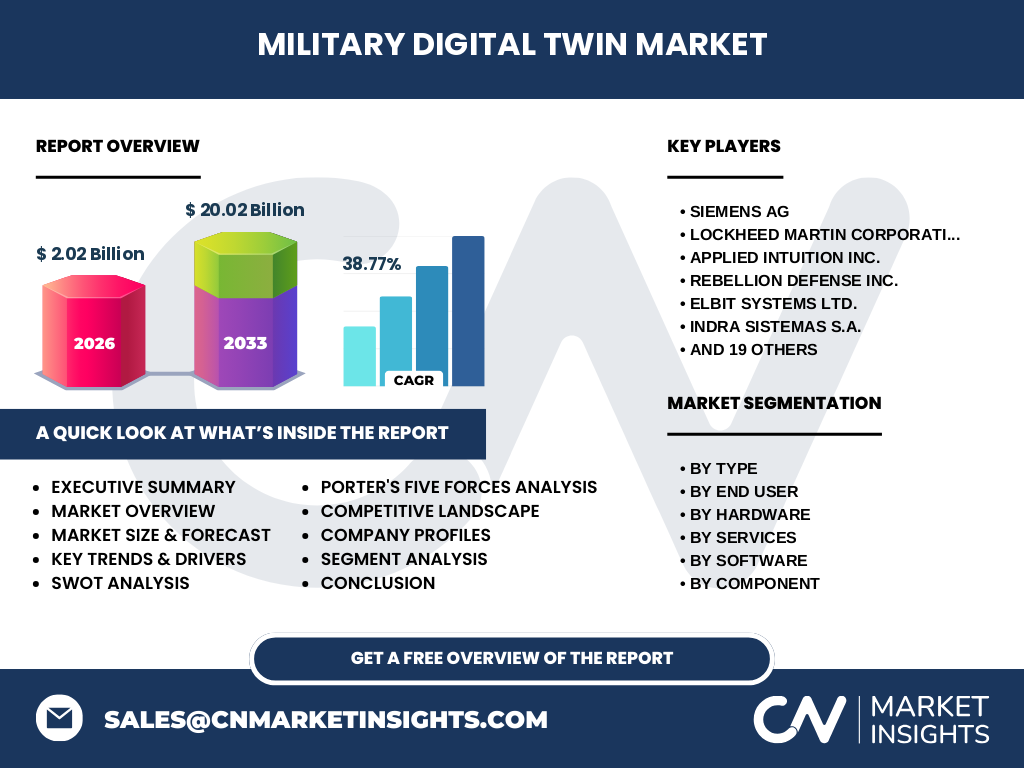
The Military Digital Twin Market represents a paradigm shift in defense technology, valued at $2.02 Billion in 2026. This domain encompasses high-fidelity virtual replicas of physical defense assets, operational environments, and strategic processes, enabling real-time telemetry integration and predictive analytics across global military infrastructure.
What are the structural growth drivers and challenges shaping the Military Digital Twin Market?
Structural growth drivers include surging demand for predictive maintenance and advanced mission simulation. However, the market faces significant restraints regarding secure data handling under strict ITAR regulations and the high cost of integrating legacy hardware with modern cloud-based analytics platforms.
Emerging trends and growth patterns in the Military Digital Twin Market
The integration of artificial intelligence and edge computing stands out as a primary trend, pushing simulation capabilities closer to tactical operational edges. Our analysis indicates that defense forces increasingly rely on hybrid deployment models to balance strict security with rapid cloud processing capabilities.
How did the COVID-19 pandemic impact the Military Digital Twin Market recovery trajectory?
The pandemic exposed vulnerabilities in global supply chains and physical maintenance schedules, accelerating digital twin adoption. Defense agencies leveraged virtual replicas to maintain asset readiness remotely, establishing a steep recovery trajectory that now fuels a massive 38.77% CAGR.
Competitive Benchmarking: Major players and strategic dynamics
The competitive landscape features industry titans like Siemens AG, Lockheed Martin Corporation, and Palantir Technologies Inc. competing alongside agile innovators like Anduril Industries Inc.. Market concentration is moderately high, with prime defense contractors leveraging proprietary simulation software to secure long-term military modernization contracts.
Executive summary of key findings in the Military Digital Twin Market
Our comprehensive research projects the market to skyrocket from $2.02 Billion in 2026 to $20.02 Billion by 2033, driven by a robust 38.77% CAGR. Investment in software ecosystems and AI-driven predictive maintenance remains critical for sustaining this unprecedented defense sector expansion.
Market forecast trajectory from 2027 to 2033
The trajectory points to exponential expansion, scaling from baseline 2026 figures to reach $20.02 Billion by 2033. This meteoric rise, underpinned by a 38.77% CAGR, reflects deep institutional commitments to automated asset performance management and advanced battlespace simulation.
Segmentation analysis by type, hardware, software, services, component, application, and deployment
Segmentation spans platform, system, and process digital twins across army, navy, air force, and space forces. The architecture relies on robust hardware like sensors and edge computing units, alongside specialized software for AI and cybersecurity, delivered via consulting, deployment, and maintenance services.
Geographic distribution and regional market analysis
Geographic performance is heavily concentrated in North America, driven by extensive Department of Defense modernization initiatives. Meanwhile, the Asia-Pacific region demonstrates rapid adoption rates due to rising geopolitical tensions and substantial investments by nations like India in indigenous defense manufacturing.
In-depth regional review of key defense markets
North America maintains market dominance through early adoption by aerospace primes like The Boeing Company and Northrop Grumman Corporation. Concurrently, European markets focus heavily on interoperability standards overseen by the EDA, favoring agile firms like HENSOLDT AG and Rheinmetall AG.
Strategic positioning of leading companies in the sector
Market leaders utilize distinct strategic plays; for instance, Dassault Systèmes SE and Bentley Systems Incorporated provide foundational modeling architecture, while RTX Corporation and CAE Inc. embed these digital twins directly into mission planning and pilot training frameworks.
Porter's Five Forces analysis of the defense simulation sector
Supplier power remains moderate due to specialized hardware dependencies, while buyer power is concentrated among sovereign defense ministries. Threat of new entrants is mitigated by high security clearances, stringent regulatory compliance, and the immense capital required for advanced simulation R&D.
SWOT analysis of the Military Digital Twin Market ecosystem
Strengths include high precision in asset lifecycle management. Weaknesses involve vulnerability to sophisticated cyber threats. Opportunities lie in expanding space force applications, while threats center on geopolitical export controls and proprietary interoperability hurdles.
Value chain analysis from raw materials to defense end-users
The value chain initiates with raw semiconductor and sensor material providers, flowing through hardware manufacturers and core software developers like Synopsys. System integrators then package these elements into deployable solutions for branches like the Army, Navy, and Air Force.
Strategic investment insights and high-potential areas
High-potential investment areas concentrate on artificial intelligence and machine learning software, alongside edge computing hardware. Investors should prioritize firms demonstrating strong cybersecurity protocols and seamless cloud-to-edge deployment capabilities tailored for tactical military environments.
Conclusion and key takeaways for defense stakeholders
The Military Digital Twin Market is transitioning from experimental trials to core operational infrastructure, targeting $20.02 Billion by 2033. Stakeholders must prioritize open architecture software integration and robust data management to capture maximum value from this rapid expansion.
Research methodology for baseline estimations and triangulation
Our analysis triangulates data by combining exhaustive trade registry reviews, primary stakeholder interviews with defense contractors, and secondary macroeconomic indicators. This multi-tiered approach ensures high fidelity in market sizing and growth projections across all specified segments.
Scope of the report, coverage parameters, and analytical limitations
This report evaluates the global market across specified hardware, software, and service segments from 2026 to 2033. Limitations include restricted access to classified military black-budget projects, focusing instead on publicly disclosed defense digitalization and modernization expenditures.
Recent developments, corporate partnerships, and strategic product launches
Recent market momentum is characterized by strategic partnerships between defense primes like Lockheed Martin Corporation and AI innovators such as Palantir Technologies Inc.. These alliances focus on deploying real-time data integration and advanced simulation tools directly into active operational command centers.