What is the market overview and industry significance of the Radio Frequency (RF) Skin Tightening Machine Market?
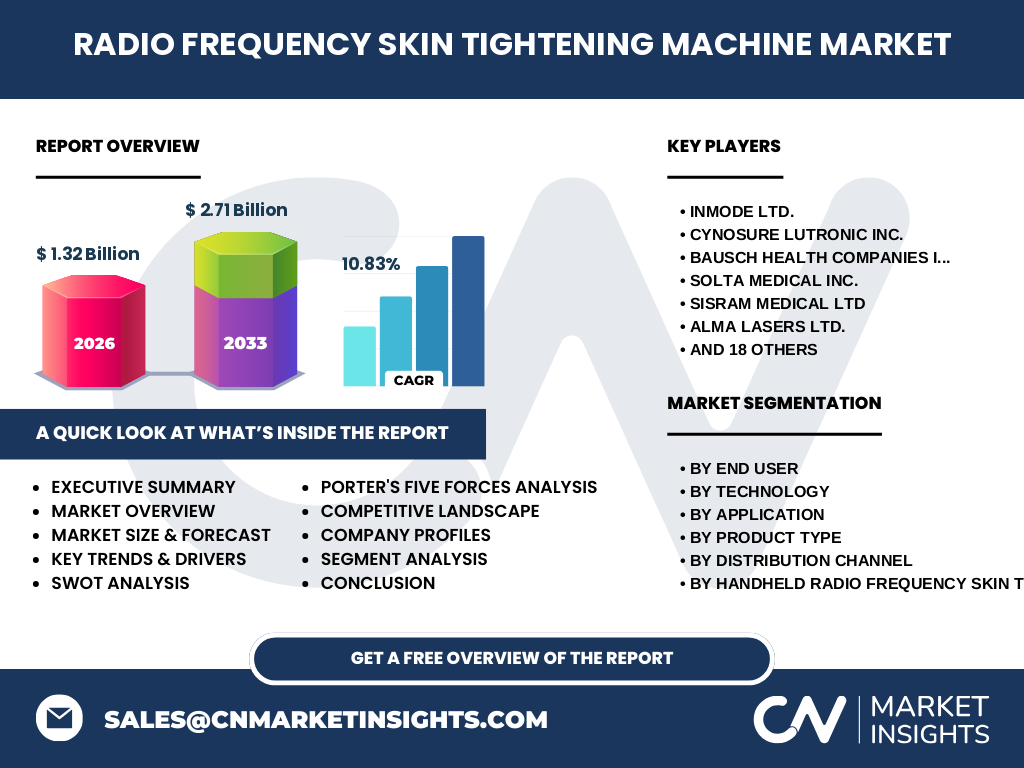
Our analysis indicates that the Radio Frequency (RF) Skin Tightening Machine Market represents a transformative sector within aesthetic medicine, valued at 1.32 Billion in 2026. This industry encompasses energy-based devices utilizing monopolar, bipolar, multipolar, and fractional RF configurations to stimulate neocollagenesis. Regulatory frameworks by bodies like the FDA and EMA govern device safety, ensuring clinical efficacy across dermatology clinics and specialized med-spas.
What are the key market drivers, restraints, challenges, and opportunities shaping the Radio Frequency (RF) Skin Tightening Machine Market?
Growth is propelled by rising consumer demand for non-invasive cosmetic procedures replacing surgical facelifts. However, high capital equipment costs and stringent pre-market clearance hurdles imposed by the FDA act as notable market restraints. Supply chain bottlenecks involving medical-grade gold-plated micro-pins and RF generators present ongoing logistical challenges. Conversely, surging disposable incomes in developing economies unlock lucrative opportunities for portable and home-use device expansion.
Emerging trends and growth patterns in the Radio Frequency (RF) Skin Tightening Machine Market
The data highlights a definitive shift toward smart connected handheld devices and multi-modality platforms combining RF with micro-needling or ultrasound. Innovators such as InMode Ltd. and Alma Lasers Ltd. lead this evolution by integrating real-time impedance monitoring. Patients increasingly favor procedures with zero downtime, fueling adoption in medical spas and high-end beauty and aesthetic centers worldwide.
How did the COVID-19 pandemic impact the Radio Frequency (RF) Skin Tightening Machine Market and shape its recovery trajectory?
Pandemic-induced lockdowns severely disrupted clinical operations, causing an unprecedented contraction in professional device sales across hospitals and cosmetic surgery centers. The subsequent recovery trajectory was sharply defined by the 'Zoom Boom,' as virtual meetings heightened aesthetic self-awareness. This catalyzed rapid post-pandemic bounce-backs, accelerating investments in home care settings and portable rechargeable systems as clinical access normalized.
Competitive Benchmarking: Major players, market concentration, and strategic dynamics
The competitive landscape features intense rivalry among tier-one med-tech leaders including Cynosure Lutronic Inc., Solta Medical Inc., and Bausch Health Companies Inc. Market concentration is moderately high, with established players leveraging proprietary thermal-delivery patents to protect margins. Strategic dynamics focus on aggressive merger and acquisition activities, geographical expansion into APAC, and direct-to-consumer digital marketing for home-use segments.
Executive summary: High-level synthesis of key findings about the Radio Frequency (RF) Skin Tightening Machine Market
Our comprehensive evaluation confirms that the Radio Frequency (RF) Skin Tightening Machine Market is poised for extraordinary expansion, projected to reach 2.71 Billion by 2033 at a robust CAGR of 10.83%. Key value pools concentrate around professional clinic-based systems and dermatology-grade home systems. Stakeholders must prioritize multi-modality integrations and regulatory compliance to capture emerging consumer demographics.
Market forecast: Projected growth from 2027 to 2033
Driven by accelerating technological refinements and broader demographic acceptance of aesthetic treatments, market valuation will climb from 2027 through 2033 to achieve the projected 2.71 Billion milestone. The sustained 10.83% CAGR reflects robust double-digit expansion across both established Western markets and high-growth Asian economies, fueled by rising demand for non-surgical wrinkle and cellulite reduction.
Segmentation analysis: Breaking down categories and their market roles
Market segmentation spans end users (Dermatology Clinics, Medical Spas, Beauty and Aesthetic Centers, Hospitals, Homecare Settings, Cosmetic Surgery Centers), technology types (Monopolar, Bipolar, Multipolar, Fractional RF), applications, product types, and distribution channels. Professional clinic systems dominate revenue share due to high treatment pricing, while home use systems represent the fastest-growing volume segment, democratizing access to skin-tightening technologies.
Regional market analysis and geographic distribution performance
Geographic performance demonstrates clear regional variance influenced by disposable income, cultural attitudes toward aging, and local regulatory clearance speeds. North America commands the largest revenue share, supported by high concentrations of cosmetic surgery centers and dermatology practices. Meanwhile, the Asia-Pacific region exhibits the fastest growth velocity, spearheaded by tech-forward markets adopting advanced smart connected handheld systems.
In-depth regional review of key markets
A closer look at key regional markets reveals that North America benefits from established reimbursement frameworks and high consumer spending on aesthetic maintenance. In contrast, the European market navigates complex Medical Device Regulations (MDR), favoring clinically validated devices from manufacturers like EndyMed Medical Ltd. and Lumenis Ltd. The Asia-Pacific arena thrives on rapid urbanization and high demand for facial skin tightening and body contouring.
Company profiles and strategic positioning of leading market participants
Industry leaders like BTL Industries Inc. and Sisram Medical Ltd differentiate themselves through continuous R&D investment and diverse product portfolios spanning clinic-based and portable modalities. Companies such as Classys Inc. and Jeisys Medical Inc. focus on ergonomic design and cost-effective clinical solutions, capturing substantial market share across competitive domestic and international distribution networks.
Porter's Five Forces analysis of the competitive landscape
The threat of new entrants is moderate, constrained by high R&D expenditures and stringent FDA/CE certification barriers. Bargaining power of buyers is high due to numerous device alternatives available to medical spas. Supplier power remains moderate regarding specialized RF generators and gold-plated tips. Rivalry among existing competitors is intense, pressuring firms to innovate continuously in wrinkle and cellulite reduction applications.
SWOT analysis of the Radio Frequency (RF) Skin Tightening Machine Market
Strengths include high procedure efficacy and minimal recovery times. Weaknesses involve high initial equipment expenditure for clinics. Opportunities lie in expanding smart connected home-use devices and tapping underserved male demographics. Threats encompass stringent regulatory clampdowns and potential adverse events from counterfeit devices distributed through unregulated online stores.
Value chain analysis: Industry structure and value flow from raw materials to end-users
The value chain initiates with raw material suppliers providing medical-grade polymers, titanium, and specialized RF chips. Midstream manufacturers such as Cutera Inc. and Candela Medical assemble sophisticated hardware and proprietary software. Downstream distribution occurs via specialty stores, retail pharmacies, and direct sales channels, ultimately supplying dermatology clinics, hospitals, and direct-to-consumer home care buyers.
Investment insights and strategic recommendations for high-potential areas
Investors should direct capital toward companies pioneering multi-modality home use systems and smart connected handheld devices, as these sub-segments yield superior margin expansion. Strategic partnerships with regional distributors in high-growth Asian markets offer immediate revenue scaling opportunities, circumventing localized import hurdles.
Conclusion and key takeaways for industry stakeholders
The Radio Frequency (RF) Skin Tightening Machine Market presents compelling financial prospects, anchored by a projected 2.71 Billion valuation by 2033. Success requires balancing clinical-grade efficacy in professional dermatology settings with consumer-friendly innovations in home-use portable devices, all while navigating evolving regulatory mandates.
Research methodology: Triangulating baseline estimates and market data
Our baseline estimates are rigorously triangulated by combining customs trade registry data, primary stakeholder interviews with key opinion leaders in dermatology, and secondary macroeconomic indicators. We cross-reference manufacturer shipment reports with clinical procedure volume databases to ensure absolute accuracy in sizing the 1.32 Billion baseline market.
Scope of the report: Coverage parameters and analytical limitations
This report covers global market sizing, segment analysis across technologies and end users, and competitive benchmarking from 2026 through the 2.71 Billion forecast horizon in 2033. Limitations include potential delays in government regulatory filings and fluctuations in macroeconomic currency exchange rates affecting cross-border device shipments.
Recent developments: Company announcements, product launches, and strategic moves
Recent industry developments highlight aggressive portfolio expansions, exemplified by Venus Concept Inc. and Sinclair EBD launching upgraded multi-polar RF platforms designed for enhanced patient comfort. Strategic acquisitions by major conglomerates underscore an industry-wide race to capture market share in both professional clinic systems and smart connected homecare segments.