What is the market overview of the Grenache Blanc Wine Market?
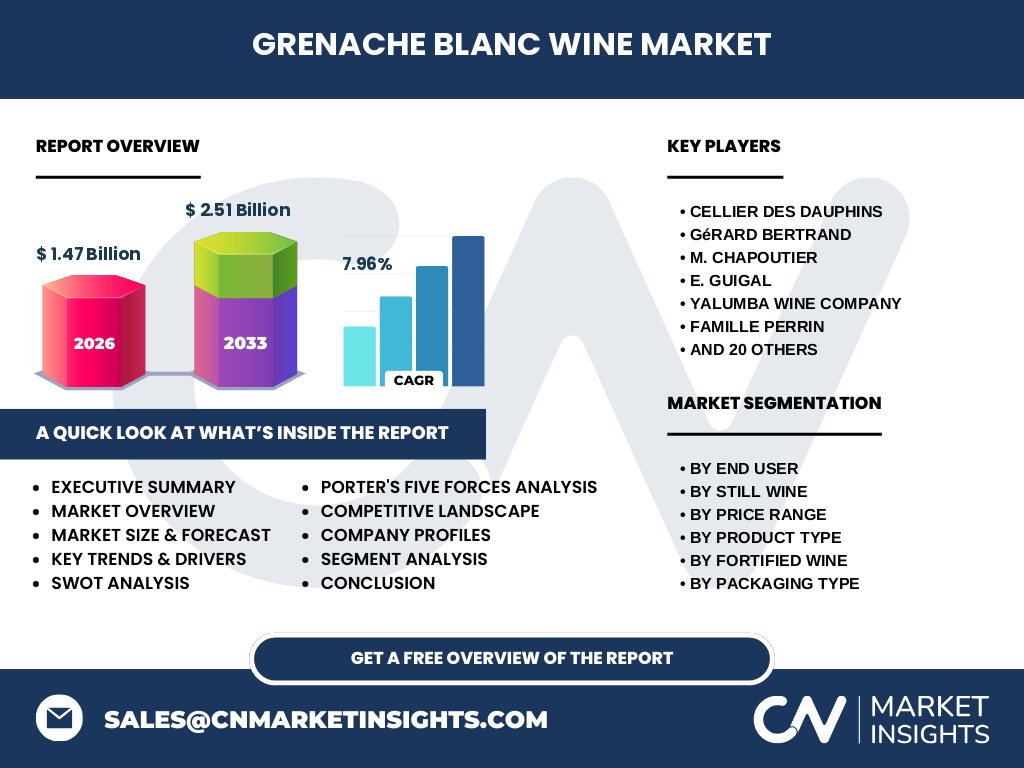
The Grenache Blanc Wine Market represents a dynamic sector within global viticulture, valued at 1.47 Billion in 2026. This market encompasses the production, distribution, and consumption of varietal and blended wines derived from the white mutation of the Grenache grape. Regulatory oversight from bodies like the TTB and OIV ensures strict geographical indications, particularly in its historic heartlands of the Rhône Valley and Catalonia.
Structural Growth Drivers and Market Restraints
Key growth is propelled by consumer demand for food-friendly, textured white wines, alongside rising plantings in regions like South Australia and Paso Robles. However, climate change-induced droughts and extreme heat events pose severe agricultural restraints. Producers face logistical hurdles in temperature-controlled maritime shipping from southern European ports to North American distribution hubs.
Emerging Trends and Growth Patterns in Grenache Blanc Wine Market
A distinct consumer pivot toward minimal intervention winemaking and skin-contact orange wines is reshaping the Grenache Blanc Wine Market industry trends. Producers are increasingly utilizing concrete egg fermenters and amphorae. This technical shift favors innovative estates capable of marketing terroir-driven, lower-intervention expressions to younger demographics.
COVID-19 Impact Analysis and Recovery Trajectory
The pandemic severely disrupted the on-premise hospitality channel, causing historic contractions in restaurant and bar wine sales. Recovery has been spearheaded by a surge in direct-to-consumer digital sales and off-premise supermarket retail. Producers adapted by pivoting packaging formats toward bag-in-box and canned options to capture stay-at-home consumption occasions.
Competitive Benchmarking in the Grenache Blanc Wine Market
The market exhibits a moderately fragmented competitive landscape blending historic European houses with agile New World operators. Key participants such as Gérard Bertrand, M. Chapoutier, and Tablas Creek Vineyard leverage biodynamic certifications and sustainable viticulture to capture high-margin premium segments against mass-market volume producers.
Executive Summary of the Grenache Blanc Wine Market
Our analysis indicates the Grenache Blanc Wine Market will expand from 1.47 Billion in 2026 to reach 2.51 Billion by 2033, achieving a robust CAGR of 7.96%. This trajectory underscores strong consumer migration toward aromatic, food-versatile white varietals, driven by premiumization across both established European appellations and emerging New World terroirs.
Market Forecast: 2027 to 2033 Projections
Projected to scale from 2027 through 2033 at a compound annual growth rate of 7.96%, the market will culminate in a valuation of 2.51 Billion. This expansion is underpinned by escalating investments in cellar-door tourism, expanded vineyard acreage in McLaren Vale and Swartland, and widening distribution via e-commerce channels.
Segmentation Analysis of the Grenache Blanc Wine Market
The market is segmented by end user into household consumers, restaurants and bars, and hotels. By still wine, it covers dry, semi-dry, and sweet still wine. Price ranges span economy, mid-range, and premium tiers. Product types include still, sparkling (brut, extra dry, demi sec), and fortified wines (sweet, dry, aromatized). Packaging encompasses bottles, cans, and bag-in-box, distributed via online stores, supermarkets, and specialty shops.
Regional Market Analysis and Geographic Distribution
Geographic performance highlights Western Europe as the historical consumption and volume leader, anchored by French and Spanish appellations. Concurrently, North America and Australasia represent the fastest-growing regional pockets, fueled by adventurous consumer adoption in urban centers and dedicated plantings by innovators like Ricca Terra Farms Pty Ltd..
In-Depth Regional Review
In Southern France and Northeastern Spain, strict Appellation d'Origine Contrôlée regulations dictate yield limits and blending ratios, preserving heritage styles. Conversely, regions like California's Central Coast and South Africa's Piekenierskloof benefit from regulatory flexibility, allowing winemakers such as Halter Ranch Vineyard and Piekenierskloof Wine Company to experiment with single-varietal expressions and skin-contact protocols.
Strategic Company Profiles
Industry leaders maintain distinct strategic positioning. E. Guigal and Famille Perrin focus on heritage-driven Rhône blends, whereas Bonny Doon Vineyard and Aphelion Wines Co. champion avant-garde, site-expressive single-varietal bottlings. Meanwhile, Yalumba Wine Company utilizes proprietary old-vine sourcing to command premium price points in export markets.
Porter's Five Forces Analysis of Competitive Pressures
Bargaining power of buyers remains moderate to high due to extensive private-label supermarket offerings. Supplier power is constrained by agricultural land availability in prime Mediterranean climates. Threat of substitutes is elevated given intense competition from Sauvignon Blanc and Chardonnay, while rivalry among established houses like Château de Beaucastel and Domaine de la Janasse drives continuous quality elevation.
SWOT Analysis of the Grenache Blanc Industry
Strengths include the grape's natural drought tolerance and adaptability to warming climates. Weaknesses involve susceptibility to oxidation during vinification. Opportunities lie in expanding canned and bag-in-box packaging for outdoor demographics. Threats stem from unpredictable spring frosts and global supply chain disruptions impacting dry glass bottle availability.
Value Chain Analysis from Raw Materials to End-Users
The value chain initiates with viticulturists managing rootstock selection and canopy management in arid soils, flowing through mechanical or hand-harvesting into stainless steel or oak fermentation vessels. Bottling and packaging leverage regional logistics hubs before distribution through specialized wine merchants, major supermarkets, and direct-to-consumer digital platforms.
Investment Insights and High-Potential Areas
Investors should target premium organic tier production and direct-to-consumer e-commerce infrastructure. Wineries incorporating sustainable dry-farming techniques in regions like McLaren Vale and the Southern Rhône offer superior risk-adjusted returns, mitigating long-term water scarcity risks while capturing high-margin consumer demand.
Conclusion and Key Takeaways
The Grenache Blanc Wine Market analysis confirms a high-growth trajectory, surging to 2.51 Billion by 2033 at a 7.96% CAGR. Success in this landscape requires balancing traditional viticultural heritage with modern packaging innovations and agile digital distribution strategies.
Research Methodology
Our research methodology triangulates bottom-up volumetric production data from trade registries such as the OIV with primary executive interviews from key stakeholders including Cellier des Dauphins and M. Chapoutier. This is synthesized alongside macroeconomic indicators like disposable income trends and hospitality index metrics.
Scope of the Report and Limitations
This report covers global market sizing, segmental breakdowns, and competitive benchmarking from 2026 to 2033. Limitations include inherent fluctuations in agricultural harvest yields driven by localized weather anomalies and unrecorded informal direct-to-consumer local cellar sales in rural European enclaves.
Recent Developments and Strategic Moves
Recent industry momentum features Gérard Bertrand expanding its biodynamic vineyard acquisitions across Languedoc, and Tablas Creek Vineyard pioneering regenerative organic certification standards. Furthermore, several Australian producers have introduced lightweight glass bottles to reduce carbon footprints during export transit.