Market overview and structural significance of the Reusable Syringe Market
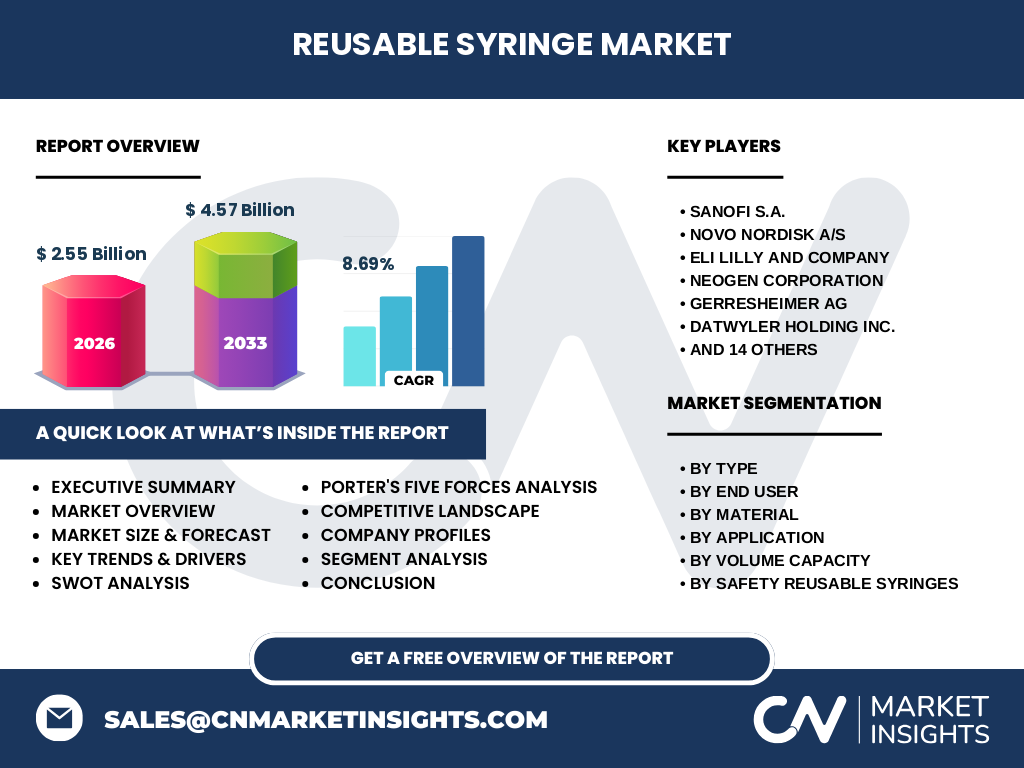
Our analysis indicates that the Reusable Syringe Market represents a critical paradigm in sustainable healthcare delivery, valued at $2.55 Billion in 2026. This sector encompasses durable administration tools crafted from stainless steel, glass, and high-performance polymers, serving critical functions across immunization campaigns and chronic disease management while addressing mounting medical waste liabilities governed by the World Health Organization.
Structural Growth Drivers and Market Restraints
The market is propelled by stringent environmental mandates reducing single-use plastics, contrasted with stringent sterilization validation protocols acting as operational restraints. Key opportunities lie in precision engineering for veterinary clinics and pharmaceutical laboratories, where industry leaders like Neogen Corporation and Hamilton Company innovate to bypass supply chain bottlenecks tied to specialized raw material sourcing.
Emerging Trends and Technological Evolution
The industry is witnessing an accelerated pivot toward passive safety mechanisms and ergonomic precision, directly influencing how clinical facilities handle high-volume vaccination drives. Innovations from firms like Portal Instruments Inc. highlight a broader shift toward needle-free and advanced reusable delivery systems, optimizing fluid delivery accuracy across Low Volume Up To One Milliliter configurations.
Pandemic Aftershocks and Recovery Trajectory
While COVID-19 initially triggered an unprecedented surge in disposable plastic injection devices, our research shows a post-pandemic strategic realignment favoring supply chain resilience. Healthcare systems globally are diversifying procurement streams, prioritizing durable glass standard reusable syringes to mitigate future single-use logistical vulnerabilities and container shortages.
Competitive Benchmarking and Market Concentration
The competitive landscape is moderately consolidated, featuring specialized medical device manufacturers such as Gerresheimer AG and Ypsomed Holding AG dominating proprietary delivery hardware. Strategic positioning hinges on ISO 13485 compliance, advanced polymer molding capabilities, and established distribution channels catering to institutional hospital networks and specialized veterinary entities.
Executive Summary of the Reusable Syringe Market
Our comprehensive evaluation confirms that the global sector is poised for robust expansion, projecting a valuation of $4.57 Billion by 2033 at a notable 8.69% CAGR. Growth is anchored by increasing chronic disease prevalence, stringent institutional biosafety mandates, and the commercial rollout of advanced pen-compatible and Enfit-compatible enteral delivery systems.
Market Forecast and Valuation Trajectory from 2027 to 2033
Driven by rising healthcare expenditure and widespread adoption of Insulin Reusable Syringes, the market will expand decisively from its 2026 baseline. Analysts forecast consistent upward momentum through 2033, supported by high-margin segments including adjustable dose insulin delivery tools and high-volume industrial dispensing units.
Segmentation Analysis Across Product, End User, and Material Matrix
The market segments into diverse categories by type, end user, material, application, and volume capacity. Hospitals And Clinics represent the dominant end-user category, while Stainless Steel and Glass maintain foundational roles in precision medical applications, contrasted by specialized Enteral Reusable Syringes utilized in clinical nutrition.
Regional Market Analysis and Geographic Distribution
Geographically, the market exhibits mature demand across North America and Europe, underpinned by stringent hospital waste reduction policies enforced by regional environmental protection agencies. Concurrently, Asia-Pacific emerges as the fastest-growing region, driven by expanding veterinary sectors and modernization initiatives across clinical infrastructure in emerging economies.
In-Depth Regional Review of Key Healthcare Hubs
North America leads consumption due to robust adoption of advanced safety mechanisms by major hospital groups, whereas Europe benefits from stringent regulatory frameworks promoting sustainable medical procurement. Key regional players like Vygon SA and ARDES Group leverage localized distribution hubs near primary maritime ports to optimize supply chain velocity.
Company Profiles and Strategic Positioning
Industry stalwarts such as Sanofi S.A., Novo Nordisk A/S, and Eli Lilly and Company anchor the therapeutic application space through proprietary drug-delivery integration. Meanwhile, component and device specialists like Datwyler Holding Inc. and Nemera France SAS focus on elastomer sealing innovations and user-centric actuation designs.
Porter's Five Forces Analysis of Competitive Dynamics
Supplier power remains moderate due to specialized medical-grade polymer and borosilicate glass requirements, whereas buyer power is high among large hospital group purchasing organizations. The threat of substitution is mitigated by strict regulatory approvals required for clinical reusable apparatus, maintaining elevated barriers to entry.
SWOT Analysis of the Global Industry
Key strengths include high durability and long-term cost-efficiency for clinical institutions, offset by weaknesses tied to intensive sterilization overhead. Opportunities abound in emerging veterinary markets and smart-syringe connectivity, while regulatory compliance shifts and cross-contamination liabilities represent persistent industry threats.
Value Chain Analysis from Raw Materials to End-Users
The value chain initiates with raw material extraction of stainless steel, borosilicate glass, and engineering plastics, progressing through high-precision injection molding and cleanroom assembly. Finished devices flow through sterilized packaging logistics directly to clinical end-users, diagnostic laboratories, and pharmaceutical contract manufacturing organizations.
Investment Insights and High-Potential Areas
Strategic capital allocation should target manufacturers developing passive safety reusable syringes and pen-compatible insulin delivery systems. Investors will capture optimal value by supporting firms with proprietary sterilization validation workflows and established distribution footprints within high-growth veterinary and clinical segments.
Conclusion and Strategic Key Takeaways
The transition toward sustainable clinical practices solidifies the long-term viability of the sector, projecting a secure financial trajectory toward 2033. Organizations that successfully balance ergonomic innovation with rigorous sterilization standards will capture disproportionate market share across both human healthcare and veterinary applications.
Research Methodology and Data Triangulation
Our baseline estimates are rigorously triangulated by synthesizing trade registry data, primary stakeholder interviews with chief procurement officers, and secondary macroeconomic indicators from global health organizations. This multi-tiered methodology reconciles shipment volumes, manufacturing capacities, and regulatory filings to ensure precise market sizing.
Scope of the Report and Analytical Parameters
This report evaluates the global market across defined material, application, volume capacity, and end-user verticals from 2026 through 2033. Geographic limitations and macroeconomic variables such as foreign exchange fluctuations are factored into our predictive econometric models to maintain analytical integrity.
Recent Developments and Industry Announcements
Recent strategic moves feature collaborative partnerships between device innovators like SHL Medical AG and pharmaceutical leaders to co-develop sustainable delivery ecosystems. Companies such as Owen Mumford Ltd. and Henke Sass Wolf GmbH have also rolled out advanced mechanical locking mechanisms to enhance user safety during high-frequency clinical administration.