Market overview and structural significance of the Long-Acting Injectables (LAIs) Market
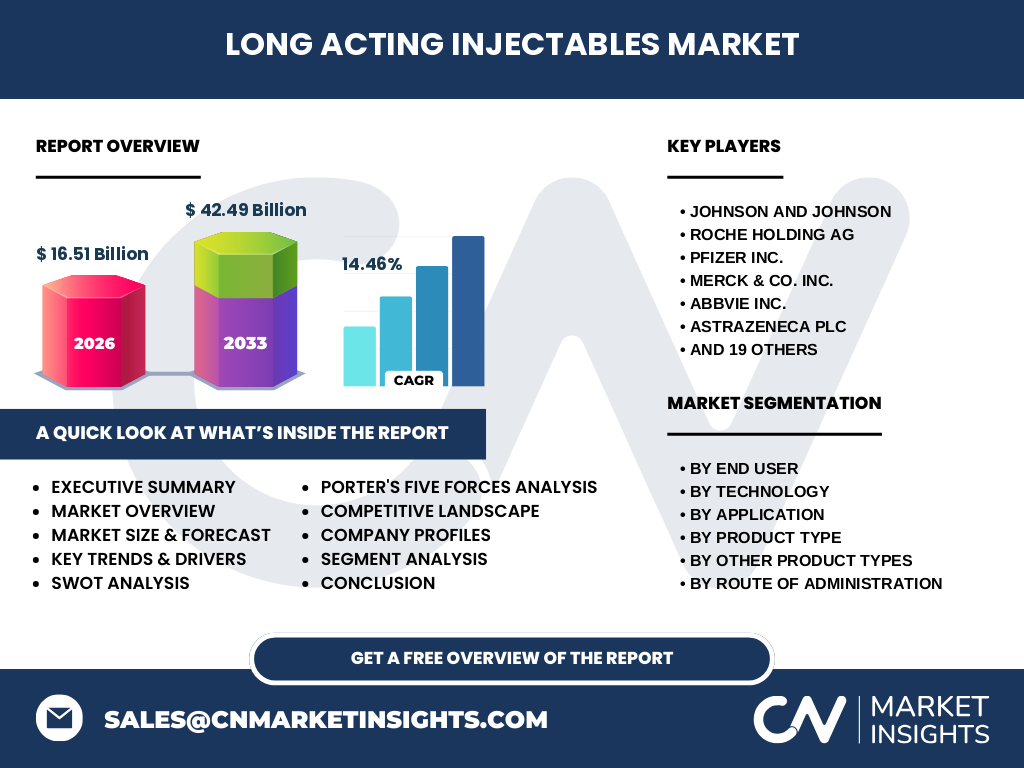
The Long-Acting Injectables (LAIs) Market represents a transformative pharmaceutical paradigm, engineered to maintain sustained therapeutic plasma drug levels over weeks or months. Valued at 16.51 Billion in 2026, this sector minimizes the pharmacokinetic peaks and valleys associated with daily oral dosing, fundamentally mitigating non-adherence risks in chronic conditions like schizophrenia and HIV.
Structural Growth Drivers and Market Restraints
Primary growth drivers include rising patient compliance demands and sophisticated delivery innovations. However, the market faces significant restraints, notably complex aseptic manufacturing validation protocols mandated by the FDA and EMA, alongside cold-chain logistical bottlenecks required for sensitive polymer matrices and liposomal suspensions in remote distribution hubs.
Emerging trends and formulation evolution in the Long-Acting Injectables (LAIs) Market industry trends
The sector is witnessing a decisive pivot toward Nano Formulations and In Situ Forming Depots, offering superior biocompatibility and reduced injection-site reactions. Innovations in biodegradable poly(lactic-co-glycolic acid) (PLGA) copolymers are enabling more predictable degradation rates, allowing developers to extend dosing intervals beyond traditional multi-week windows.
COVID-19 operational impact and supply chain resilience
The pandemic severely disrupted global clinical trials and active pharmaceutical ingredient (API) procurement. Nevertheless, the post-pandemic recovery trajectory highlights robust bounce-back metrics, as healthcare systems prioritize long-acting therapies to reduce hospital visit frequencies and protect immunocompromised patients from nosocomial infection vectors.
Competitive Benchmarking and Industry Consolidation
Market concentration is high, dominated by biopharma giants leveraging proprietary delivery platforms. Firms like Johnson & Johnson and Pfizer Inc. utilize aggressive portfolio expansions and patent life-cycle management strategies, while specialty players like Alkermes plc focus on proprietary nanocrystal technologies to secure defensible market niches.
Executive summary of the Long-Acting Injectables (LAIs) Market analysis
Our comprehensive analysis confirms that the Long-Acting Injectables (LAIs) Market is entering a hyper-growth phase, projected to surge to 42.49 Billion by 2033 at a remarkable CAGR of 14.46% from 2027. This acceleration is propelled by breakthrough approvals in antiviral and antipsychotic depots.
Market forecast trajectory from 2027 to 2033
Driven by accelerating R&D investments and expanding clinical indications, the market is set to expand rapidly from its 2026 baseline. The data suggests that sustained adoption of Cabotegravir Extended Release Injection and Paliperidone Palmitate Injection will be primary catalysts fueling this multi-billion-dollar expansion.
Detailed segmentation analysis across technologies and end users
Segmentation spans multiple dimensions:
- By Technology: Microsphere Based Formulations, Polymer Based Depot Systems, Nano Formulations, Liposomal Delivery Systems, In Situ Forming Depots.
- By End User: Hospitals, Specialty Clinics, Ambulatory Surgical Centers, Homecare Settings, Specialty Pharmacies.
Geographic distribution and regional market performance
Regional performance varies based on healthcare reimbursement infrastructure and regulatory agility. North America maintains revenue dominance due to entrenched chronic disease management frameworks, while Asia-Pacific emerges as the fastest-growing region, bolstered by expanding domestic contract manufacturing organizations (CMOs) and rising biologic investments.
In-depth regional review of regulatory and clinical environments
North American growth is underpinned by favorable FDA expedited review pathways for complex generics. Conversely, European markets navigate stringent pricing controls enforced by EMA member states, while emerging economies face localized reimbursement hurdles that temper the rapid uptake of high-cost branded depot systems.
Strategic positioning in company profiles
Industry leaders maintain distinct strategic positioning. ViiV Healthcare dominates antiviral depots with Cabotegravir and Rilpivirine, whereas Otsuka Pharmaceutical Co Ltd. and Janssen lead the neuropsychiatric segment with advanced atypical antipsychotic formulations, maximizing patent protections against biosimilar erosion.
Porter's Five Forces competitive intensity assessment
The threat of new entrants is moderate-to-high due to severe barrier-to-entry dynamics imposed by complex scale-up manufacturing and stringent bioequivalence testing. Bargaining power of suppliers is low for standard excipients but high for proprietary polymers, while competitive rivalry remains intense among established tier-one pharmaceutical titans.
SWOT evaluation of the Long-Acting Injectables (LAIs) Market
Strengths include high patient adherence rates and strong IP protection; weaknesses involve intricate manufacturing scaling challenges. Opportunities lie in expanding into oncology and metabolic disorders, whereas threats include potential regulatory pushback on complex generic approvals and alternative oral drug delivery technologies.
Value chain analysis from raw materials to end-users
The value chain initiates with raw polymer and API synthesis, moving through sophisticated aseptic fill-finish contract manufacturing. It extends via specialized cold-chain logistics to hospitals, specialty clinics, and homecare settings, where clinical administration requires specialized healthcare professional training.
High-potential investment insights and strategic recommendations
Investors should target early-stage developers specializing in In Situ Forming Depots and subcutaneous sustained-release platforms. Strategic partnerships with established CMOs possessing dedicated sterile injectable fill-finish lines will mitigate commercialization risks and accelerate time-to-market.
Conclusion and strategic takeaways for industry stakeholders
In summary, the Long-Acting Injectables (LAIs) Market offers exceptional growth prospects, substantiated by a robust 14.46% CAGR. Stakeholders must prioritize formulation innovation, navigate complex regulatory landscapes proactively, and secure reliable supply chain partnerships to capture maximum market value.
Robust research methodology and triangulation framework
Our baseline estimates are rigorously triangulated by combining exhaustive trade registry data, primary qualitative interviews with C-suite biopharma executives, and secondary macroeconomic indicators from global health organizations, ensuring high-fidelity market sizing and predictive accuracy.
Scope of the report, coverage parameters, and analytical limitations
This report covers global revenue performance across all specified therapeutic applications, routes of administration, and technology types from 2026 to 2033. Limitations include unforeseen geopolitical trade disruptions and shifting national healthcare reimbursement policies that may influence regional adoption speeds.
Recent developments, corporate partnerships, and product launches
Recent milestones feature aggressive pipeline expansions by key players like Gilead Sciences Inc. and Novo Nordisk A/S, focusing on long-acting viral suppression and metabolic disorder depots. Strategic acquisitions of smaller drug-delivery innovators highlight an industry-wide push to secure next-gen polymer and nano-formulation assets.